

A bank can invest millions in digital transformation, select a leading technology platform, hire an award-winning UX design agency and launch a beautifully executed banking app—only to discover that customers see little difference between its experience and dozens of competitors. The problem may not be poor design. It may be something far more expensive: choosing a partner capable of executing the bank's decisions, but not challenging whether those decisions were strategically right.
A bank can spend millions on digital transformation, select a leading technology platform, hire an award-winning UX agency and launch a beautifully designed mobile app—only to discover that customers see little difference between its experience and dozens of competing banks. Nothing may be fundamentally wrong with the execution.
The interfaces are polished. The design system is consistent. The application passes usability tests. Every requested feature has been delivered. The problem began much earlier.
The bank chose a partner to design what had already been decided, rather than one capable of challenging whether those decisions would create meaningful customer and business value. This is one of the most expensive mistakes financial institutions can make: confusing design capability with strategic experience expertise.
At UXDA, we believe that evaluating a strategic financial UX partner requires looking beyond agency portfolios, design awards and delivery capacity. Banks need to assess the quality of strategic judgment behind the design, the depth of financial expertise, the ability to challenge assumptions and the governance mechanisms that ensure thousands of individual decisions reinforce one coherent experience. Because the wrong partner may deliver exactly what the bank requested—and that may be the most expensive outcome of all.
As banks invest in AI, digital ecosystems, next-generation platforms and large-scale transformation, choosing a UX partner is no longer simply a procurement decision about who can deliver the best interfaces. It is a strategic decision about who can help the institution define its future digital experience, differentiate its brand, align complex stakeholders and protect transformation value over time.
The question is not whether a UX partner can design an outstanding banking app. It is whether that partner can help a bank avoid investing millions in becoming one more instead of one of a kind.
Why Choosing a Banking UX Partner Is a Strategic Decision, Not a Design Procurement Task
Imagine a bank preparing for a major digital transformation.
The technology platform has been selected. The budget is approved. The delivery roadmap is ambitious. The internal teams have collected requirements from business units, and procurement begins searching for a banking UX agency to redesign the customer experience.
Several candidates present impressive portfolios. One has won international awards. Another has worked with top tech brands. A third promises to deliver hundreds of polished screens within an aggressive timeline.
All demonstrate strong design capabilities. But what if the bank's biggest problem is not the quality of pixels?
What if its products are fragmented across departments? Its brand promises simplicity while its processes create unnecessary complexity? Its customer journeys are built around internal operations rather than financial needs? Or its future platform is being designed to reproduce the same experience customers can already find at competing banks?
An excellent design team could execute every requirement perfectly and still fail to address these challenges. Because the most consequential decisions may have been made before the first screen was designed. This is the difference between purchasing UX design services and establishing a strategic financial UX partnership.
A traditional design engagement often begins with a defined problem and a requested deliverable. A strategic engagement must be capable of questioning both.
The real value of a strategic banking UX partner is not simply delivering what the bank requests. It is helping the bank determine what is worth building, why it matters and how the resulting experience can create lasting competitive advantage.
At UXDA, we believe the selection of a financial UX partner should be evaluated at the same level of strategic importance as other decisions shaping a major digital transformation. Because the chosen partner may influence thousands of decisions about customer behavior, product architecture, financial understanding, trust, Digital Brand Identity and the long-term coherence of the banking ecosystem.
And those decisions determine how much of the bank's transformation investment actually reaches the customer.
What Is a Strategic Banking UX Partner?
A strategic banking UX partner is a specialist organization that helps financial institutions research, define, design and govern customer experiences across digital products, journeys and channels.
Unlike an execution-focused UX supplier, a strategic partner contributes to decisions about customer needs, business objectives, product direction, digital differentiation, experience architecture and the governance mechanisms needed to maintain consistency over time.
The distinction is not simply the range of design services offered. It is the level at which the partner contributes to the institution's decisions.
A UX design agency may be engaged to improve an existing mobile banking application, redesign onboarding or develop a new interface. A strategic financial UX partner should also be able to ask:
- Is the institution solving the right customer problem?
- Does the proposed product direction support its long-term business strategy?
- What makes the experience meaningfully different from competitors?
- Are product and channel decisions reinforcing one coherent Digital Brand Identity?
- How will internal teams and technology vendors maintain that direction?
- What evidence demonstrates that the transformation is creating value?
These questions extend beyond individual screens and usability improvements. They concern the entire relationship between the financial institution and its customers.
A useful distinction is that execution-focused UX improves how a solution works, while strategic UX challenges what the solution should achieve and how it contributes to the larger experience system.
Both capabilities are important. But when banks are investing in institution-wide transformation, execution without strategic direction can make the wrong decisions more expensive.
This is why UXDA approaches Digital Banking UX Strategy as Strategic Infrastructure—an institutional capability that connects business strategy, customer experience, technology, brand and governance.
Why an Impressive UX Portfolio Is No Longer Enough
A portfolio can demonstrate visual quality, interaction craftsmanship and experience across multiple industries. It can show what a team is capable of designing. But it rarely tells the full story of what the team was capable of deciding.
A beautiful banking interface does not reveal whether the team challenged a weak product proposition, identified a critical customer need, prevented unnecessary development, aligned conflicting stakeholders or established an experience system that could evolve without fragmentation.
It also does not establish whether the product succeeded after implementation. This is particularly important in financial services, where visually similar interfaces may support fundamentally different customer needs and business models.
Consider the differences between retail banking, wealth management, SME banking, trading, insurance and Islamic banking.
A retail customer may prioritize everyday financial clarity and effortless payments. A wealth management client may need to understand complex portfolio exposure and investment decisions. A small business owner may require cash-flow visibility, multi-user approvals and operational control. A trader may prioritize execution speed, accurate market information and risk transparency.
A universal visual template cannot adequately solve all these problems. Yet financial product portfolios are often judged primarily by screenshots. This encourages banks to compare visual outputs rather than the strategic reasoning behind them.
The danger becomes greater when a transformation brief asks vendors to reproduce features and patterns already used by successful competitors. Copying familiar interactions can improve usability. But copying the entire experience strategy rarely creates lasting differentiation.
As we explore in our perspective on Digital Banking Clone Wars, financial institutions risk becoming increasingly interchangeable when standardization extends beyond proven usability patterns into their entire product identity.
The strongest UX partner should understand which conventions customers need—and where the bank must establish something distinctive.
A portfolio shows what a UX partner can design. Strategic expertise reveals what a bank should build.
That distinction should guide the entire evaluation process.
The Financial UX Challenge: More Technology Does Not Automatically Mean More Customer Value
The financial industry has made significant progress in digitalizing products and services. Banks offer increasingly sophisticated mobile apps, digital onboarding, integrated payments, investment capabilities, personalization and AI assistance. But the availability of advanced functionality does not necessarily translate into a distinctive or coherent customer experience.
Deloitte's Digital Banking Maturity 2024 study evaluated 349 banks across 44 countries, analyzing 1,005 digital banking functionalities. The strategic challenge for banks is no longer simply identifying which features competitors offer. It is determining which capabilities create meaningful customer value, which should be prioritized and how they can operate together as a coherent experience.
McKinsey's 2025 research on world-class mobile banking apps found that leading mobile banks resolve more than 80% of routine interactions within the app. These institutions generate 51% more annual customer touchpoints and approximately twice the mobile-driven sales and new customer acquisitions compared with the global average.
These results illustrate the commercial importance of strong digital banking experiences. They do not mean that interface redesign alone produces such outcomes.
McKinsey emphasizes that leading experiences depend on coordinated capabilities, including intuitive design, personalization, predictive engagement and intelligent movement between channels. The transformation challenge is systemic.
Meanwhile, Accenture's Banking Consumer Study 2025, based on 49,300 customers across 39 countries, found that 73% engage with banks beyond their primary institution. The study also reported that banks with the highest customer advocacy scores experienced 1.7 times faster revenue growth than their peers.
The implication is important. Customers have more financial relationships available to them, while digital functionality alone is becoming less effective as a source of differentiation. Banks must increasingly earn customer preference through relevance, trust, confidence and the quality of their overall experience.
A strategic UX partner should help translate these competitive realities into decisions about the institution's digital future. Not merely make existing functionality look better.
How to Choose a Strategic Banking UX Partner: 10 Essential Evaluation Criteria
A financial institution should evaluate a UX partner against its ability to reduce strategic uncertainty, shape meaningful customer value, create differentiation and maintain experience coherence through transformation.
We recommend ten criteria that examine the decisions behind the design—not simply the visible results.
1. Financial Industry Expertise: Do They Understand Banking Beyond the Interface?
The first criterion is genuine specialization in financial services.
Banks operate in environments shaped by financial behavior, operational complexity, regulatory obligations, security, risk and customer trust. A design decision that appears straightforward in another industry can have significant consequences in banking.
Simplifying a payment journey must not compromise transaction clarity. Making an investment interface more engaging must not conceal risk. Reducing onboarding steps must not undermine required verification.
A partner should understand how these requirements influence customer psychology, information architecture and interaction design. But financial expertise should extend beyond familiarity with industry terminology.
It should include the ability to understand complex financial products, different customer segments, business objectives and the operational processes behind digital interactions.
What to evaluate: Ask the partner to explain a difficult financial UX problem and demonstrate how domain expertise changed the solution.
2. Strategic Diagnosis: Can They Challenge the Problem Before Designing the Solution?
Many banking redesigns begin with a conclusion presented as a problem.
- Our app looks outdated.
- Our onboarding has too many steps.
- Competitors have launched AI assistants.
- We need a new dashboard.
These observations may be valid. But they do not necessarily identify the underlying challenge.
An outdated-looking app may also suffer from fragmented product architecture. Low onboarding conversion may reflect weak customer understanding, unnecessary operational requirements or an unsuitable proposition. An AI assistant may automate a service experience that should first be simplified.
A strategic UX partner should investigate the problem before accepting the proposed solution. At UXDA, we consider this one of the most important distinctions between tactical delivery and strategic partnership.
The value of expertise is not demonstrated by agreeing with the brief. It is demonstrated by improving the quality of the decisions behind it.
What to evaluate: Present an incomplete or deliberately challenging brief. Examine the questions the partner asks before proposing a solution.
3. Customer Research: Can They Validate Assumptions Before They Become Expensive?
Banks make expensive decisions based on assumptions about what customers understand, value and expect.
These assumptions may originate from executive opinions, competitor benchmarks, product performance or historical business practices. Some will be correct. Others may be outdated, incomplete or misleading.
A strategic partner must be able to distinguish between them through appropriate research. This involves more than conducting usability tests after the interface has been designed.
Research should influence which problems deserve investment, how customer segments differ, what behaviors create friction and which opportunities have the strongest potential. The objective is to reduce uncertainty before it becomes embedded in product specifications, technology decisions and implementation costs.
What to evaluate: Request examples where research contradicted the initial brief and materially changed the project's direction.
4. Experience North Star: Can They Define Where the Bank Should Go?
A major transformation may involve hundreds of stakeholders, thousands of screens, multiple technology vendors and years of development. Without a clear strategic experience direction, individual teams can make locally reasonable decisions that collectively produce fragmentation.
An Experience North Star provides a shared reference point for evaluating these decisions. It defines what the institution wants customers to experience, how that ambition supports business strategy and which principles should remain consistent over time.
This should be more specific than generic aspirations such as simple, seamless and customer-centric. Almost every bank wants those qualities.
A distinctive North Star must explain what makes the institution's experience valuable in its particular market, customer context and strategic position.
What to evaluate: Ask the partner to explain how it would establish a North Star and translate it into specific product and organizational decisions.
5. Digital Brand Identity: Can They Create Differentiation Beyond Best Practices?
Banking interfaces increasingly share similar navigation, account cards, payment shortcuts and financial dashboards. Some similarity is necessary because familiar patterns reduce customer effort. But there is a difference between using proven interaction conventions and reproducing an entire competitor's experience.
A strategic UX partner should help banks establish a distinctive Digital Brand Identity. That means translating brand values into how the institution communicates, behaves, guides decisions and supports customers digitally.
A premium financial brand should not rely only on elegant visuals. A bank promising empowerment should help customers understand and control their finances. A bank promising simplicity should not expose customers to unnecessary organizational complexity. Its digital experience should make the brand promise true.
What to evaluate: Look beyond visual identity. Ask how the partner connects brand strategy with information architecture, interaction behavior, communication and customer relationships.
6. Systemic UX Thinking: Can They Design Beyond a Single Product?
Customers do not experience banks through isolated screens. They move between websites, onboarding processes, mobile apps, support channels, branches, payment systems and financial products. A solution that improves one touchpoint can still create problems elsewhere.
For example, a digital loan application may be easy to complete while the subsequent approval and fulfillment process remains confusing. A mobile app may provide excellent self-service while the contact center cannot access the customer's journey context. A redesign may modernize one product while increasing inconsistency across the larger banking ecosystem. A strategic partner must understand these relationships.
As UXDA explains in Bank-as-a-Product: Why a Mobile Banking App Redesign Is Not Enough, improving the app does not automatically improve the complete customer relationship.
What to evaluate: Ask the partner to map how its proposed solution would affect adjacent products, operational processes and customer journeys.
7. Experience Governance: Can They Protect Quality Beyond Launch?
Even an exceptional redesign can lose coherence over time. New products are introduced. Business priorities change. Additional vendors join the ecosystem. Different departments reinterpret design principles. New technologies create new interaction patterns. Each decision may appear reasonable independently. Together, they can gradually undermine the original experience strategy.
This is why UX governance must be considered during partner selection. A design system can standardize components, but it cannot independently resolve strategic conflicts between business units or determine which customer outcomes deserve priority. The institution needs shared experience principles, decision criteria, defined responsibilities and mechanisms for maintaining coherence.
UXDA addresses this through its Digital Experience Governance System (DXG), which connects experience direction with the standards and decision-making needed to support long-term consistency.
Read more about Systemic UX Governance in Banking >>
What to evaluate: Ask what happens after design delivery. How will future changes be evaluated? Who resolves conflicts? How will teams maintain consistency as the ecosystem expands?
8. Cross-Functional Alignment: Can They Work Beyond the UX Department?
The quality of digital banking experience depends on decisions made by many functions. Product management defines priorities. Technology establishes implementation constraints. Risk and compliance influence verification and customer communication. Marketing communicates the proposition. Operations determines how services are delivered.
Internal UX teams translate strategy into detailed experiences. A strategic external partner must be able to work constructively across these groups. This requires communication skills, institutional understanding and the ability to challenge assumptions without creating unnecessary conflict. It also requires respect for the bank's internal expertise.
The purpose of a strategic partnership is not to replace capable internal professionals. It is to connect their knowledge and capabilities around a coherent customer experience direction.
What to evaluate: Ask how the partner manages disagreements between stakeholders and what decision-making structures it recommends for complex transformation programs.
9. Implementation Realism: Can They Connect Ambition With Delivery?
A concept is valuable only if the institution can implement and sustain it. Strategic ambition must therefore be informed by technology, security, accessibility, operational readiness, regulatory obligations and delivery dependencies.
However, feasibility should not automatically determine the experience direction. If every decision is constrained by today's systems, the transformation risks becoming a cosmetic modernization of existing limitations.
A strong UX partner in banking should distinguish between constraints that must be respected, assumptions that can be challenged and capabilities that require a longer-term roadmap. This is especially important when banks work with multiple technology vendors.
Financial UX strategy must remain connected to implementation without becoming subordinate to whichever platform or supplier was selected first.
What to evaluate: Request evidence of how the partner translates ambitious experience concepts into practical architecture, design specifications, stakeholder alignment and delivery-ready decisions.
10. Business Impact: Can They Demonstrate Value Beyond Awards?
Design awards can recognize outstanding creativity and execution. They are useful signals of quality. But they are not substitutes for evidence of customer and business value.
When reviewing a case study, banks should ask what the original challenge was, which assumptions were tested, which decisions changed and how the resulting experience supported the institution's objectives. Relevant measures may include journey completion, digital adoption, customer comprehension, product engagement, operational efficiency, service demand, retention and experience consistency.
Not every outcome can be attributed directly to a UX engagement. Business performance also depends on implementation, marketing, operations, product pricing, market conditions and other factors. A credible partner should explain those limitations rather than promise unsupported ROI.
What to evaluate: Look for transparent reasoning, verifiable project evidence, relevant client references and measurable outcomes where reliable data is available.
Strategic UX Partner vs Traditional UX Design Agency: What's the Difference?
The difference between a UX agency and a strategic partner is not necessarily the company's name, size or organizational model.
Some agencies offer significant strategic expertise. Some consulting organizations primarily deliver execution.
The important distinction is the depth of responsibility and influence within the engagement.
| Evaluation | Execution-focused UX engagement | Strategic UX partnership |
|---|---|---|
| Starting point | Defined brief and deliverables | Validated customer and business problem |
| Main objective | Improve or create interfaces | Define and protect experience value |
| Core question | How should we design it? | What should we build, why and how should it evolve? |
| Research | Validates designs and usability | Informs strategic direction and priorities |
| Differentiation | Logo and colors | Distinctive Digital Brand Identity |
| Scope | Features, screens and selected journeys | Products, journeys and experience ecosystems |
| Collaboration | Product and delivery teams | Business leadership and cross-functional teams |
| Governance | Design specifications and components | Experience principles, standards and decision mechanisms |
| Success | Delivery and local UX performance | Customer outcomes and long-term transformation value |
These models are not mutually exclusive. A successful transformation needs both strategic direction and excellent execution. The problem emerges when a bank assumes that strong execution capabilities automatically include strategic judgment.
A partner that can deliver the requested solution is valuable. A partner that can determine whether the requested solution is right may be indispensable.
Seven Red Flags When Choosing a Banking UX Agency or Strategic Partner
Understanding the desired capabilities is only half of the selection process. Banks should also recognize warning signs that indicate a proposed engagement may fail to address strategic challenges.
Red Flag 1: The Partner Accepts Every Requirement Without Challenge
A supplier may appear highly cooperative by agreeing to every feature request, timeline and design preference. But if it never questions the underlying assumptions, the bank receives little independent strategic value.
The most useful partner is not necessarily the one that agrees most frequently. It is the one that can constructively explain when a proposed decision may undermine the customer experience or business objective.
Red Flag 2: The Portfolio Is More Convincing Than the Reasoning Behind It
Impressive screens attract attention. But if the partner cannot explain why an experience was structured in a particular way, which customer needs influenced it or what alternatives were rejected, the portfolio offers limited evidence of strategic competence.
Banks should evaluate decisions, not just deliverables.
Red Flag 3: The Proposed Solution Resembles Every Leading Competitor
Competitive benchmarking is essential. Blind replication is not.
If the partner's principal recommendation is to reproduce features and conventions from market leaders, it may help the bank achieve functional parity while sacrificing differentiation.
The institution should ask what customers will recognize as meaningfully different—and valuable—about its experience.
Red Flag 4: Research Begins After the Direction Has Already Been Approved
When research is used only to validate an existing solution, it cannot fully protect the bank from investing in the wrong direction.
A strategic partner should be comfortable discovering that the original brief needs to change.
Red Flag 5: The Partner Has No Influence Beyond Interface Design
Some of the most damaging UX problems originate in product policy, operational processes, technology constraints or organizational conflicts.
If the external team has no access to the relevant decision-makers, it may be unable to resolve the causes of customer friction. The scope of influence should match the scale of the expected outcome.
Red Flag 6: The Engagement Ends Without a Plan for Long-Term Coherence
A successful launch is important, but it does not guarantee a sustainable experience. Without shared principles, ownership, documentation, knowledge transfer and governance, the institution may gradually return to fragmented decision-making.
A strong partner should help the bank become more capable of maintaining its own experience.
Red Flag 7: The Partner Promises Results Without a Credible Basis
Guaranteed conversion increases, dramatic ROI projections and promises of exceptional adoption should be treated carefully when they lack reliable evidence.
A strategic partner should define how value will be measured, explain the assumptions behind projections and distinguish its contribution from broader market and organizational factors.
Credibility comes from evidence and disciplined judgment—not exaggerated certainty.
The Hidden Cost of Choosing the Wrong UX Partner: Experience Debt
The consequences of an unsuitable UX partnership are not always immediately visible. Sometimes the project is delivered on time. The interface looks modern. Stakeholders approve the presentation. The development team receives the specifications. The product launches successfully.
Yet the transformation gradually becomes more difficult to evolve.
A new channel introduces different interaction patterns. Another product adopts inconsistent terminology. An external technology provider changes the journey architecture. New business requirements lead to exceptions that weaken the original experience principles.
Over time, these decisions accumulate.
At UXDA, we describe this as Experience Debt: the growing burden of fragmented experience decisions that creates complexity, inconsistency and additional effort for both customers and the institution.
Experience Debt is not limited to visual design. It can appear in disconnected customer journeys, duplicated processes, contradictory communication, inconsistent product behavior and unclear ownership of the experience.
A weak strategic direction may therefore create costs long after the initial engagement is completed. These costs can include repeated redesigns, additional research, implementation rework, higher service demand, slower decision-making and lost opportunities for differentiation.
Not every one of these outcomes will appear in the original project budget. That is what makes them dangerous. The cost of choosing a UX partner should not be evaluated solely through hourly rates or delivery fees.
The real cost includes the future complexity, constraints and decisions the partnership leaves behind.
A strategically sound engagement should reduce that burden by establishing a clear experience architecture and a coherent foundation for future development.
What Real Banking Transformations Reveal About Strategic UX Expertise
Strategic capabilities are easier to evaluate through real transformation challenges than through abstract promises. The strongest case studies should demonstrate how a partner understands the problem, establishes priorities, makes difficult decisions and enables the institution to continue developing the experience.
NMB Bank: Defining a Super App Beyond Feature Expansion
NMB Bank in Tanzania faced an ambitious challenge: evolve its Mkononi banking service toward a broader digital super app ecosystem without sacrificing the familiarity and trust that customers associated with existing financial services.
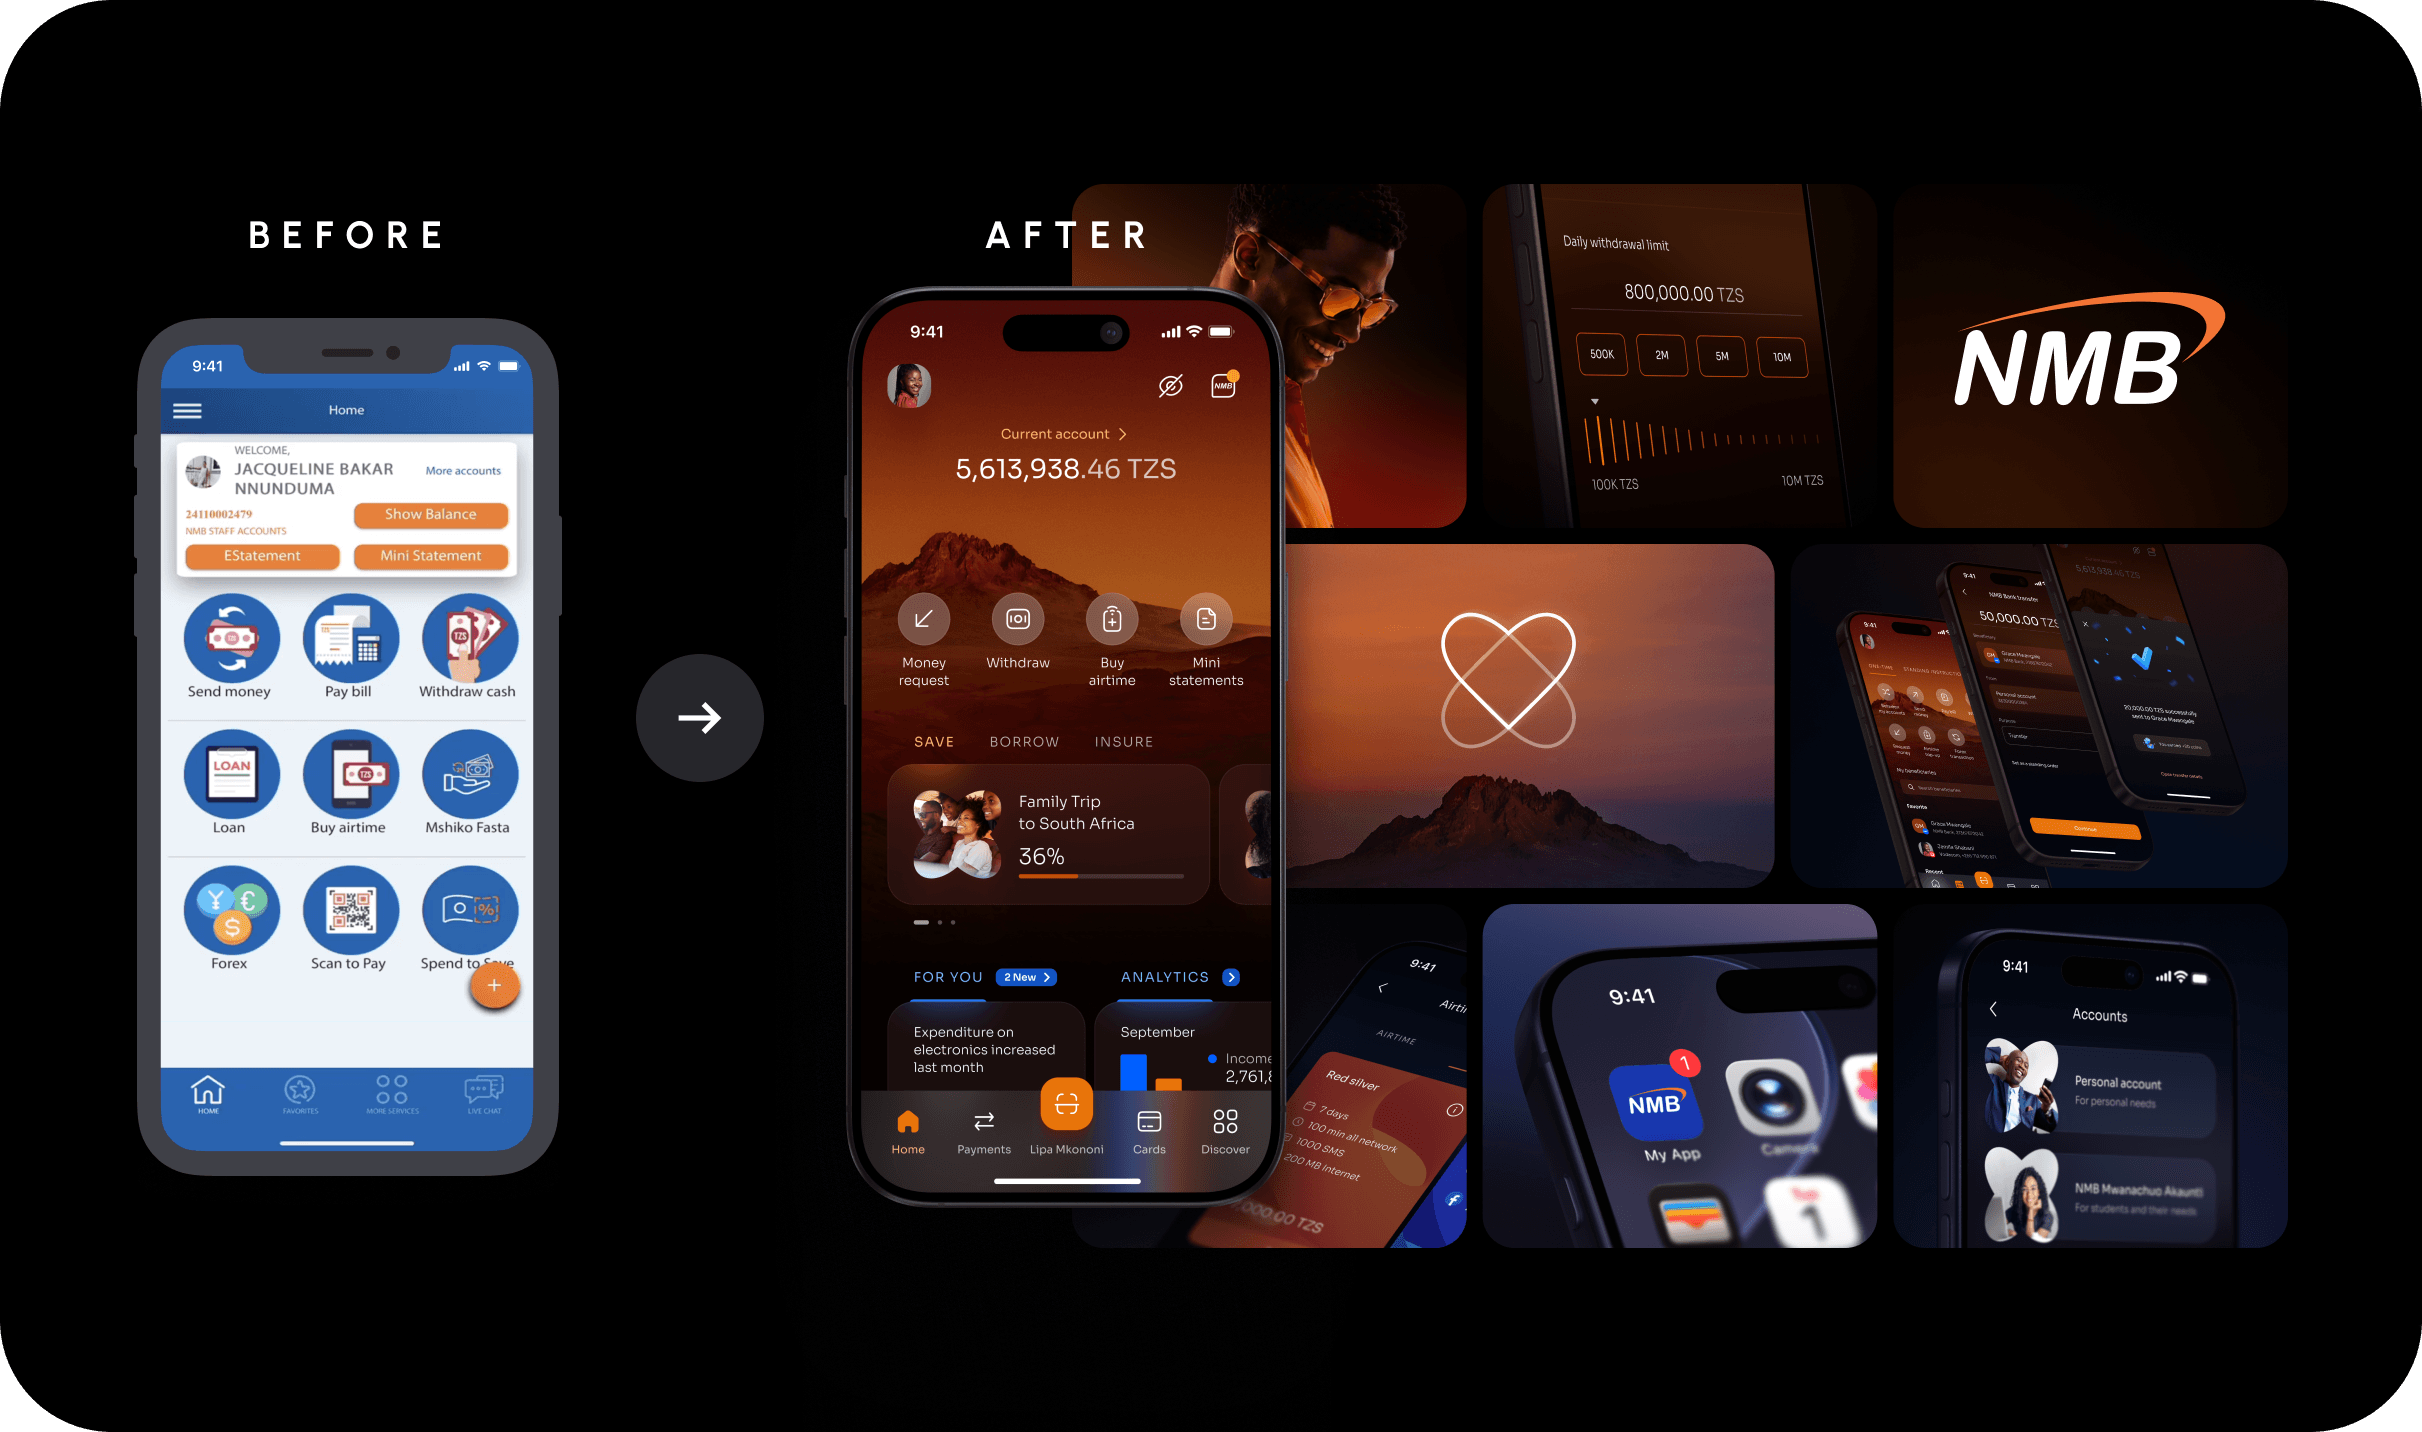
The task was not simply to redesign a mobile application.
The bank needed a scalable foundation for expanding digital services while supporting customers with different financial behaviors and levels of digital confidence.
In the NMB Mkononi Super App case study, UXDA describes five strategic gaps that informed the transformation: Adoption, Trust, Advantage, Brand and Alignment.
These considerations guided decisions about the product's experience structure, Digital Brand Identity, information architecture and organizational readiness.
Instead of expanding the interface around an ever-growing list of services, the experience was structured to make everyday banking dependable and understandable while creating room for future growth.
Liv X: Turning a Distinctive Brand Promise Into Banking Behavior
A digital banking brand targeting a new generation of customers cannot rely on traditional banking functionality presented in a more colorful interface. It needs an experience that expresses its positioning through the way customers interact with their money.
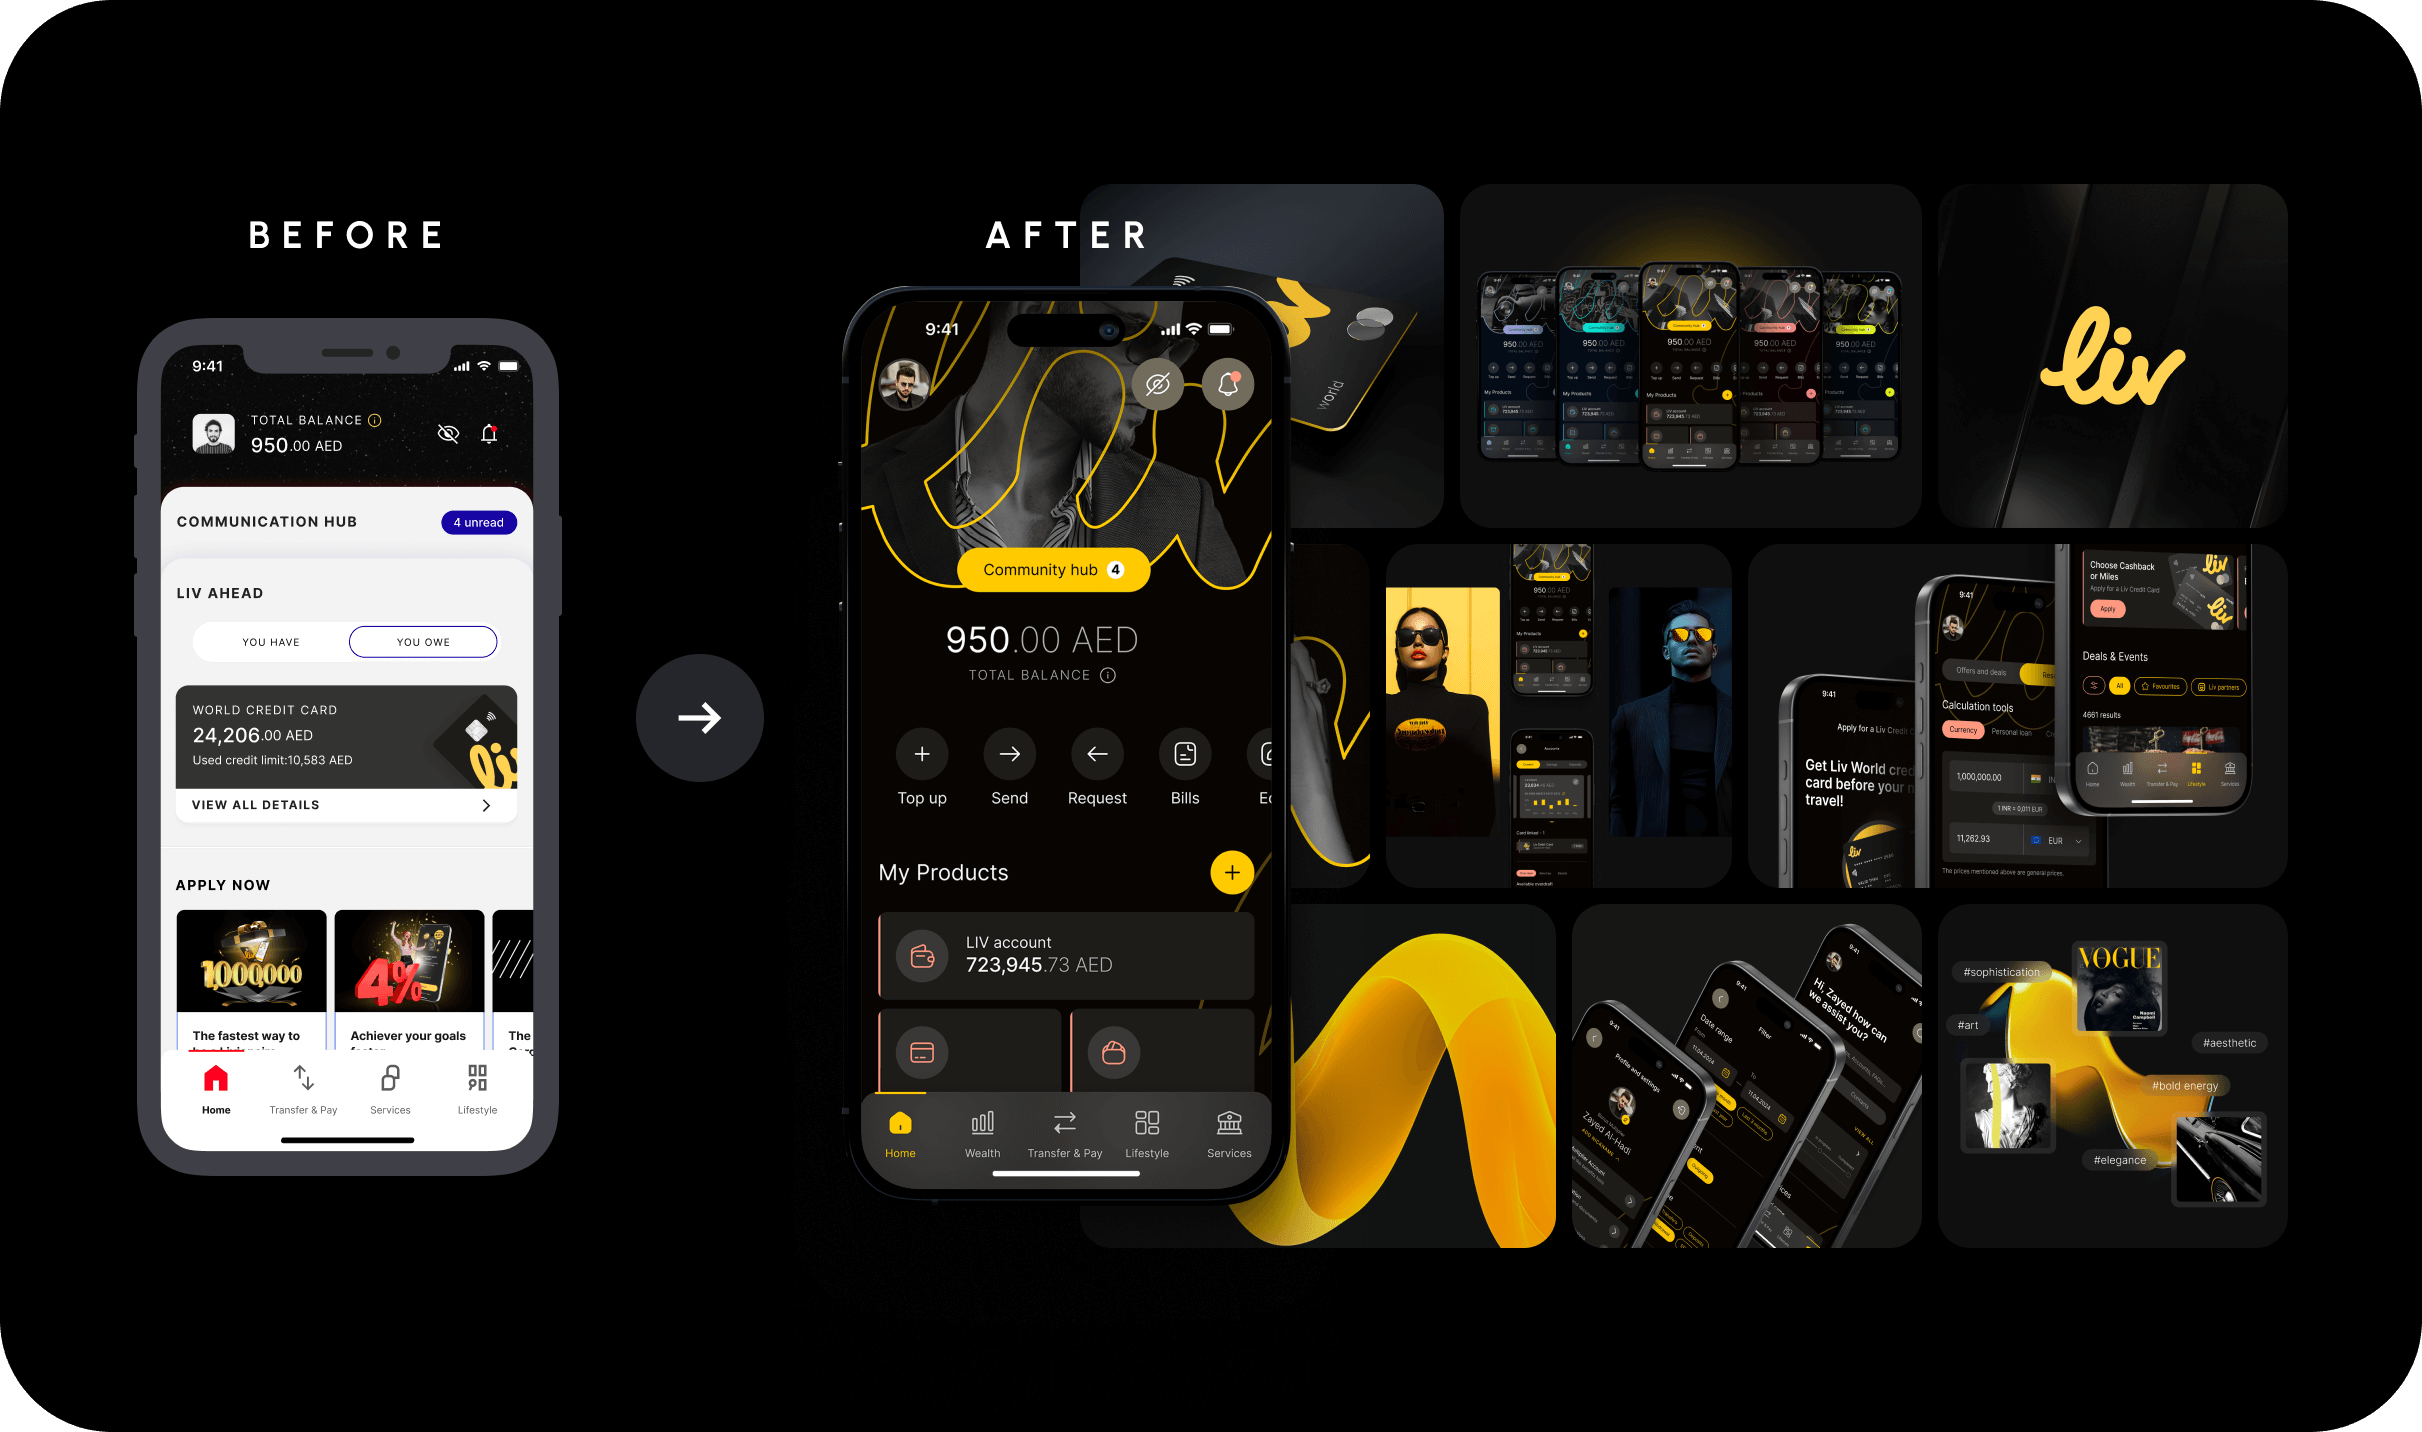
UXDA's work on Liv X, part of the Emirates NBD ecosystem, demonstrates how a distinctive lifestyle-oriented Digital Brand Identity can inform the banking experience itself.
The strategic challenge extends beyond visual differentiation. It involves connecting the institution's brand personality with financial clarity, product discovery, interaction patterns and everyday banking needs.
The principle is relevant to any bank seeking to differentiate.
A strong digital brand does not emerge from decorating conventional banking experiences. It emerges from making deliberate decisions about how the institution should behave.
BKT: Reconsidering the Relationship Between Banking and Customer Independence
BKT's digital banking transformation addressed the need to make everyday banking easier to understand and use independently.The challenge was not only to modernize the interface but to reduce customers' dependence on physical or assisted service for routine financial tasks.
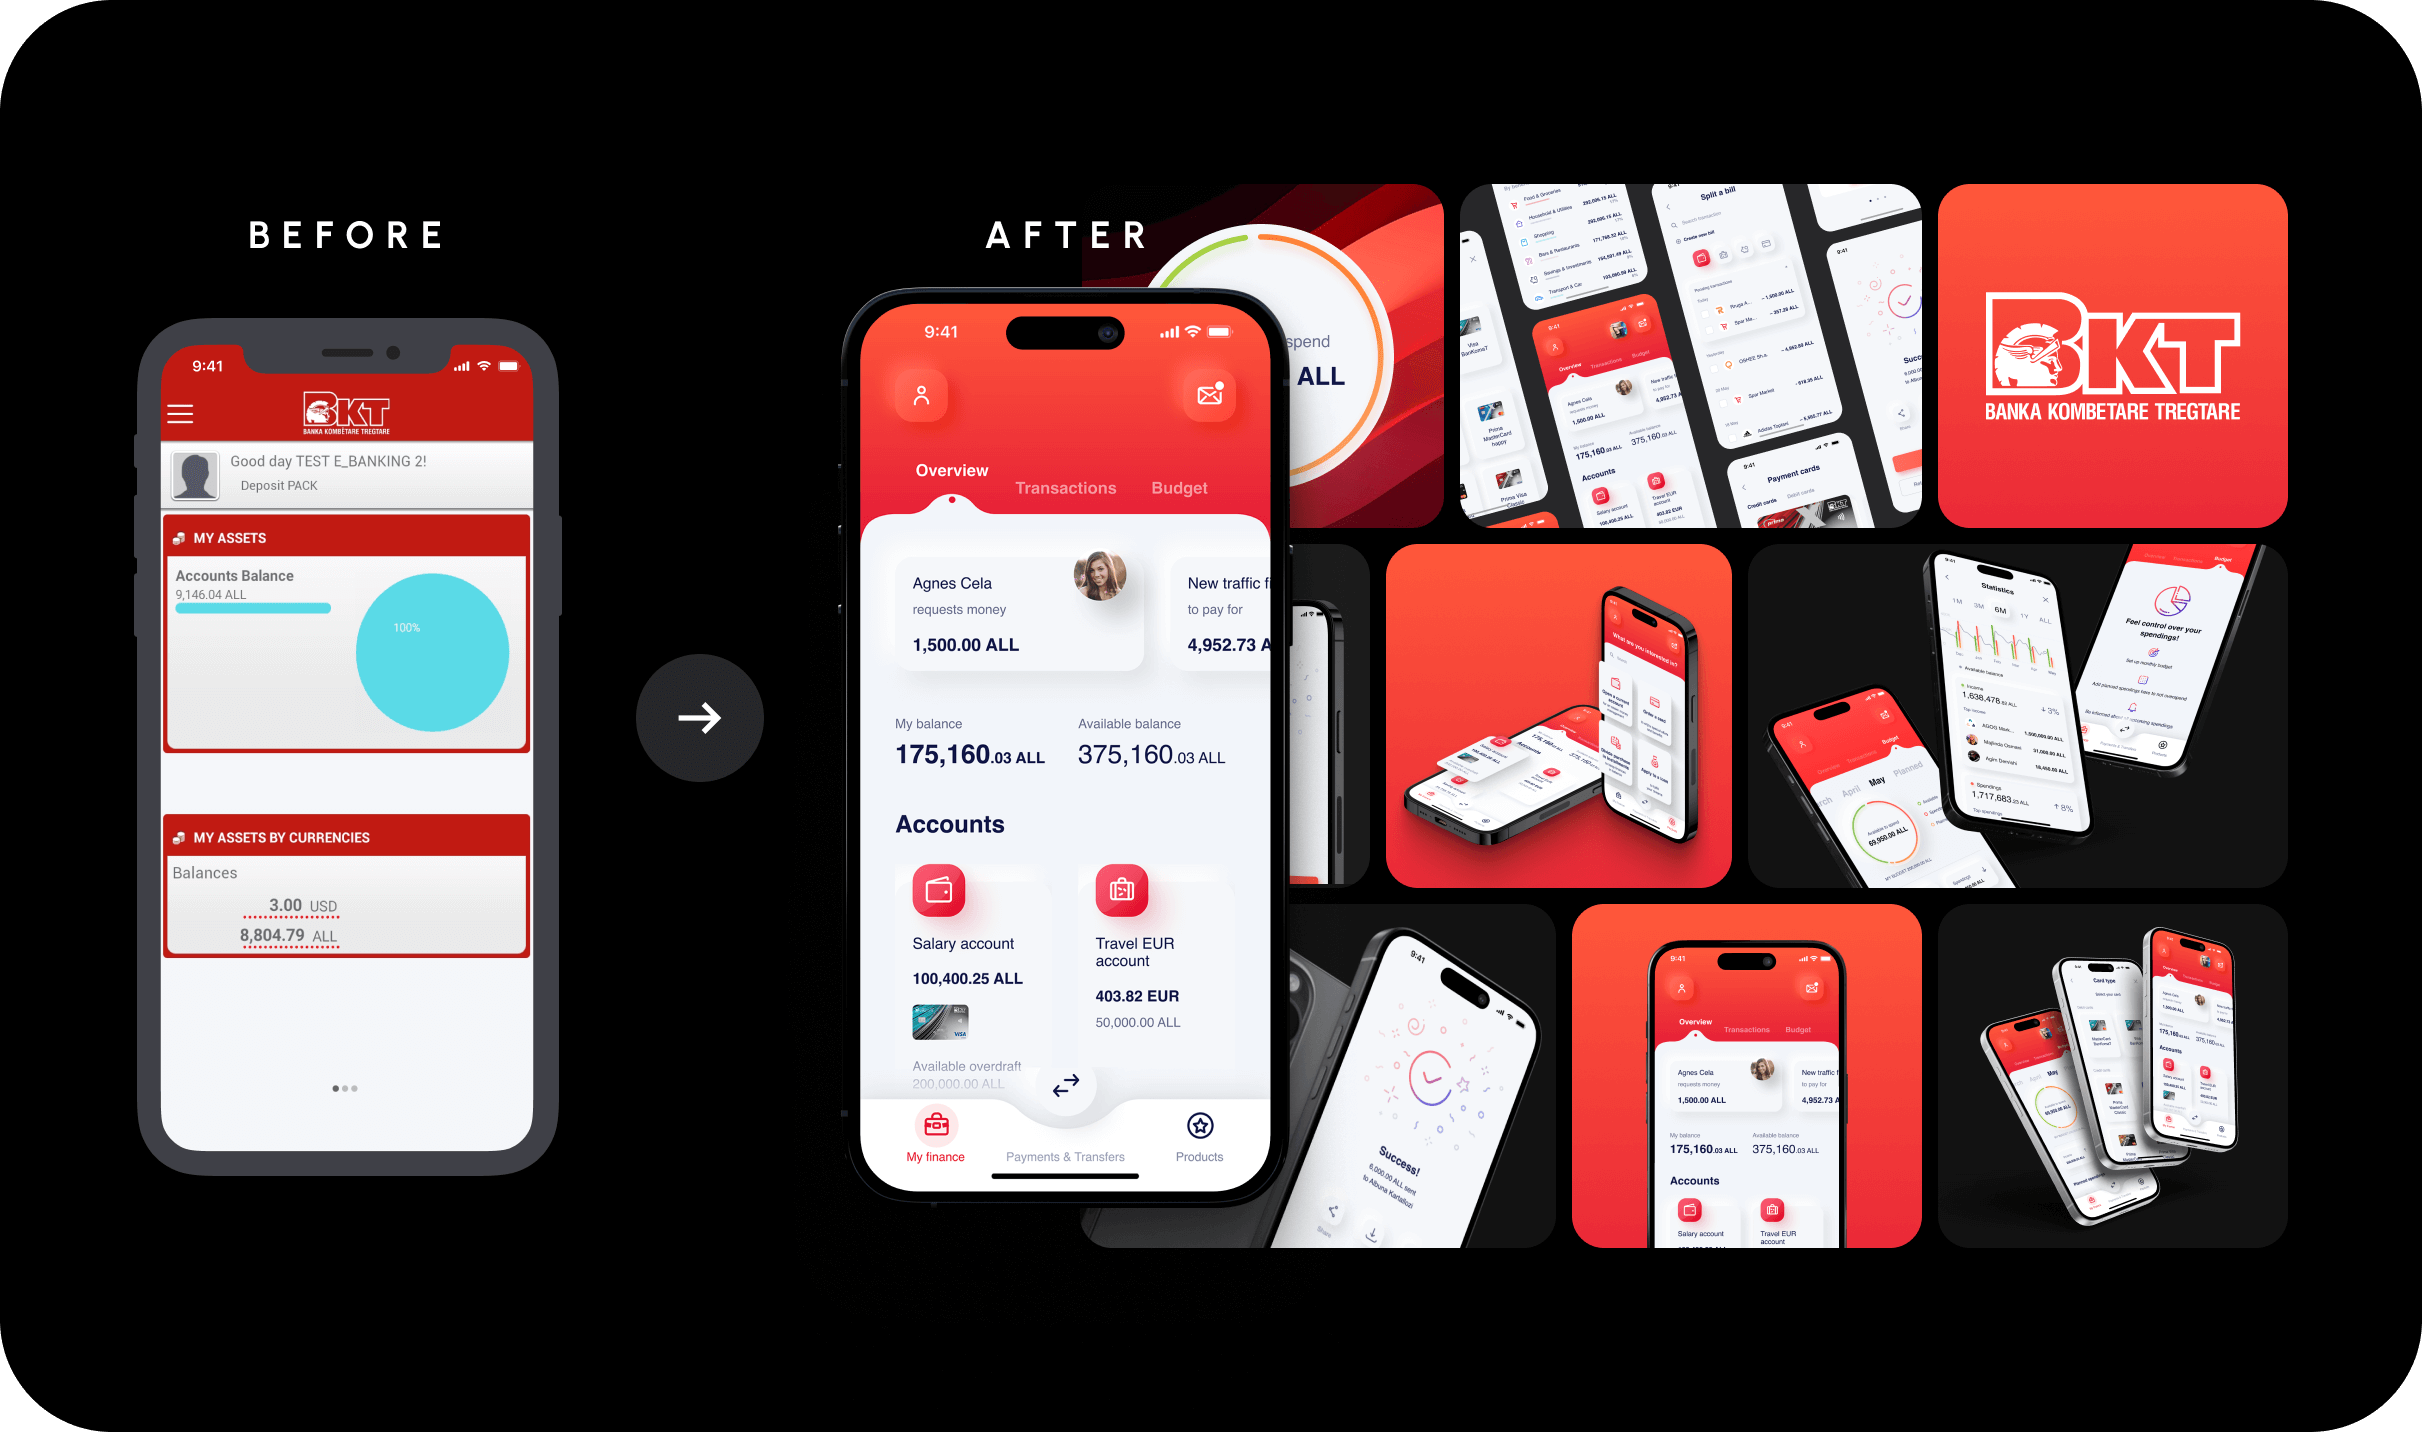
UXDA's BKT banking UX case study explores how clearer information architecture, navigation and financial communication supported a more intuitive digital banking experience. The broader lesson is that strategic UX should connect interface decisions to customer behavior and operational objectives.
A successful redesign should not simply make banking look more modern. It should change what customers can confidently accomplish.
Emirates NBD: Turning a Fragmented Banking Ecosystem Into a Strategic Digital Advantage
For one of the Middle East's leading financial institutions, an outstanding mobile banking app was not enough.
Emirates NBD faced a more fundamental challenge: how to transform a fragmented ecosystem of banking, investment and financial services into a coherent, personalized experience that could strengthen customer relationships, differentiate the brand and increase the value of its digital investments.
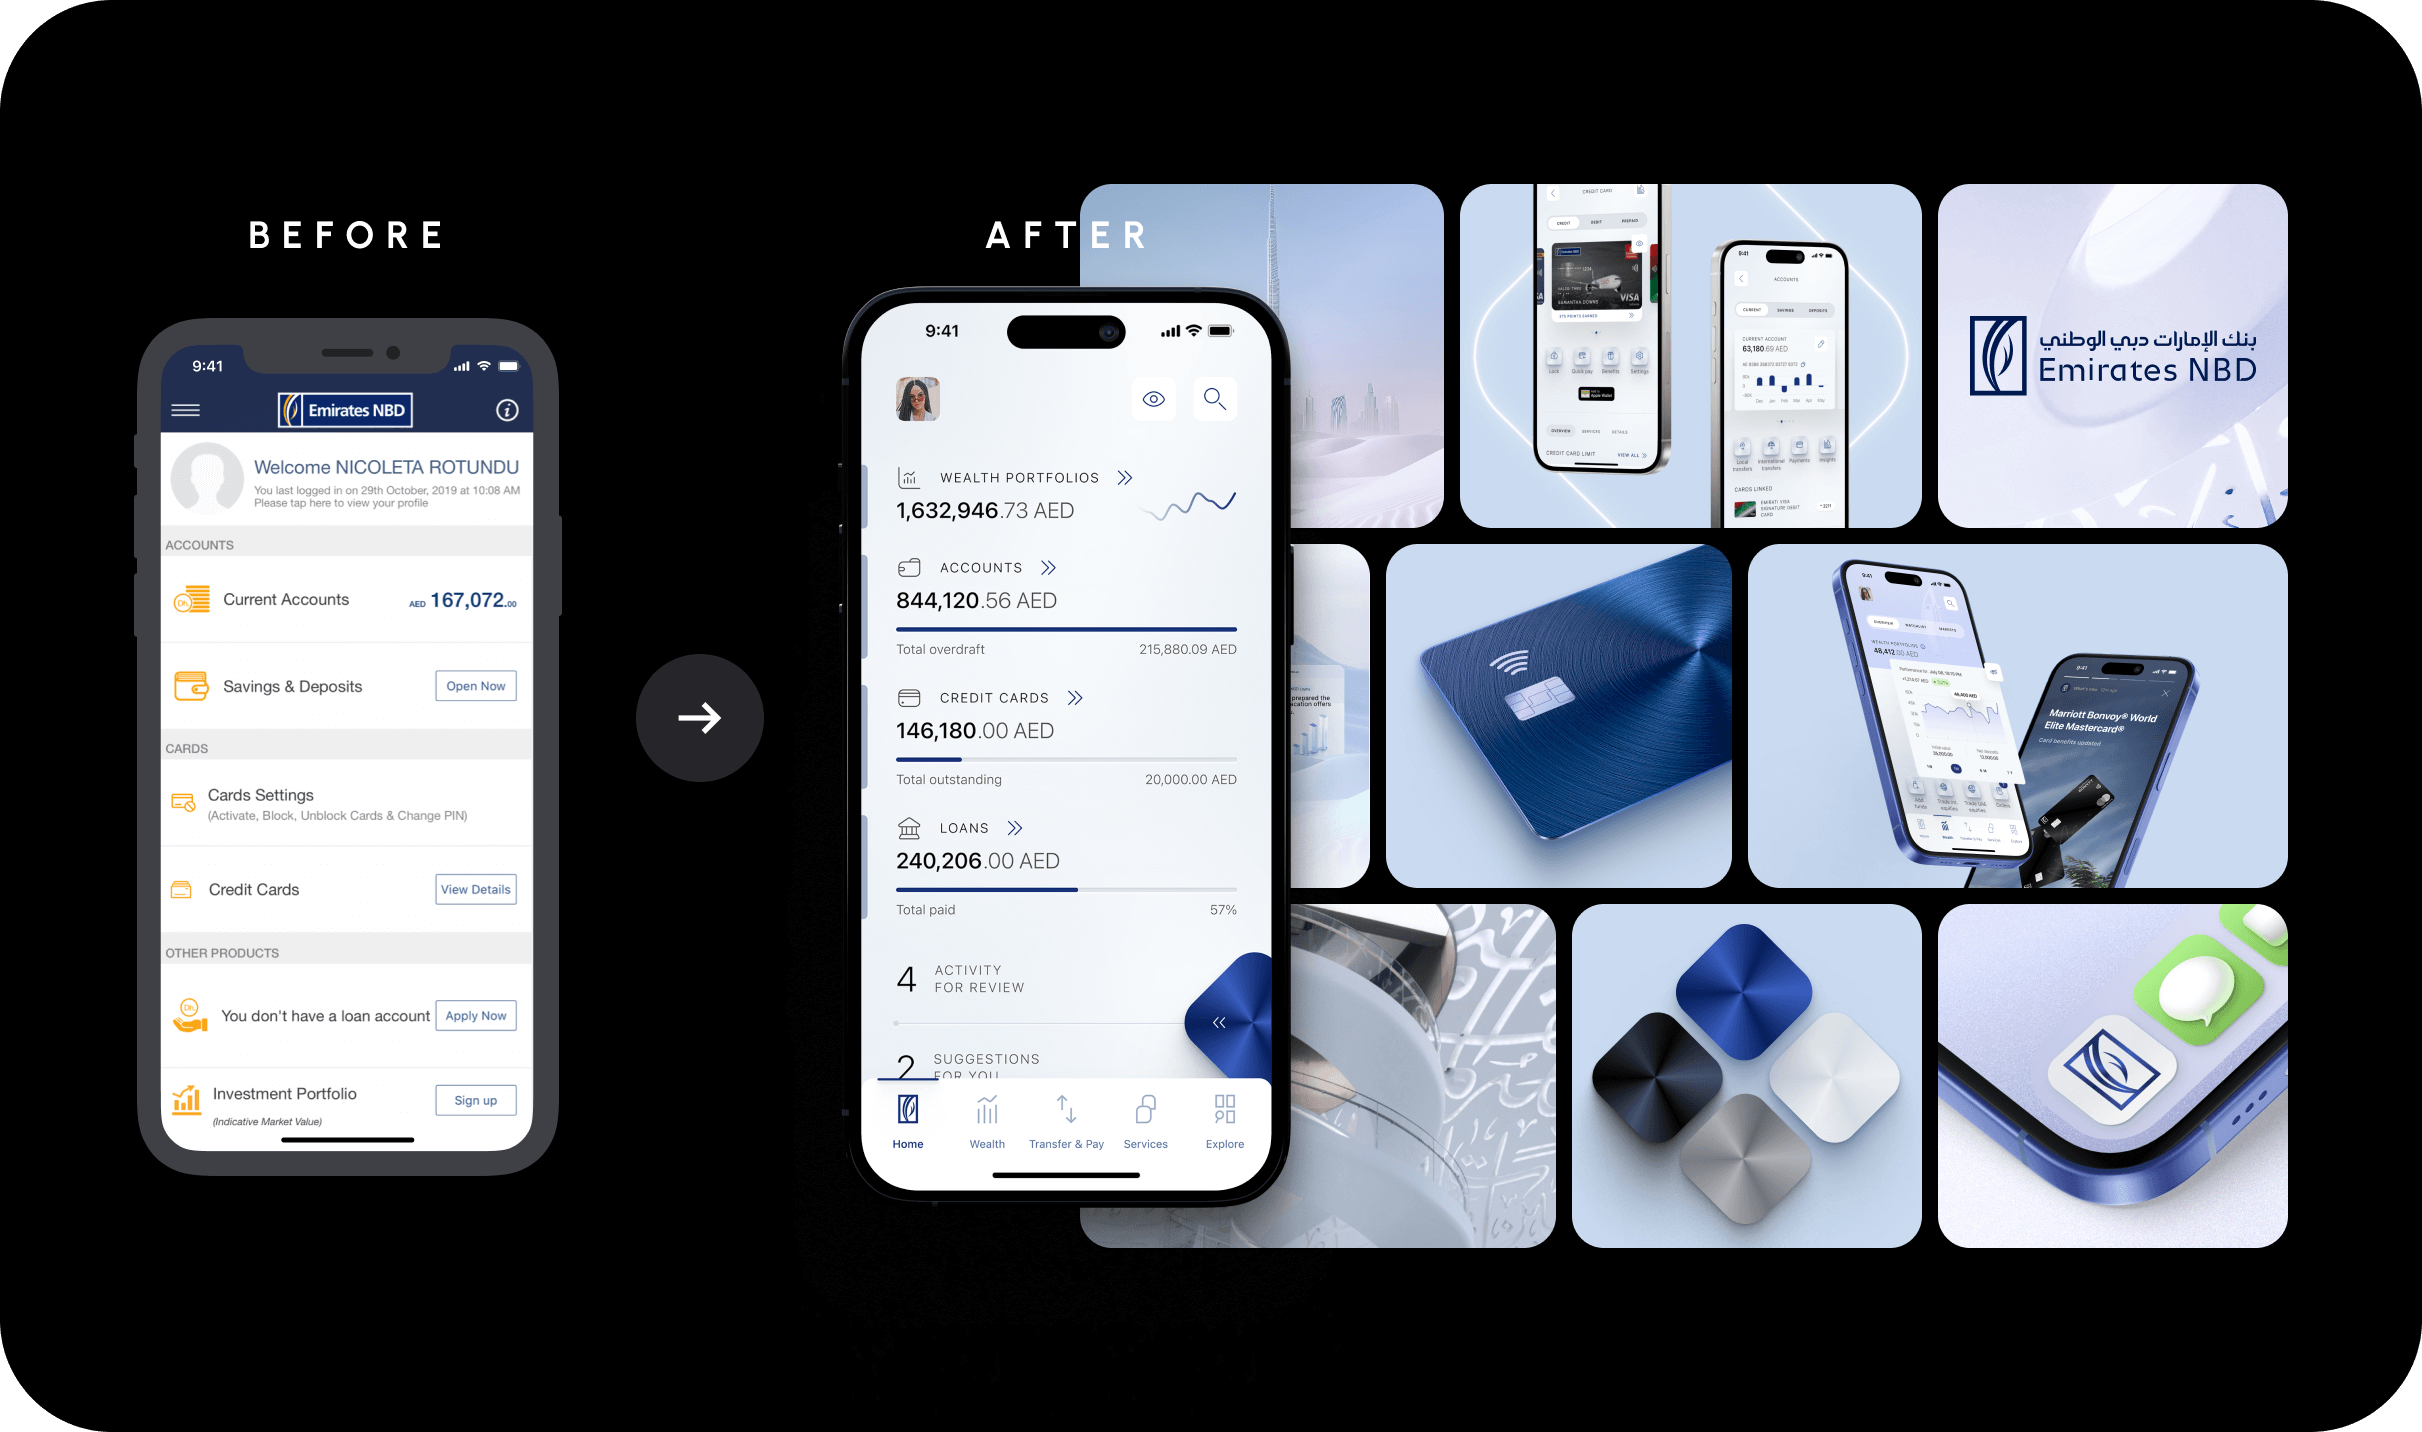
The ambition extended far beyond interface modernization. The bank needed a strategic experience direction capable of unifying complex financial services, aligning multiple teams and supporting its long-term digital transformation.
Working closely with Emirates NBD's leadership, product and technology teams, UXDA helped establish a unified experience strategy that translated the bank's premium brand identity and Dubai's distinctive spirit into the digital environment.
The resulting ENBD X experience brought everyday banking and wealth management closer together, providing customers with a more holistic view of their finances and access to over 200 digital banking services. UXDA also contributed to the evolution of the design language and experience consistency across the bank's wider ecosystem, including mobile banking, online banking and related Emirates NBD Group products.
The bank reported significant results following the launch of ENBD X:
- 91% digital adoption reported in UXDA's subsequent Digital Brand Identity case material.
- 50% higher login and transaction activity compared with the previous application.
- An App Store rating increase from 2.0 to 4.7, as reported in UXDA's Digital Brand Identity case.
- Recognition through multiple regional mobile banking awards.
Garanti BBVA Securities: Choosing Strategic Expertise Over Another White-Label Experience
Garanti BBVA Securities faced a different but equally important challenge. As the Turkish investment market expanded, its existing eTrader platform relied on a restrictive white-label solution that limited personalization, innovation and consistency between mobile and web experiences.
The platform primarily served experienced investors, while a growing population of newcomers needed greater clarity, financial education and confidence in making investment decisions.
The challenge was not simply to create a more attractive trading interface.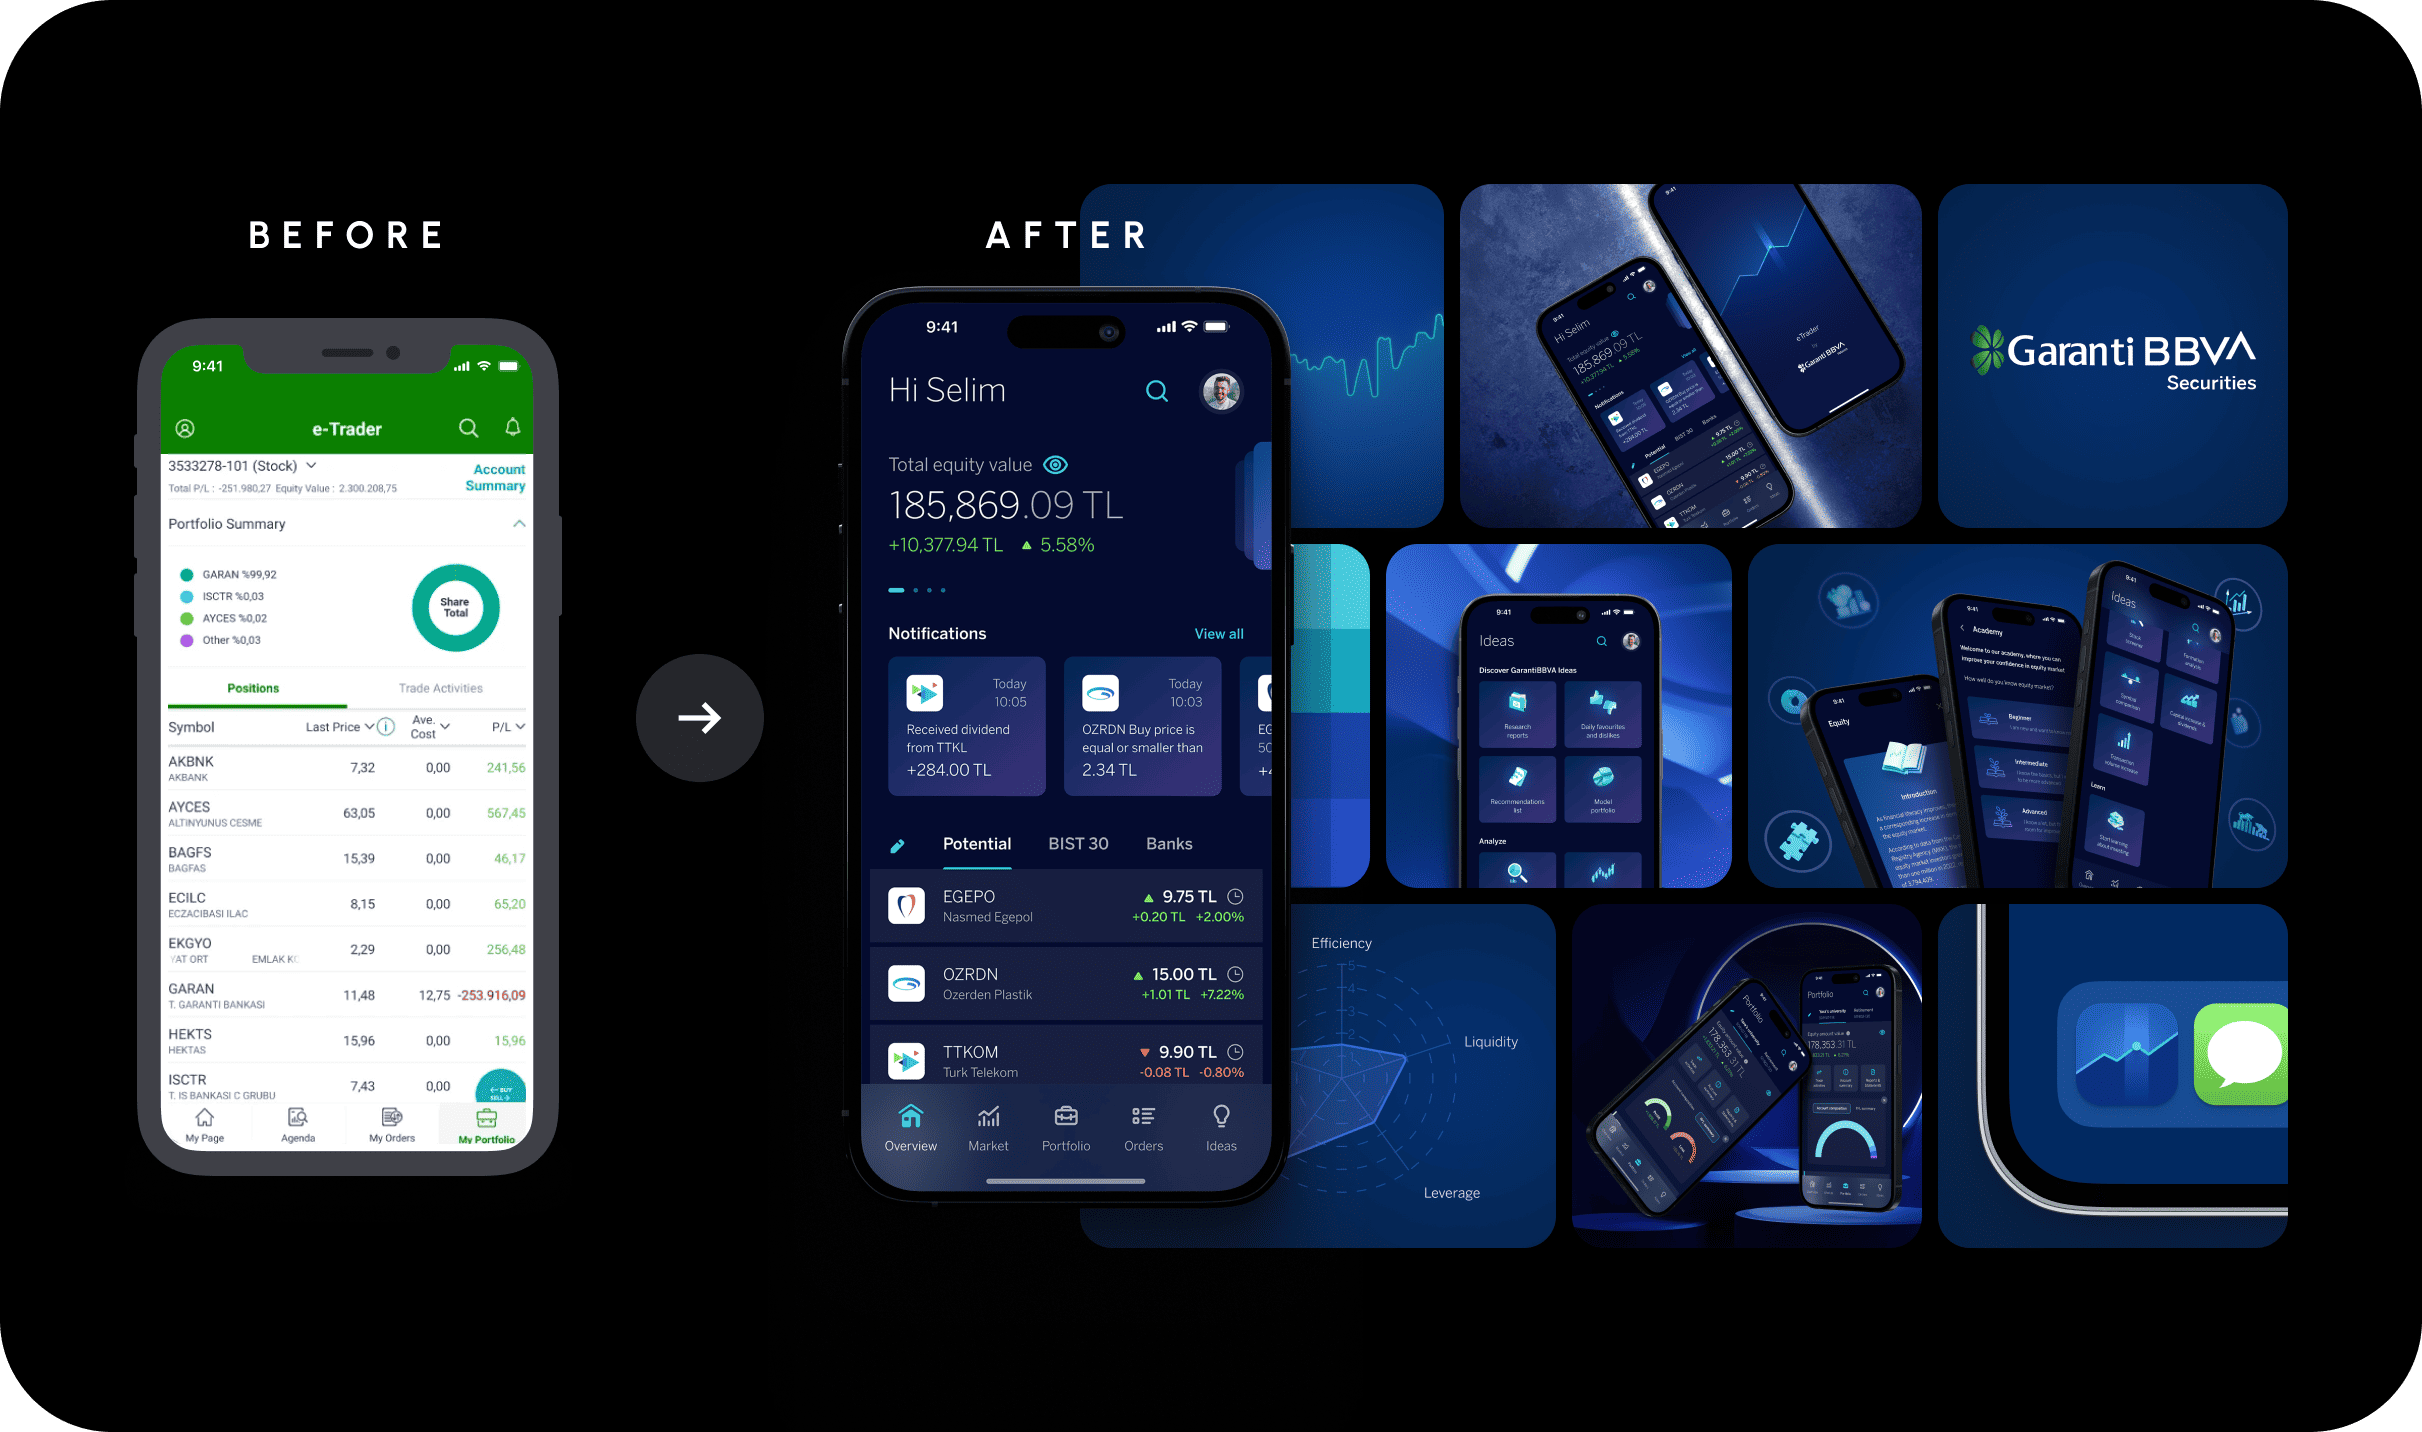
Garanti BBVA Securities needed to redefine its investment experience around different investor needs, strengthen its distinctive position in the market and gain greater control over the evolution of its digital products.
UXDA began with market analysis, stakeholder interviews and research involving investors with different levels of experience. These insights revealed a fundamental tension: experienced traders required advanced data, speed and analytical control, while newcomers needed understandable information, guidance and opportunities to develop financial knowledge.
Rather than forcing both groups into a generic trading interface, UXDA established an experience structure that could serve different needs within one coherent product.
The transformation introduced clearer portfolio overviews, personalized watchlists, improved symbol analysis, accessible trading actions and an educational Academy designed to help new investors build confidence.
Read the full Garanti BBVA Securities eTrader UX transformation case study.
When Should a Bank Hire an External Strategic UX Partner?
Many financial institutions have capable internal UX, product, technology and research teams. They understand the institution's systems, operational constraints, customers and long-term responsibilities.
A strategic external partner should not be engaged simply because outside expertise is assumed to be superior. The most valuable partnerships complement internal capabilities where specialized experience, independent judgment or cross-functional alignment is needed.
There are four particularly important moments when external strategic UX expertise can create value.
Before Transformation: Validate the Direction Before Investment
A bank preparing to invest in a new platform, mobile ecosystem or digital banking proposition should first understand the experience it wants to create. This requires research, strategic diagnosis, customer and market understanding, opportunity prioritization and a clear Experience North Star.
The objective is to reduce uncertainty before expensive technology and implementation commitments are made.
During Transformation: Align Teams Around One Experience
Large programs often involve multiple business units, technology suppliers, internal designers and delivery partners. Even when every team performs well, the result can become fragmented.
A strategic UX partner can help define shared experience architecture, establish Digital Brand Identity and resolve inconsistencies before they reach production.
During AI Implementation: Define the Experience Before Automating It
AI introduces new possibilities for customer assistance, proactive banking and autonomous financial interactions. But adding AI to a poorly understood journey can amplify existing friction.
Banks need to determine how AI should communicate, explain decisions, request permission, preserve customer control and operate consistently with the institution's broader experience strategy.
A strategic UX partner should help define this human-centered interaction model rather than treating AI as another isolated feature.
After Launch: Protect the Experience as the Bank Evolves
Digital transformation does not end when the application launches. New features, regulations, customer expectations and technologies continuously reshape the ecosystem.
Banks need consistent experience principles, knowledge transfer and governance mechanisms that enable internal teams to develop the product without losing strategic coherence.
The best external partnership should make the bank stronger—not more dependent.
Why Strategic Independence Matters in Banking UX Consulting
A financial institution's transformation is influenced by many legitimate interests. Business units want their products prioritized. Technology partners want solutions compatible with their platforms. Internal teams must manage delivery schedules, existing systems and organizational commitments. Executives need to demonstrate commercial progress.
These interests are not inherently in conflict with customer needs. But they can create pressure to favor decisions that are easiest to approve, implement or defend internally rather than those that produce the strongest long-term experience.
An independent strategic UX partner can contribute value by evaluating these decisions through customer evidence, financial expertise and the institution's broader experience objectives. That independence requires both competence and the willingness to disagree constructively.
A partner should be capable of explaining why a popular feature may not deserve priority, why a visually impressive design may weaken comprehension or why an apparently efficient implementation decision may create future fragmentation.
This does not mean an external partner should replace executive authority. Strategic decisions ultimately belong to the institution. The partner's role is to improve their quality.
A valuable partner does not defend every decision the bank has already made. It helps the bank make decisions worth defending.
Why UXDA Approaches Banking UX as an Institutional Capability
At UXDA, we have focused exclusively on financial services for more than a decade, contributing to over 150 financial digital products across 39 countries.
This specialization has reinforced a consistent conclusion: the most expensive digital experience problems are rarely limited to the interface. They emerge from the relationship between customer needs, business priorities, technology constraints, brand positioning and organizational decision-making. When those elements are disconnected, even excellent design execution may produce a fragmented or interchangeable experience.
UXDA's role is to help financial institutions establish a distinctive strategic direction and translate it into coherent experience architecture, interaction principles, digital products and governance. Our Digital Experience Governance System (DXG) connects research, strategic experience definition, Digital Brand Identity and consistency across products, teams and vendors.
The objective is to strengthen the institution's ability to make better experience decisions and preserve their value over time. This is why we work selectively with financial institutions where strategic experience can make a meaningful difference.
We don't chase volume. We build lasting impact.
The Right Banking UX Partner Should Protect the Value of Transformation
Choosing a banking UX partner is ultimately a decision about whose judgment will influence the institution's future digital experience.
The bank is not only purchasing research, architecture, design or consulting hours. It is selecting an external perspective that may shape how customers understand its services, how products work together, how the brand behaves and how future decisions are governed.
An execution-focused supplier can deliver a product according to specification. A strategic partner should also be capable of explaining when the specification is wrong. It should help the bank recognize which assumptions need validation, what makes the experience distinctive, how customer and business outcomes should be connected and how the transformation can remain coherent as it evolves.
Without strategic clarity, even advanced technology can accelerate fragmentation. Without distinctive Digital Brand Identity, a major transformation can make the institution resemble every competitor. Without experience governance, a successful launch can gradually accumulate inconsistencies that erode its long-term value.
The strongest banking UX partner is not necessarily the one offering the largest team, the most screenshots or the most impressive list of deliverables. It is the one capable of helping the institution make better decisions before they become expensive—and protecting those decisions as the bank evolves.
Because the real competitive advantage is not simply having one more digital banking product. It is creating a financial experience that is one of a kind.
Banking UX Partner Selection: Frequently Asked Questions
What is a strategic banking UX partner?
A strategic banking UX partner is an external specialist that helps financial institutions define, validate, design and govern digital customer experiences. Its role extends beyond interface design to customer research, product direction, Digital Brand Identity, cross-functional alignment and long-term experience governance.
How do banks choose the right UX design partner?
Banks should evaluate potential UX partners against financial industry expertise, strategic problem diagnosis, customer research, differentiation capabilities, systemic experience thinking, governance, implementation realism and evidence of business impact. Design portfolios and awards are useful, but they should not replace evaluation of the decisions and outcomes behind the work.
What is the difference between a banking UX agency and a strategic UX partner?
A banking UX agency may focus primarily on executing specified design work, while a strategic UX partner also contributes to defining problems, validating assumptions, establishing experience direction and maintaining coherence across products and channels. The distinction concerns the engagement's capabilities and responsibilities rather than the provider's formal business category.
Why is financial industry expertise important in UX design?
Financial UX requires understanding complex products, financial behavior, customer trust, regulatory constraints, security, risk communication and operational processes. Specialized knowledge helps designers create interfaces that are understandable and useful without compromising essential financial controls or customer protection.
What should banks look for in a banking UX portfolio?
Banks should examine the original business and customer challenge, the research performed, strategic decisions, rejected alternatives, design rationale, implementation constraints and documented outcomes. An attractive interface demonstrates craftsmanship but does not independently establish strategic expertise.
What are the biggest red flags when hiring a fintech UX design agency?
Warning signs include accepting requirements without challenge, relying primarily on visual portfolios, copying competitors, conducting research too late, lacking financial domain expertise, having no influence beyond design delivery, providing no governance plan and promising unsupported business results.
When should a bank engage an external strategic UX partner?
Banks should consider external strategic UX expertise before major transformation investments, during complex cross-product redesigns, when establishing distinctive Digital Brand Identity, when implementing AI-driven financial experiences or when improving governance across internal teams and external vendors.
Can an external UX partner work with a bank's in-house UX team?
Yes. A strategic partner can complement internal UX teams through independent research, financial domain expertise, experience strategy, cross-functional alignment and knowledge transfer. The goal should be to strengthen internal capabilities and maintain clear institutional ownership of the resulting experience.
Should banks outsource UX design or keep it in-house?
Banks should retain internal ownership of product strategy, customer relationships, critical decisions and ongoing experience management. External UX partners can provide specialized expertise, independent validation and additional strategic capacity where needed. The appropriate model depends on organizational maturity, transformation complexity and the capabilities already available internally.
What is the role of UX governance in digital banking transformation?
UX governance establishes shared experience principles, standards, decision responsibilities and review mechanisms across products, channels, teams and vendors. It helps financial institutions maintain consistency, prevent unnecessary fragmentation and protect the strategic value of digital experience as their ecosystems evolve.
How does a strategic UX partner help prevent Experience Debt?
A strategic UX partner can help prevent Experience Debt by defining coherent experience architecture, shared interaction principles, clear decision criteria and governance mechanisms before fragmented choices accumulate. It also helps teams identify when local product decisions may undermine the wider customer experience.
How should banks measure the ROI of a strategic UX partnership?
Banks should define relevant baseline indicators before the engagement and measure outcomes such as journey completion, digital adoption, customer comprehension, product engagement, operational efficiency, retention, experience coherence and implementation rework. Results should be assessed alongside other business and technology factors rather than attributed automatically to UX design.
What should banks include in a banking UX request for proposal?
A banking UX RFP should describe the institution's strategic objectives, customer challenges, product ecosystem, current research, technology dependencies, target outcomes, stakeholder responsibilities, governance expectations and evaluation criteria. It should also ask candidates to demonstrate their strategic reasoning, relevant financial experience and approach to knowledge transfer.
How does UXDA differ from a traditional financial UX design agency?
UXDA focuses exclusively on financial institutions and approaches UX as a strategic experience capability. Its work connects independent research, distinctive Digital Brand Identity, experience architecture and the DXG System for governance. Rather than focusing only on delivering interfaces, UXDA helps banks define and protect coherent digital experiences across complex financial ecosystems.
Get UXDA Research-Based White Paper "How to Win the Hearts of Digital Customers":
Planning a Major Digital Banking Transformation?
Before committing millions to technology and implementation, make sure your future customer experience is worth building.
UXDA partners with financial institutions to research, define and govern distinctive digital experiences—from strategic diagnosis and Experience North Star definition to Digital Brand Identity and systemic UX governance.
- E-mail us at info@theuxda.com
- Chat with us in Whatsapp
- Send a direct message to UXDA's CEO Alex Kreger on Linkedin