

AI in banking has moved from experimentation toward large-scale deployment. Artificial intelligence implementation in banking is transforming how financial institutions serve customers, prevent fraud, personalize financial services and improve operational efficiency. From generative AI assistants to predictive analytics and intelligent automation, leading banks are implementing AI across customer experience, financial advisory, payments, lending and risk management. The shift was dramatic: global AI adoption rocketed to 78% of all organizations—up from just 20% in 2017—while an extraordinary 91% of bank boards formally approved Gen-AI programs, according to NTT and McKinsey. But which AI banking use cases are delivering real value, and what can financial institutions learn from them?
In this article, UXDA examines 21 real-world AI banking case studies (+3 bonus) from JPMorgan Chase, Bank of America, Morgan Stanley, HSBC, DBS, Revolut, Nubank and other financial institutions with nearly 200 AI use-case examples in total. We explore how these organizations have implemented AI, what results they have reported, and how their experience can inform more effective banking AI strategies.
We analyze how financial AI adoption in recent years impacted key areas of digital CX, highlighting global trends as well as specific insights from major markets like the US and UK. We examine both quantitative gains— such as higher customer satisfaction scores, rising self-service usage and digital adoption rates—and qualitative developments, including more personalized services, smarter virtual assistants and greater accessibility in digital banking.
The central lesson is that successful AI transformation in banking is not measured by the number of AI features deployed, but by the customer and business problems those features solve. AI can increase productivity, reduce fraud and simplify digital interactions. However, lasting competitive advantage depends on integrating these capabilities into a coherent, trustworthy and human-centered financial experience.
In banking, AI is becoming a core capability for transforming how customers interact with financial institutions across mobile, web, conversational and assisted channels. The strongest applications go beyond automating existing processes: they personalize experiences, anticipate customer needs, simplify complex tasks and increasingly help customers make financial decisions.
AI is enabling higher engagement on digital platforms and scaling up customer support without sacrificing quality. J.D. Power survey shows consumers are largely optimistic about AI’s benefits: 72% agree AI will deliver easy, convenient self-service but also highlight areas to improve, such as building trust and ensuring human-like empathy in AI interactions.
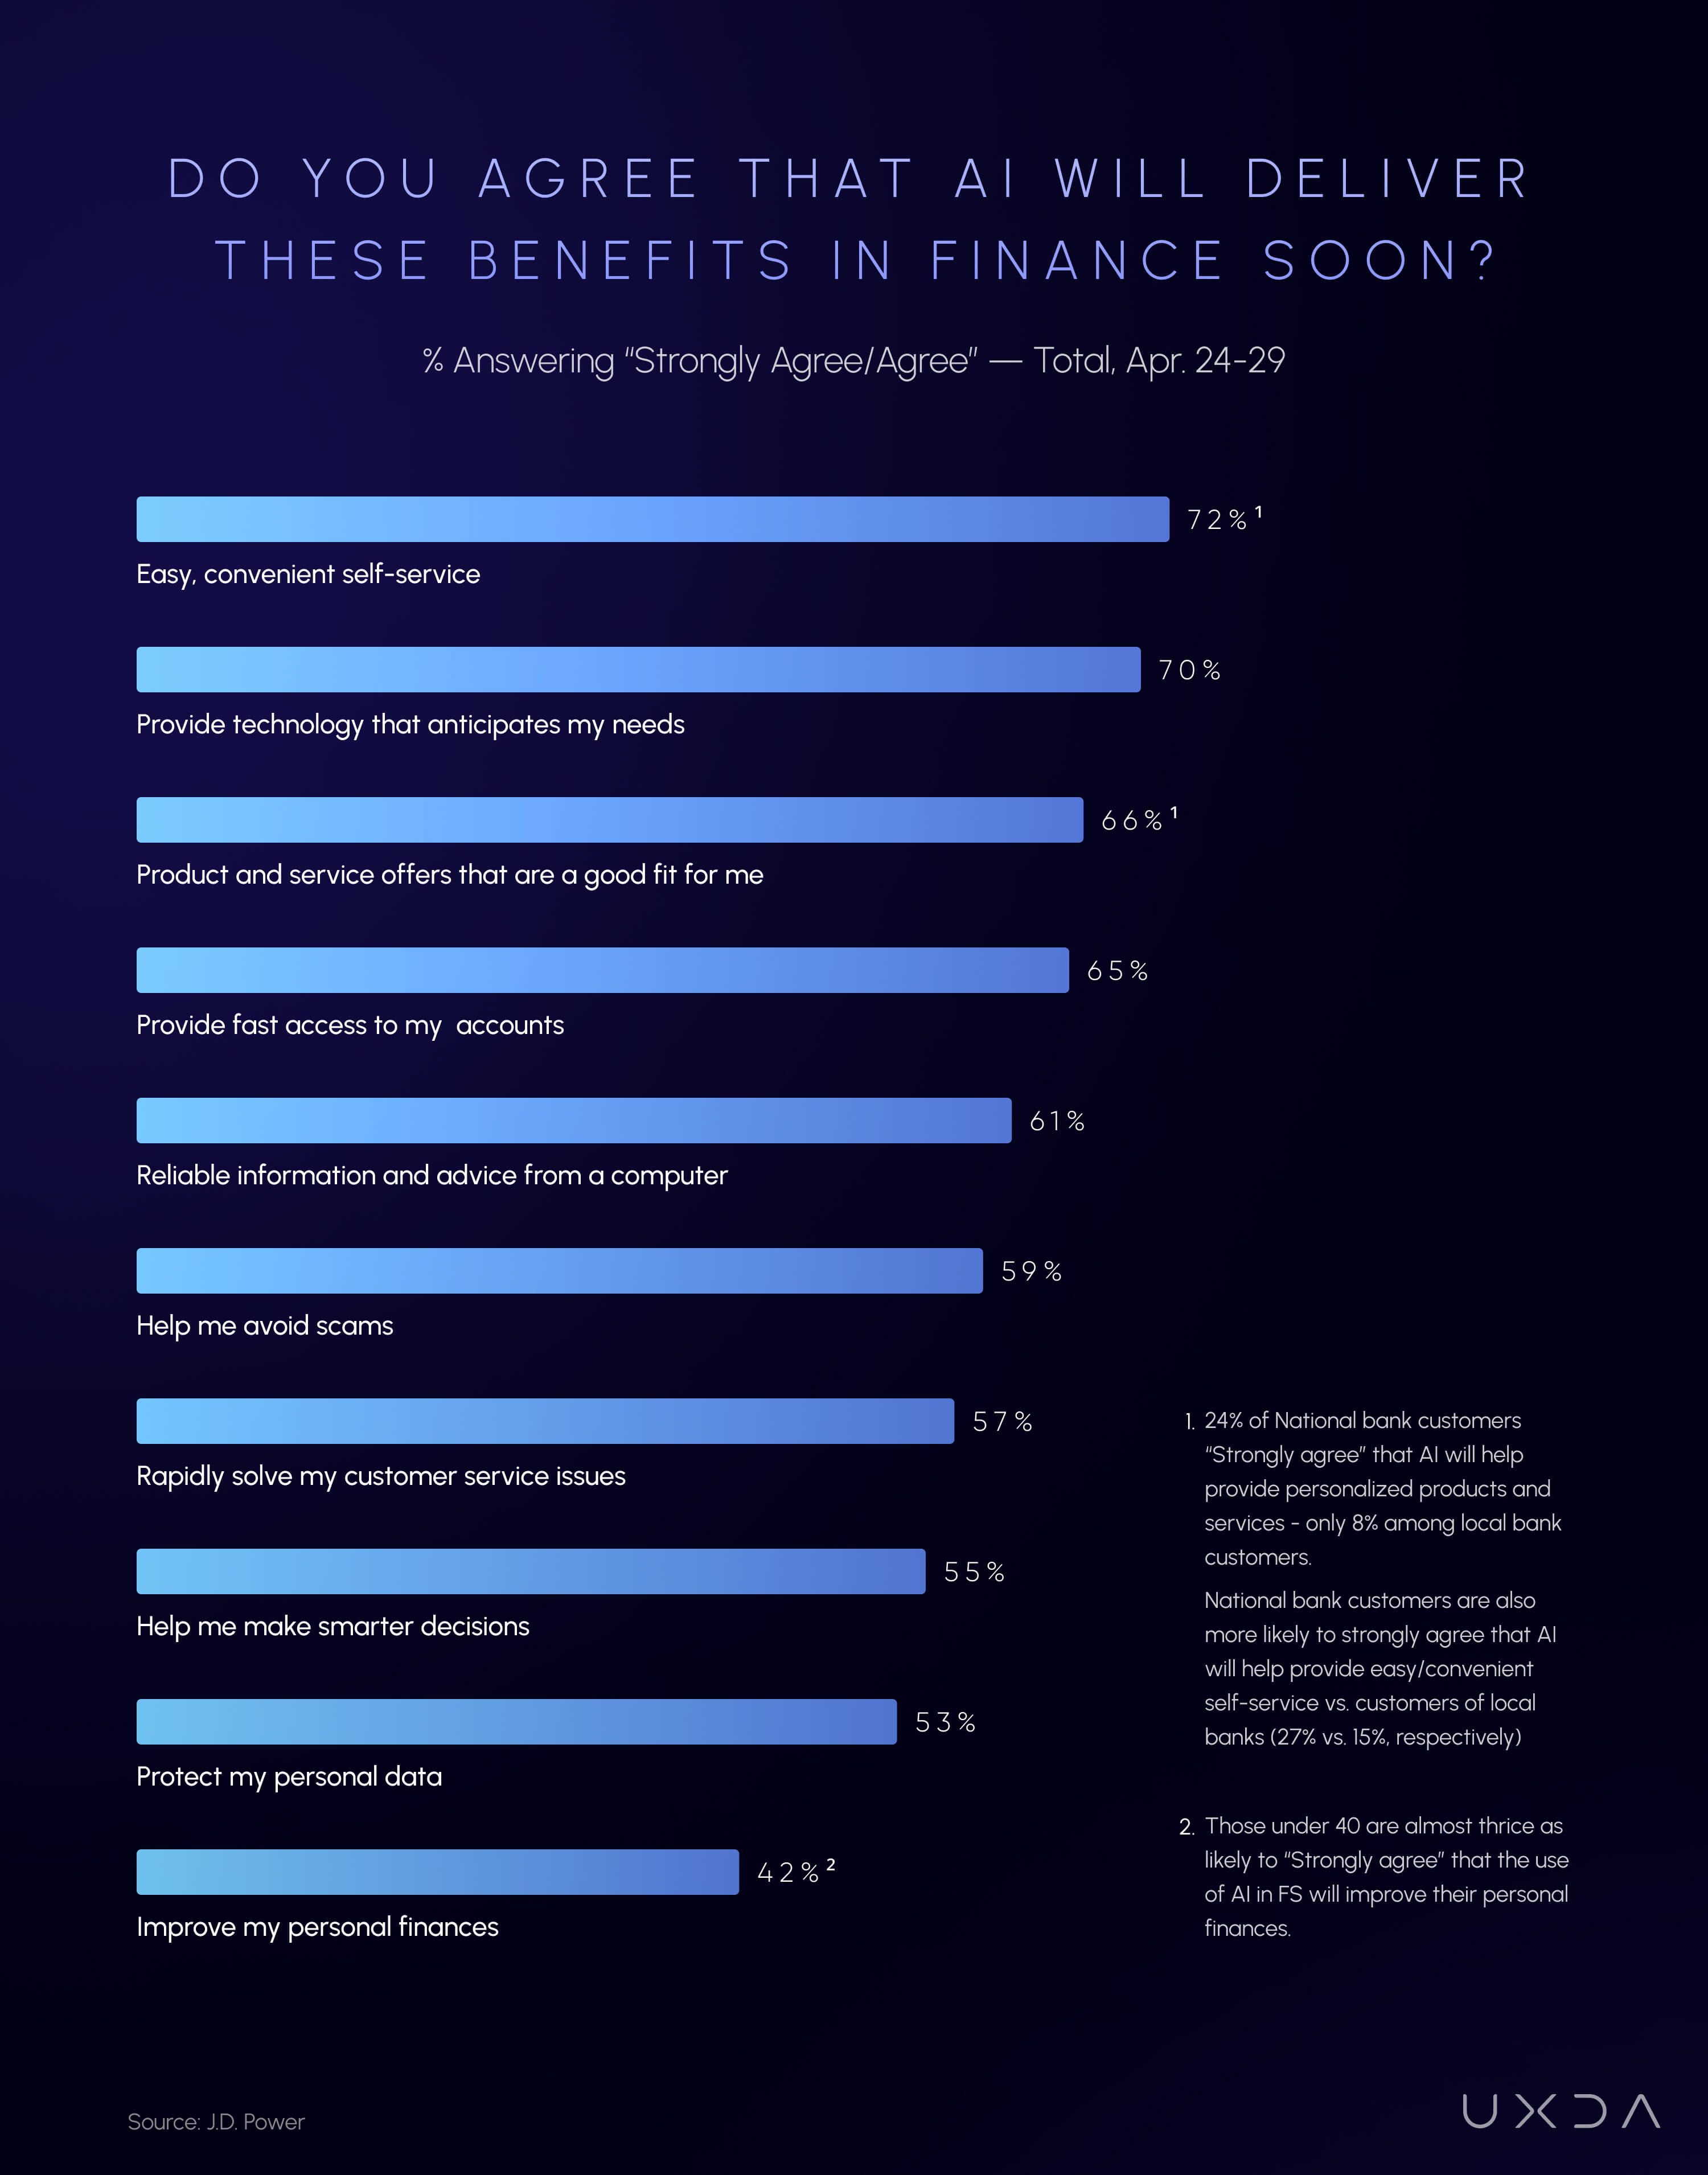 Source: J.D. Power
21 Real-World AI Banking Case Studies and Use Cases
These 21 AI banking case studies demonstrate how banks, payment networks and fintech companies are applying artificial intelligence to customer service, fraud prevention, financial advisory, personalization, lending and operational efficiency.
Each case examines the financial institution, AI application, implementation approach, reported results and customer experience implications. Together, they illustrate both the opportunities of AI in financial services and the importance of designing these technologies around real customer and business needs. On the customer side, AI assistants can handle 20 million chats around the clock—driving record engagement and a 150 percent jump in satisfaction scores even as call-center volumes fall by half.
Fraud-fighting models double detection rates, block over $350 million in attempted theft for the case and slice scam losses by up to 50 percent, with one bank saving 17 percent more funds for clients and processing 250,000 security queries each month. Instantaneous self-service resolves most issues in under two minutes, trims wait times by 40 percent and cuts repetitive contact by 55 percent, while algorithmic credit engines approve 44 percent more borrowers at 36 percent lower rates—proof that AI can widen access as well as convenience.
In short, from faster payments (60 percent quicker) to safer transactions and $40 million profit bumps from automated support, AI is quietly rewriting banking’s cost, risk and customer-experience equations in real time.
1. How JPMorganChase uses AI for personalized banking, fraud prevention, investment research and agentic automation
Financial AI Use Case: Generative AI, agentic AI, personalized banking, fraud detection, credit decisioning, investment research, wealth management, trading optimization, corporate treasury, employee productivity, workflow automation
Experience Impacted: CX – Banking Customer Experience; UX – Digital Banking User Experience; EX – Banking Employee Experience
AI Implementation: The largest U.S. bank, JPMorganChase scaled artificial intelligence across its banking operations, integrating predictive AI, generative AI and specialized AI agents into customer personalization, financial security, investment management and employee workflows. By 2025, its proprietary LLM Suite had reached more than 200,000 users, with approximately 150,000 weekly users reported in early 2026. The platform supports document analysis, research, content generation and operational automation, while more than 90% of engineers in Corporate & Investment Banking use AI coding assistants.
In retail banking, JPMorganChase uses machine learning for fraud detection, credit decisions, personalized offers, pricing and service optimization. AI-driven personalization of Chase's mobile banking home screen delivered 25% higher engagement, while the bank reported a 21% year-over-year reduction in fraud and scam claim rates across payment methods in 2025. The bank also expanded AI-enabled operational tools for customer service, risk assessment and financial security.
In wealth management and investment banking, its AI-powered SpectrumIQ platform analyzes research and financial data covering approximately 90,000 securities and 22 million documents, reducing time from manual research to investment insight by 80%. Its Connect Coach platform supports 12,000 wealth management users with 25 specialized AI agents, delivering one million personalized insights to help advisors prepare meetings, analyze portfolios and strengthen client relationships. AI-powered proxy voting also supports investment stewardship decisions across more than 3,000 annual company meetings.
In corporate banking and financial operations, AI-powered transaction screening enables JPMorganChase to review more than twice the transaction volume while halving manual operator checks. The bank also uses AI for cash-flow forecasting, liquidity management, securities inventory optimization and trading risk assessment. Earlier AI improvements reduced KYC processing unit costs by nearly 40%, while a newly deployed Employee Assistant provides personalized support across internal workflows.
Financial customer experience impact: JPMorganChase demonstrates how AI can transform banking beyond employee productivity. Customers benefit from more relevant digital experiences, stronger fraud protection and faster financial processes, while wealth management clients receive more contextual advisor support. Institutional customers gain improved transaction processing and liquidity forecasting, connecting AI-driven operational efficiency with more responsive financial services.
UX lesson: AI creates greater strategic value when intelligence is embedded across the entire financial experience rather than added as isolated assistants or features. JPMorganChase demonstrates how combining predictive personalization, financial security, agentic workflows and employee intelligence can improve customer relationships and service efficiency while preserving human expertise, governance and trust.
2. How Morgan Stanley uses AI for personalized wealth management, investment research and financial advisory automation
Financial AI Use Case: Generative AI, personalized wealth management, investment research, financial advisor assistance, portfolio risk analytics, client engagement, meeting automation, employee productivity
Experience Impacted: CX – Financial Customer Experience; EX – Banking Employee Experience; UX – Digital Wealth Management Experience
AI Implementation: US investment bank Morgan Stanley expanded artificial intelligence across wealth management, investment research and institutional banking, combining generative AI, machine learning and predictive analytics to improve financial advice, client personalization and operational efficiency.
Its OpenAI-powered AI @ Morgan Stanley Assistant provides financial advisors with access to institutional knowledge, investment research and financial insights. The assistant achieved 98% adoption among financial advisor teams, enabling faster retrieval and synthesis of information from the firm's extensive research library. Morgan Stanley also introduced AI @ Morgan Stanley Debrief, which automatically captures client meeting notes with consent, summarizes discussions, identifies action items, drafts follow-up communications and integrates records into Salesforce. Advisors reported saving approximately 30 minutes per meeting. Debrief received a 2025 Celent Model Wealth Manager Award for Emerging Technologies.
Beyond generative AI assistance, Morgan Stanley uses predictive intelligence for personalized wealth management. Its Next Best Action engine recommends timely, relevant investment ideas and engagement opportunities for financial advisors, while its Genome capability uses machine learning and customer analytics to personalize financial content, products and communications across advisory, workplace and self-directed investment channels. The firm's Portfolio Risk Platform also supports scenario analysis and risk assessment, helping advisors evaluate portfolio exposure and make more informed investment recommendations.
In institutional banking, Morgan Stanley deployed AskResearchGPT, an OpenAI-powered research assistant supporting investment banking, sales, trading and research teams. The platform retrieves and synthesizes information from the firm's research library, which produces more than 70,000 proprietary reports annually, and helps employees prepare research-backed client communications with links to original sources. In September 2026, Morgan Stanley further expanded its collaboration with OpenAI as a design partner for AI-powered financial research, modeling and analytical workflows.
Financial customer experience impact: Morgan Stanley demonstrates how AI can improve financial relationships by connecting institutional intelligence with personalized human advice. Financial advisors can retrieve research faster, prepare more relevant portfolio recommendations and spend less time documenting meetings. Predictive personalization enables more contextual client engagement, while automated follow-ups help improve service continuity. In institutional banking, AI-assisted research gives client-facing teams faster access to financial analysis and investment insights.
UX lesson: AI creates greater value in wealth management when it connects institutional intelligence, predictive personalization and human expertise across the entire advisory journey. Morgan Stanley illustrates how AI can reduce operational friction and strengthen financial relationships without replacing the judgment, accountability and trust essential to personalized financial advice.
3. How Goldman Sachs uses AI for investment banking, trading, risk management and agentic workflow automation
Financial AI Use Case: Generative AI, agentic automation, investment banking, capital markets analytics, trading, risk management, KYC, client onboarding, regulatory compliance, employee productivity
Experience Impacted: EX – Banking Employee Experience; CX – Institutional Banking Customer Experience; UX – Digital Financial Services Experience
AI Implementation: US investment bank Goldman Sachs expanded artificial intelligence across its operations, combining generative AI, machine learning and agentic automation to improve employee productivity, institutional client services, financial operations and risk management.
Its proprietary GS AI Assistant grew from approximately 10,000 employees in early 2025 to 40,000 users by May 2026, reaching nearly the entire workforce. The platform helps employees analyze documents, summarize research, generate content, interpret data and automate repetitive tasks. By May 2026, employees were submitting approximately 2 million prompts per month. Goldman Sachs also reported a 20% productivity improvement across the software development lifecycle, supported by AI coding assistants and engineering automation.
In 2026, Goldman Sachs expanded its collaboration with Anthropic to develop specialized AI agents for trade accounting, transaction reconciliation, client due diligence and onboarding. These systems are designed to support complex, multi-step financial operations rather than simply answer employee questions. The bank's broader One Goldman Sachs 3.0 transformation program targets six operational areas: client onboarding and KYC, lending, regulatory reporting, enterprise risk management, vendor management and sales enablement.
In investment banking and capital markets, Goldman Sachs is developing AI capabilities to improve information retrieval, financial analysis and institutional workflows. Its Marquee platform provides digital trading, market analytics and risk-management capabilities for institutional clients, while the bank is advancing AI-enabled tools designed around proprietary financial data, reliable information retrieval and auditable outputs.
Goldman Sachs also applies advanced analytics and machine learning across financial risk management, trading infrastructure and operational controls. Its AI governance framework emphasizes model oversight, risk assessment and accountability as the bank expands AI integration into regulated financial processes.
Financial customer experience impact: Goldman Sachs demonstrates how AI can improve financial services by transforming the operations behind institutional client relationships. Faster information retrieval and employee assistance can support more responsive service, while automation of onboarding, transaction processing and compliance creates opportunities to reduce operational delays. AI-enhanced analytics and risk-management capabilities can also help institutional clients access more relevant financial information and make informed decisions.
UX lesson: AI creates greater strategic value when financial institutions redesign complete operational and customer journeys rather than simply automate individual employee tasks. Goldman Sachs illustrates the importance of connecting intelligent assistance, financial analytics, agentic workflows and governance to improve institutional service efficiency while preserving human judgment, transparency and accountability.
4. How Bank of America uses AI for personalized banking, wealth management, fraud prevention and customer service
Financial AI Use Case: Conversational banking, personalized financial assistance, AI fraud detection, generative AI customer service, wealth management automation, corporate treasury intelligence, employee productivity
Experience Impacted: CX – Banking Customer Experience; UX – Digital Banking User Experience; EX – Banking Employee Experience
AI Implementation: US banking giant Bank of America expanded artificial intelligence across its financial services ecosystem, connecting customer assistance, fraud prevention, wealth management, corporate banking and employee productivity through reusable AI technologies.
In retail banking, its AI-powered virtual financial assistant Erica provides conversational self-service, proactive financial insights, transaction monitoring and personalized guidance. Launched in 2018, Erica surpassed 3.2 billion cumulative client interactions by March 2026, with 20.6 million customers using the assistant nearly 700 million times in 2025. Bank of America also reported that more than 98% of Erica users found the information they needed, demonstrating the assistant's effectiveness in helping customers access banking information and services.
In fraud prevention and financial security, Bank of America deployed more than 50 AI-enabled fraud detection models to identify suspicious activity and strengthen customer protection. Its broader security approach combines automated risk detection with proactive alerts, customer education and digital security controls. The bank sends more than one billion fraud and scam education messages annually, helping customers recognize potential threats and take preventive action.
In wealth management, Merrill and Bank of America Private Bank introduced an AI-Powered Meeting Journey in March 2026 to automate meeting preparation, summarize client conversations with consent and generate follow-up tasks. The bank reported that the solution could save financial advisors up to four hours per meeting, creating more capacity for personalized advice and client relationships. Its ask MERRILL and ask PRIVATE BANK assistants also provide employees with faster access to institutional knowledge, recording more than 23 million interactions in 2024.
In corporate banking and treasury management, Bank of America's AI-powered CashPro Chat and CashPro Search help business customers track transactions, resolve inquiries and access payment information. CashPro Chat usage increased 21% year over year in 2025, while CashPro Search exceeded 18 million cumulative searches. Among early adopters, transaction search reduced phone and email inquiries by 20%. In September 2026, the bank also launched Payments Insights, expanding its AI-powered CashPro Data Intelligence suite to help corporate clients analyze payment efficiency, cross-border flows and working-capital performance.
For employee productivity, Bank of America expanded EricaAssist with generative AI in July 2026. Used by more than 18,000 customer service employees, the assistant delivers contextual guidance in under three seconds and reduces average call handling time by nearly one minute. The bank also uses AI-powered employee knowledge tools, training simulators and generative AI applications across business operations. In September 2026, it expanded Ask Global Payments Solutions (AskGPS) with an Intelligence Hub designed to combine client, account and relationship information for more contextual treasury assistance.
Financial customer experience impact: Bank of America demonstrates how AI can improve financial experiences across both customer-facing interactions and the operations behind them. Erica simplifies everyday banking, predictive fraud detection strengthens security, and AI-powered wealth management tools enable advisors to provide more timely and personalized service. Corporate customers benefit from faster transaction tracking and more actionable treasury insights, while AI-assisted employees can resolve inquiries more efficiently. Together, these capabilities support a more connected, proactive and responsive banking experience.
UX lesson: AI creates greater strategic value when intelligence connects customer self-service, financial security, personalized advice and human assistance across the entire banking relationship. Bank of America demonstrates how reusable AI capabilities can scale across retail, wealth and corporate banking while preserving human judgment and customer trust.
5. How Wells Fargo uses AI for conversational banking, wealth management, lending and agentic automation
Financial AI Use Case: Conversational banking, personalized financial insights, predictive banking, wealth management, AI financial advisor assistance, commercial lending, agentic workflow automation, customer service, employee productivity
Experience Impacted: CX – Banking Customer Experience; UX – Digital Banking User Experience; EX – Banking Employee Experience
AI Implementation: US banking giant Wells Fargo expanded artificial intelligence across its banking ecosystem, integrating conversational AI, generative AI, predictive analytics and specialized AI agents into retail banking, wealth management, commercial lending and internal operations.
In retail banking, its AI-powered virtual assistant Fargo, launched in 2023, surpassed 1 billion cumulative customer interactions by March 2026, with nearly 600 million interactions reported during 2025. Powered by Google Cloud AI technologies and Wells Fargo's internal orchestration systems, Fargo helps customers complete everyday financial tasks through natural language, including Zelle transfers, bill payments, account inquiries and spending analysis. Its capabilities also include personalized transaction insights, subscription monitoring and cash-flow forecasting. More than 3 million Spanish-speaking customers have used Fargo over 160 million times, expanding access to conversational banking across languages.
In wealth management, Wells Fargo launched Advisor Gateway in May 2026, integrating more than 200 financial advisory tools into a unified workspace. Its generative AI-powered Auto Commentary, developed through BlackRock's Aladdin Wealth technology, synthesizes portfolio risk analytics, customer holdings and investment preferences into structured insights for financial advisors. In July 2026, the bank introduced AI Teammate, a conversational assistant embedded in Advisor Gateway that helps advisors retrieve institutional knowledge, summarize information and navigate workflows more efficiently.
In commercial banking and lending, Wells Fargo began deploying agentic AI to automate parts of commercial underwriting analysis and document preparation. These tools assist employees with reviewing financial information and preparing credit documentation, while human specialists remain responsible for evaluating outputs and making consequential decisions. The bank also introduced AI agents into contact centers and internal help desks to automate routine administrative work and support service employees.
For employee productivity, Wells Fargo significantly expanded enterprise generative AI adoption in 2025. Approximately 190,000 employees gained access to Microsoft Copilot Chat, with around 40,000 using Microsoft 365 Copilot for document analysis, information retrieval and workplace productivity. Its secure internal AI platform, supporting multiple language models and customized agents, reached approximately 25,000 users. In software engineering, Wells Fargo reported a 35% increase in code written where generative AI tools had been deployed, alongside shorter development cycles.
In financial security and risk management, Wells Fargo continues applying advanced analytics and established machine-learning capabilities within its wider risk-control environment while strengthening safeguards against AI-enabled financial crime. Its enterprise AI governance includes model validation, employee training and controls addressing data privacy, cybersecurity, regulatory compliance and model reliability.
Financial customer experience impact: Wells Fargo demonstrates how AI can improve both visible banking interactions and the operations behind them. Fargo makes everyday financial tasks more accessible through conversational assistance and personalized insights, while AI-supported advisors can retrieve financial information and prepare more relevant client recommendations. Agentic lending workflows create opportunities to accelerate commercial credit processes, and AI-assisted service teams can reduce administrative friction. Together, these capabilities support more responsive, personalized and consistent banking experiences.
UX lesson: AI creates greater customer value when conversational assistance, financial intelligence and operational automation work together across the banking relationship. Wells Fargo demonstrates how financial institutions can move beyond isolated AI features toward connected, intent-driven experiences that simplify customer interactions, strengthen human expertise and improve the processes behind financial services.
6. How Citibank uses AI for personalized banking, wealth management, agentic automation and institutional services
Financial AI Use Case: AI-powered personal finance management, open banking, personalized financial insights, conversational wealth management, generative AI, agentic automation, institutional banking, lending, risk management, employee productivity
Experience Impacted: CX – Banking Customer Experience; UX – Digital Banking and Wealth Management Experience; EX – Banking Employee Experience
AI Implementation: Global financial institution Citi expanded artificial intelligence across its banking ecosystem, connecting predictive analytics, generative AI and specialized AI agents across retail banking, wealth management, institutional services, lending and internal operations. By September 2026, Citi had deployed its proprietary AI tools to more than 180,000 employees across 87+ countries and jurisdictions, recording over 65 million interactions with the tools since December 2024 and an adoption rate exceeding 87%.
In retail banking and personal financial management, Citibank Hong Kong's Wealth 360, introduced in 2024, uses AI-powered financial insights and open banking to help customers manage spending, monitor cash flow and plan financial goals. Developed with Planto and Doconomy, it provides personalized budgeting recommendations, spending analysis and carbon footprint tracking. Through Hong Kong's Interbank Account Data Sharing (IADS) initiative, customers can connect eligible accounts from HSBC, DBS, Standard Chartered and Bank of China (Hong Kong), creating a consolidated view of their finances across institutions.
In wealth management, Citi introduced several AI-powered experiences in 2025–2026. Portfolio Intelligence provides personalized investment insights, while Advisor Insights identifies relevant client engagement opportunities. AskWealth and AskWealth CIO help financial advisors retrieve institutional research and investment guidance. Client 360 consolidates customer holdings, interests and interaction history, while CitiScribe, rolled out to North American wealth advisors in Q1 2026, automatically summarizes client meetings and prepares follow-up documentation.
In April 2026, Citi also unveiled Citi Sky, a conversational AI wealth assistant developed with Google Cloud and Google DeepMind. Designed for a phased U.S. rollout, Citi Sky combines natural-language interactions, voice and avatar technology with contextual financial insights, investment guidance and human advisor support. Its goal is to help clients understand their financial situation and act on relevant opportunities through more intuitive interactions.
In institutional banking and financial operations, Citi deployed CitiService Agent Assist, a generative AI solution helping service employees retrieve information and respond to client inquiries more accurately. AI is also being applied to trade confirmation processing, corporate lending, credit reviews and KYC automation. In September 2026, Citi launched an AI-enhanced Market Guide platform covering more than 100 custody markets, providing institutional investors with faster access to market-specific post-trade intelligence.
For employee productivity and agentic automation, Citi expanded its proprietary Stylus, Stylus Workspaces, Citi Assist and Citi Squad tools for document analysis, knowledge retrieval, research and workflow automation. In September 2025, Citi introduced agentic capabilities in Stylus Workspaces, allowing employees to coordinate multi-step tasks using connected internal systems. Its Arc AI agent platform, introduced in April 2026, enables developers to build governed AI agents for specialized financial workflows. Citi also reported that AI-assisted software development generates approximately 100,000 hours of additional development capacity per week, supporting faster technology modernization.
Financial customer experience impact: Citi demonstrates how AI can connect fragmented financial information, personalized advice and operational intelligence across different customer segments. Wealth 360 gives retail customers a more holistic understanding of their finances, while Citi Sky and Portfolio Intelligence aim to make wealth management more conversational and proactive. Institutional customers benefit from faster access to financial information and AI-assisted service, while employee automation creates opportunities to reduce onboarding, lending and operational friction.
UX lesson: AI creates greater strategic value when fragmented financial data, intelligent assistance and operational workflows become one connected experience. Citi illustrates how financial institutions can move beyond isolated AI features toward a more unified financial relationship, combining personalized insights, conversational guidance and intelligent execution while preserving human expertise, customer control and trust.
7. How Royal Bank of Canada uses AI for personalized banking, credit decisions, investment research and trading automation
Financial AI Use Case: Automated savings, predictive banking, personalized financial guidance, AI credit underwriting, digital identity verification, investment research, electronic trading, generative AI, agentic automation, employee productivity
Experience Impacted: CX – Banking Customer Experience; UX – Digital Banking and Investment Experience; EX – Banking Employee Experience
AI Implementation: Canada's largest bank, Royal Bank of Canada (RBC), expanded artificial intelligence across its financial services ecosystem, integrating predictive AI, proprietary foundation models, generative AI and reinforcement learning into retail banking, credit decisions, capital markets and operational workflows. Its AI capabilities are supported by RBC Borealis, the bank's dedicated AI research institute, and Lumina, its enterprise data and AI platform.
In personal banking, RBC's AI-powered NOMI suite provides automated savings, spending analysis, personalized financial insights and predictive cash-flow guidance. According to its 2025 Annual Report, NOMI Find & Save helped customers set aside more than CAD 9.6 billion cumulatively since 2017, while approximately 1.3 million customers had used NOMI Forecast to anticipate upcoming payments and expenses. NOMI also connects financial insights with RBC InvestEase, helping customers identify opportunities to save and invest.
In credit underwriting and financial inclusion, RBC applies machine learning to assess customers' financial circumstances and personalize credit decisions. In October 2026, the bank reported that its AI models enabled approximately 40% more credit-limit increases for Canadians with less than two years of credit history compared with conventional methods, translating into nearly CAD 300 million in additional credit extended to customers establishing their financial history.
In capital markets and investment banking, RBC expanded its proprietary Aiden AI platform across all 8,000 Capital Markets employees. Its Aiden QuickTakes generates draft investment research reports up to 95% faster, helping analysts increase company coverage from an average of 14.5 companies per analyst in 2024 to more than 17.5 in 2026. AidenBanker supports pitchbook preparation, meeting planning and client documentation, while Aiden's electronic trading capabilities use reinforcement learning to adapt execution strategies to changing market conditions.
For commercial banking and lending operations, RBC uses AI to ingest financial statements, organize financial data and support credit analysis. Its proprietary ATOM foundation model, deployed across 15 products and processes in 2025, supports credit assessment and personalized financial recommendations, including tailored Avion Rewards offers. RBC is also developing AI-enabled mortgage and commercial banking workflows to reduce processing friction and improve employee decision support.
In digital security and customer service, RBC uses AI-enabled government identity verification to support safer, faster digital onboarding. Its intelligent digital assistant uses natural-language intent detection to direct customers to relevant services or human advisors. Internal AI-powered knowledge search also processes approximately 2 million policy and procedure searches per month, helping banking employees retrieve information more efficiently.
For employee productivity, RBC scaled its proprietary RBC Assist and Aiden tools to more than 72,000 employees by October 2026, while approximately 10,000 technologists used additional AI tools for software development and technology operations. By the second quarter of 2026, AI had contributed to more than 24 million lines of code and 120,000 code reviews, supporting modernization of the bank's technology infrastructure.
Financial customer experience impact: RBC demonstrates how AI can improve financial experiences beyond personalized insights. NOMI helps customers save and manage cash flow proactively, while AI-enhanced credit assessment expands access to financing for customers with limited credit histories. Intelligent identity verification simplifies onboarding, and AI-supported advisors can deliver more timely financial information and investment insights. In capital markets, automated research and trading analytics support faster institutional decision-making.
UX lesson: AI creates greater strategic value when it improves the financial decisions and processes behind customer experiences—not simply the information presented on screen. RBC demonstrates how predictive intelligence, personalized financial guidance, more inclusive credit assessment and AI-assisted human expertise can work together to make banking more proactive, accessible and responsive.
8. How HSBC uses AI for fraud prevention, personalized wealth management, trade finance and agentic banking
Financial AI Use Case: AI fraud detection, anti-money laundering, personalized wealth management, investment research, customer service automation, credit analysis, AI-powered trade finance, corporate treasury, agentic banking, cybersecurity, employee productivity
Experience Impacted: CX – Banking Customer Experience; UX – Digital Banking and Wealth Management Experience; EX – Banking Employee Experience
AI Implementation: Global banking group HSBC scaled artificial intelligence across more than 600 operational use cases, integrating predictive AI, generative AI and automation into financial crime prevention, wealth management, customer service, lending, trade finance and institutional banking. By 2025, HSBC had more than 100 generative AI solutions in use, demonstrating a shift from experimentation toward enterprise-wide implementation.
In financial crime prevention, HSBC's AI-powered Dynamic Risk Assessment system, developed with Google Cloud, identifies two to four times more suspicious activity while reducing false-positive alerts by approximately 60% compared with its previous rules-based approach. The system analyzes transaction patterns and relationships to identify potential money laundering more accurately, reducing unnecessary investigations and customer disruption. HSBC also applies AI to fraud detection, cybersecurity, transaction monitoring and risk assessment.
In wealth management, HSBC launched Wealth Intelligence, a generative AI platform that analyzes and summarizes investment research and financial news from more than 10,000 data sources. Introduced in Hong Kong and Singapore in 2025 and expanded to additional markets in 2026, the solution helps relationship managers prepare personalized investment insights and provide more relevant financial guidance. In June 2026, HSBC also expanded its partnership with Google Cloud to develop advanced AI-powered wealth personalization, financial crime detection and frontline relationship management capabilities.
In corporate banking and customer service, HSBC deployed a generative AI assistant supporting teams responsible for approximately 3 million institutional client interactions annually, helping employees retrieve information and reduce service turnaround times. The bank also uses generative AI to prepare credit analysis reports using trusted financial data, accelerating parts of the lending application process.
In trade finance, HSBC introduced Smart Checking, an AI-powered solution for reviewing documentary credits and collections. Combining document extraction, AI reasoning and a knowledge graph, the system analyzes trade documents, checks transaction-specific requirements and directs uncertain or complex cases to human specialists. This approach is designed to reduce manual processing, improve auditability and accelerate trade finance workflows that support business liquidity and working capital.
In corporate treasury and agentic banking, HSBC launched HSBCnio in September 2026, connecting accounts, payments, foreign exchange and trade services through digital channels, APIs and AI-enabled interfaces. Its Model Context Protocol (MCP) connectivity allows corporate clients' own AI tools to access authorized banking information within established permissions. HSBC is also developing Ask HSBC, a conversational assistant intended to help business clients interpret account and payment information.
For employee productivity, HSBC expanded its internal Productivity Suite to approximately 85% of employees, supporting document analysis, summarization and translation. Its 2025 Annual Report also disclosed that more than 31,000 engineers were using AI coding assistants, while an earlier update reported a 15% improvement in coding-time efficiency. In 2026, HSBC strengthened enterprise AI leadership and announced a Google Cloud partnership expected to support more than 200 additional AI use cases over the following two years.
Financial customer experience impact: HSBC demonstrates how AI can improve financial experiences across security, advice, lending and complex business transactions. More accurate financial crime detection can reduce unnecessary disruption to legitimate customers, while Wealth Intelligence helps advisors provide more timely and contextual investment guidance. AI-assisted customer service and credit analysis create opportunities for faster responses and lending decisions. Smart Checking and HSBCnio extend these benefits into trade finance and treasury, where reduced processing friction and better access to financial information can improve business customers' control over cash flow.
UX lesson: AI creates greater strategic value when it makes complex financial relationships more intelligent, proactive and easier to manage—not simply when it automates individual tasks. HSBC demonstrates how connected intelligence across financial security, personalized advice, lending and corporate banking can reduce friction while maintaining human oversight, transparency and customer trust.
9. How DBS Bank uses AI for personalized banking, agentic customer service, wealth management and fraud prevention
Financial AI Use Case: Personalized banking, predictive financial insights, fraud prevention, conversational AI, agentic banking, wealth management, SME lending, trade finance automation, KYC and compliance, employee productivity
Experience Impacted: CX – Banking Customer Experience; UX – Digital Banking and Wealth Management Experience; EX – Banking Employee Experience
AI Implementation: Singapore-based DBS Bank scaled artificial intelligence across its financial services ecosystem, integrating predictive AI, generative AI and agentic automation into retail banking, wealth management, customer service, lending, risk management and institutional operations. In 2025, DBS deployed more than 2,000 AI models across 430+ use cases, generating approximately SGD 1 billion in economic value from data analytics and AI/ML initiatives.
In retail banking and personalized financial management, DBS uses machine learning to deliver hyper-personalized financial insights, spending alerts and investment recommendations. Its Intelligent Banking platform analyzes customer behavior to identify upcoming payments, financial risks and relevant opportunities. According to DBS's 2025 Annual Report, customers who engaged with AI-powered financial nudges saved twice as much, invested five times as much and held three times the insurance coverage of non-users. DBS also applies predictive analytics to identify suspicious transactions and support proactive financial protection.
In conversational banking and agentic AI, DBS expanded its virtual assistants DBS digibot and DBS Joy to serve more than 10 million retail, wealth and corporate customers across Singapore, Hong Kong and Taiwan. By July 2026, GenAI-enabled digibot was resolving nine out of ten customer queries digitally without a follow-up call. DBS Joy, launched for business banking customers in 2025, evolved into an agentic assistant in Singapore in July 2026, allowing authenticated customers to retrieve and analyze payments, transactions and account information through natural-language requests. During the first half of 2026, its active users increased 61%, customer satisfaction rose 17%, and customer service calls or emails declined 7% in Singapore. DBS also began extending conversational assistance into its digiWealth platform, while more advanced consumer task execution and voice capabilities were scheduled for later rollout.
In wealth management, DBS combines predictive personalization with investment insights, portfolio monitoring and AI-supported relationship management. Its financial nudges help customers identify savings and investment opportunities, while AI-powered recommendations support advisors in delivering more contextual engagement. The bank introduced digiWealth, connecting investment and insurance services with access to human wealth planning managers.
In SME lending and corporate banking, DBS uses AI-powered credit analytics to identify eligible businesses and streamline financing. Its established DBS Quick Finance solution enables selected SMEs to apply for financing in approximately one minute, with credit decisions possible in one second. In trade finance, generative AI reduced processing times for selected trade conditions by 60%. DBS also introduced a customer service copilot that reduced call handling time by up to 20%.
In risk management and employee productivity, DBS applies AI to suspicious-transaction monitoring, credit-risk assessment, customer due diligence and adverse-news screening. Its generative AI-enhanced KYC name-screening processes delivered approximately 70% efficiency gains. Internally, DBS-GPT supports employees with information retrieval, document analysis and routine tasks, while iCoach provides personalized AI career coaching. DBS's enterprise platforms, including ADA, support governed deployment of AI models across the organization.
Financial customer experience impact: DBS demonstrates how AI can improve financial experiences from everyday money management to complex business banking. Predictive insights help customers recognize financial needs and opportunities, while conversational assistants simplify access to services. Agentic AI reduces the need to navigate multiple screens for selected tasks, and AI-powered lending and trade finance automation can reduce administrative friction for businesses. Human advisor access remains important for complex financial decisions.
UX lesson: AI creates greater customer value when financial intelligence progresses from providing information to anticipating needs and helping customers complete meaningful tasks. DBS demonstrates how predictive personalization, conversational assistance and agentic execution can work together across retail, wealth and corporate banking—provided customers retain clear control, security and access to human support.
10. How Lloyds Banking Group uses AI for personalized banking, fraud prevention, lending and agentic automation
Financial AI Use Case: Agentic banking, personalized financial guidance, conversational AI, fraud and scam prevention, commercial lending, credit underwriting, insurance claims automation, customer service assistance, generative AI, employee productivity
Experience Impacted: CX – Banking Customer Experience; UX – Digital Banking and Financial Management Experience; EX – Banking Employee Experience
AI Implementation: UK-based Lloyds Banking Group expanded artificial intelligence across its financial services ecosystem, integrating predictive AI, generative AI and specialized AI agents into everyday banking, financial security, commercial lending, insurance and internal operations. In 2025, Lloyds deployed more than 50 generative AI solutions, generating approximately £50 million in reported economic value, and accelerated agentic AI development in 2026.
In personalized banking and financial management, Lloyds introduced an agentic AI Financial Assistant to help customers understand spending, analyze transactions and receive contextual financial guidance through natural-language conversations. By June 2026, the assistant had reached more than 500,000 Bank of Scotland customers, with a wider rollout planned across Lloyds' mobile banking ecosystem. Its initial capabilities focus on transaction insights and financial questions, while expanded support for savings, investments, mortgages and protection forms part of the bank's longer-term roadmap. Built on curated financial data, the assistant combines personalized information with access to human support.
In fraud prevention and payment security, Lloyds deployed a new agentic AI fraud detection system in June 2026. Multiple AI agents support fraud specialists during customer interactions by performing identity checks, analyzing payment activity and assessing scam risks in real time. The system provides contextual recommendations while employees retain responsibility for final decisions. Lloyds also announced Scam Check, an AI-powered tool designed to assess potentially fraudulent online purchases by examining customer-provided marketplace screenshots and identifying scam indicators before payments are completed. The group's wider fraud protection systems prevented more than £1 billion in attempted fraud during 2025, although this figure covers its overall security capabilities rather than the newly deployed AI agents alone.
In commercial lending and credit analysis, Lloyds uses AI to process financial documents, extract relevant information and support faster underwriting decisions, including commercial real estate lending. An AI-powered document-processing solution reduced selected complex commercial property document reviews from several hours to approximately five minutes, helping relationship managers access information and assess applications more efficiently.
In insurance and protection, Lloyds' insurance business Scottish Widows partnered with Sprout.ai in 2025 to trial AI-powered claims processing and underwriting. The solution uses natural-language processing to analyze medical documents, summarize complex case information and support claims specialists. The initiative aims to shorten processing times and allow employees to concentrate on cases requiring human expertise and empathetic customer support.
In customer service and employee productivity, Lloyds expanded Athena, its AI-powered knowledge assistant, to approximately 20,000 employees, reducing average information search times by 66%. Its AI HR assistant resolved approximately 90% of employee inquiries correctly on first contact. The bank also expanded Microsoft 365 Copilot to 40,000 licensed employees, with 97% of license holders classified as active users by June 2026. AI-assisted software engineering reached more than 10,000 engineers, with selected legacy code conversion tasks showing a 50% improvement.
To scale agentic AI across banking operations, Lloyds launched Envoy in May 2026, a secure internal platform for developing, monitoring and reusing specialized AI agents. Envoy provides agent orchestration, governance and human oversight, supporting applications ranging from fraud prevention to customer service. By June 2026, more than 65,000 employees had completed AI training, supporting the bank's broader transition toward AI-enabled financial services.
Financial customer experience impact: Lloyds Banking Group demonstrates how AI can improve customer experiences both directly and behind the scenes. Its financial assistant simplifies access to personalized money management insights, while agentic fraud detection helps employees identify risks and intervene during critical payment journeys. AI-powered lending and document processing can reduce delays in financial applications, and insurance automation creates opportunities for faster, more supportive claims experiences. AI-assisted employees can also deliver more timely and consistent customer service.
UX lesson: AI creates greater strategic value when it connects proactive financial guidance, intelligent protection and faster service execution across the entire banking relationship. Lloyds Banking Group demonstrates how customer-facing assistance and agentic operational systems can work together to remove friction, anticipate risks and simplify complex financial journeys—while preserving customer control, human accountability and trust.
11. How BNY uses agentic AI for institutional banking, payments, asset servicing and investment operations
Financial AI Use Case: Agentic AI, client onboarding automation, payment processing and repair, settlement inquiry resolution, securities servicing, fund accounting, investment operations, risk monitoring, document analysis, employee productivity
Experience Impacted: CX – Institutional Financial Customer Experience; UX – Institutional Digital Financial Services Experience; EX – Employee Experience
AI Implementation: US-based global financial services institution BNY scaled its proprietary Eliza AI platform, integrating generative AI and specialized digital employees into complex institutional banking workflows. Built using a model-agnostic architecture incorporating Microsoft Azure, Microsoft Foundry and leading AI models, Eliza provides governed AI tools, reusable capabilities and agent orchestration. By September 2026, BNY reported more than 300 AI solutions in production, supported by digital employees designed to execute defined financial tasks alongside human specialists.
In client onboarding and compliance, Eliza's AI agents review financial documents, retrieve relevant information, conduct due diligence and support risk assessments. According to BNY's September 2026 results, AI assisted approximately 25% of new client onboardings, reducing completion times by an average of 20% for those clients. Agentic workflows help eliminate repetitive document reviews and administrative delays while retaining oversight of consequential decisions.
In payments and settlement operations, BNY deployed digital employees to validate and repair incomplete payment instructions, investigate transaction exceptions and support cross-border payment processing. AI now handles more than 10% of payment repair issues globally, while over 10% of selected client transaction inquiries are resolved or assisted by AI, resulting in 80% faster processing of those inquiries. These applications address operational friction that can otherwise delay the movement of funds or resolution of institutional client requests.
In asset servicing and fund accounting, BNY expanded AI into reconciliations, exception management, securities operations and net asset value (NAV) calculation. By October 2026, its Asset Servicing business had developed more than 40 AI solutions using Eliza. AI-powered transaction matching and data enrichment help reconcile financial records, while dynamic benchmarking detects unusual NAV patterns more precisely. In one reported fund-accounting application, AI reduced false-positive alerts from 90% to below 20%, allowing specialists to focus on genuine accounting exceptions. BNY is also extending intelligent NAV production and document validation across selected fund structures.
In risk management and financial analytics, BNY uses AI to monitor transactions and market conditions, detect anomalies and support portfolio-level credit risk assessment. Its AI-powered Contract Review Assistant compares negotiated agreements against internal standards and regulatory requirements. In September 2026, BNY and Microsoft also described an AI research capability for investigating complex accounting discrepancies, identifying probable root causes and recommending resolution steps; that initiative was entering a pilot phase.
For employee productivity and enterprise transformation, BNY trained its entire workforce of nearly 50,000 employees on Eliza, delivering more than 400,000 cumulative AI training hours. Approximately 60% had been onboarded to Microsoft 365 Copilot by September 2026. AI-powered development tools were contributing to substantial software engineering activity, with BNY reporting that 40% of code was AI-authored in Q2 2026. Its digital employees operate within defined governance frameworks covering access permissions, monitoring, auditability and human accountability.
Financial customer experience impact: BNY demonstrates how AI can improve institutional financial experiences by reducing delays and errors in the processes customers depend on. Faster onboarding simplifies access to financial services, automated payment repair helps transactions proceed with fewer interruptions, and AI-assisted settlement inquiries improve service responsiveness. More precise fund-accounting controls support reliable investment operations, while AI-assisted employees can devote greater attention to complex client needs.
UX lesson: Agentic AI creates the greatest financial customer value when it transforms the execution of complex service journeys, not merely the interfaces through which customers request them. BNY shows how intelligent agents can coordinate documents, decisions, transactions and exception handling across institutional systems. Achieving this at scale requires clearly defined agent responsibilities, transparent workflows, strong governance and human oversight to preserve trust in critical financial operations.
12. How NatWest uses AI for conversational banking, fraud prevention, personalized financial guidance and agentic automation
Financial AI Use Case: Generative AI, conversational banking, agentic financial assistance, personalized money management, fraud detection, AI-powered wealth management, mortgage assistance, business onboarding, identity verification, customer service automation, employee productivity
Experience Impacted: CX – Banking Customer Experience; UX – Digital Banking and Wealth Management Experience; EX – Banking Employee Experience
AI Implementation: UK-based NatWest Group expanded artificial intelligence across its banking ecosystem, integrating generative AI, predictive analytics and specialized AI agents into retail banking, financial security, wealth management, mortgages, commercial banking and employee operations.
In conversational banking, NatWest expanded generative AI across its Cora virtual assistant, increasing GenAI-supported customer journeys from four to 21 by the end of 2025. Cora handled 12.9 million retail banking conversations in 2025, with 50% requiring no human intervention. GenAI-supported journeys achieved an approximately 20-percentage-point higher autonomous resolution rate than comparable non-GenAI journeys. In 2026, NatWest also began trialling an agentic financial assistant within Cora, allowing selected customers to ask natural-language questions about their spending and receive personalized financial insights.
In personal financial management, NatWest developed Spending Insights, an experimental conversational experience powered by proprietary small language models. The voice-enabled assistant allows customers to explore spending patterns, compare transactions and ask follow-up questions through natural conversation, supported by interactive financial visualizations. Announced for trial with Royal Bank of Scotland customers in 2026, the experience represents NatWest's move toward more intuitive, personalized financial guidance rather than navigation-based self-service.
In fraud prevention and customer security, NatWest uses machine learning, real-time transaction monitoring and AI-driven risk analysis to identify suspicious payment activity and potential scams. In August 2026, the bank launched a Fraud Triage Agent within Cora, helping credit card customers describe suspicious transactions in their own words and reach the appropriate fraud, scam or dispute support. The agent handled nearly 19,000 customer conversations following its launch. NatWest is also researching continuous voice authentication and multimodal identity verification to strengthen protection against impersonation and deepfake fraud.
In wealth management and financial advisory, NatWest introduced AI-powered client intelligence that analyzes advisor conversations, captures relevant information and supports more personalized client engagement. Its AI call-summarization capabilities reduced the time spent on selected advisor documentation tasks by more than 70%, creating more capacity for relationship managers to focus on financial advice and complex customer needs.
In mortgage services and commercial banking, NatWest applies AI to affordability assessment, application preparation, document processing and customer onboarding. In 2025, it introduced AI-based digital identity verification for approximately one million Commercial & Institutional customers, reducing selected verification processes from days to minutes. In 2026, NatWest expanded business onboarding automation through AI agents that help verify company information, process documents and complete operational checks. For sole traders, selected checks that previously took approximately 15 minutes can now be completed in under 60 seconds. The bank expects its broader agentic onboarding program to automate up to 75% of manual interventions as additional capabilities are deployed.
For employee productivity, NatWest provided AI tools to approximately 60,000 employees, including generative AI assistance for research, customer support, document analysis and operational workflows. AI-powered summarization saves retail banking employees approximately 70,000 working hours annually, while more than 12,000 software engineers use AI coding assistants. NatWest also expanded agentic software development following pilots that demonstrated more than tenfold productivity improvements in selected engineering workflows.
Financial customer experience impact: NatWest demonstrates how AI can improve financial experiences across customer interactions and the processes behind them. Cora enables more customers to resolve banking inquiries independently, while conversational Spending Insights creates opportunities for more accessible and proactive money management. AI-powered fraud detection and triage simplify security support, especially when customers are unsure how to categorize suspicious activity. Faster identity verification and business onboarding reduce administrative friction, while AI-assisted advisors can spend more time understanding customers' financial needs.
UX lesson: AI creates greater customer value when it removes complexity from entire financial journeys—not simply when it automates conversations. NatWest demonstrates how conversational intelligence, proactive security, personalized guidance and agentic workflows can help customers move from explaining a problem to resolving it, while maintaining human support, transparency and control.
13. How Revolut uses AI for fraud detection
Financial AI Use Case: Conversational banking, agentic AI, personalized financial management, customer service automation, fraud prevention, credit risk assessment
Experience Impacted: CX – Banking Customer Experience; UX – Digital Banking User Experience; EX – Employee Experience
AI Implementation: Global fintech Revolut expanded AI across its digital banking ecosystem, combining intelligent financial assistance, automated customer support, personalized recommendations and AI-powered risk management.
In April 2026, Revolut launched AIR (AI by Revolut), an in-app conversational assistant initially rolled out in the UK. Unlike traditional banking chatbots, AIR helps customers complete financial tasks through natural-language requests, including analyzing spending, monitoring investments, managing subscriptions, freezing cards and purchasing travel eSIMs. The assistant is designed to reduce multi-step navigation and provides contextual assistance based on customers' financial activity, with biometric authorization required for sensitive actions.
Revolut also significantly expanded its AI-powered customer support in 2025. According to its annual report, the LLM-powered assistant now resolves more than 75% of customer queries, contributing to a 40% reduction in average customer support resolution times and a 12-percentage-point increase in the assistant's NPS during the year.
In August 2026, Revolut introduced PRAGMA, its proprietary financial AI foundation model, developed for fraud detection, credit risk assessment and personalized financial recommendations. Historical-data evaluations showed 65% more fraud cases detected, 2.3 times higher accuracy in identifying credit default risk and 41% more relevant product recommendations compared with previous models. Revolut also uses AI-powered transaction monitoring and contextual scam interventions to protect customers against financial crime.
Financial customer experience impact: Revolut demonstrates how AI can transform mobile banking from a collection of separate features into a more conversational, personalized and proactive financial experience. AIR simplifies everyday financial tasks, AI-powered support accelerates customer service, and predictive models can improve financial recommendations and security. Together, these capabilities create opportunities for more intuitive interactions, faster problem resolution and better-informed financial decisions.
UX lesson: AI creates a distinctive banking experience when it connects financial intelligence, customer assistance and task execution across the entire customer journey. Rather than adding isolated chatbots or AI features, financial institutions can use AI to replace fragmented navigation with contextual, intent-driven interactions that make financial management simpler, more proactive and more personal.
14. How BBVA uses AI for conversational banking, personalized financial advice, fraud prevention and agentic payments

Financial AI Use Case: Conversational banking, agentic AI, personalized financial management, fraud prevention, investment advice, AI-powered trading, commercial banking, credit-risk analysis, customer service automation, customer experience intelligence, employee productivity
Experience Impacted: CX – Banking Customer Experience; UX – Digital Banking and Wealth Management Experience; EX – Banking Employee Experience
AI Implementation: Spanish banking group BBVA expanded artificial intelligence across its global banking ecosystem, combining predictive analytics, generative AI and specialized AI agents to improve customer interactions, financial personalization, security, investment services and operational efficiency. By July 2026, the bank reported 1,127 AI use cases in production, supported by its global AI Factory and enterprise technology infrastructure.
In conversational banking and personalized financial management, BBVA expanded its generative AI-powered Blue assistant, integrated into its mobile banking app in Spain and Mexico. Blue interprets customers' natural-language requests, provides contextual financial information and helps complete selected account and card transactions without navigating multiple menus. In Türkiye, Garanti BBVA's Ugi evolved into an LLM-powered banking assistant supporting more than 300 end-to-end banking transactions. By May 2026, Ugi recorded approximately 6.4 million monthly interactions and 1.6 million active users, understood 90% of user requests and delivered around 780,000 proactive notifications per month.
BBVA also introduced more personalized and proactive banking experiences through its redesigned mobile app, Futura, using AI to adapt financial information and services to individual customer needs. In February 2026, BBVA launched conversational applications within ChatGPT in Italy and Germany, enabling users to explore banking products through natural-language questions. Garanti BBVA followed in July 2026. These external ChatGPT integrations initially provide product and service information rather than authenticated access to personal accounts or banking transactions.
In financial security, fraud prevention and agentic payments, BBVA applies machine learning to transaction monitoring, risk analysis and fraud detection. In July 2026, it completed its first AI agent-initiated card transaction with Visa, demonstrating a payment initiated on behalf of a cardholder using real payment credentials, tokenization, fraud monitoring and biometric authentication. The transaction was part of a controlled agentic-commerce initiative, not a generally available autonomous payment service.
In wealth management and investment banking, BBVA uses AI-powered analytics to support investment decisions and portfolio personalization. In Mexico, its BPyP Investment Portfolio Optimization model helps evaluate investment allocations for high-net-worth customers in line with their risk profiles. In September 2026, BBVA introduced On The Fly Ideas within its ePricer platform, using AI to suggest relevant structured investment products while institutional clients are pricing transactions. AI also supports trading desks with market analysis, pricing, execution and risk management.
In commercial banking and credit operations, more than 7,000 commercial banking professionals were using AI tools by August 2026 to support customer service, financial analysis, risk assessment and relationship management. AI assists employees with preparing financial information, responding to client inquiries and supporting complex commercial workflows, while human bankers remain responsible for consequential financial decisions.
For customer service and experience management, BBVA deployed generative AI copilots in Italy and Germany that reduced average handling times for common customer inquiries by more than 15%. The bank also uses AI to analyze customer interactions and identify unmet needs, service problems and opportunities for improvement, including more than 220,000 monthly calls between customers and remote relationship managers in Mexico. By October 2026, AI assistants were filtering more than half of the conversations received by Spanish relationship managers through the app, while voice-agent production pilots in Peru and Mexico resolved close to 90% of selected interactions. AI also reduced the time required to register complaints by nearly 80%.
In employee productivity and enterprise automation, BBVA expanded ChatGPT Enterprise to approximately 100,000 employees globally by June 2026. Employees reported saving around three hours per week, with efficiency improvements of up to 80% in selected workflows. An internal assistant in Peru reduced average employee inquiry handling times from approximately 7.5 minutes to one minute. By October 2026, BBVA reported approximately 28% higher software developer productivity and introduced The Frame, a common framework for developing, deploying and governing specialized AI agents across the organization.
Financial customer experience impact: BBVA demonstrates how AI can improve banking through both direct interaction and intelligent service delivery. Blue and Ugi reduce navigation friction by helping customers express their intentions naturally and complete everyday financial tasks. Personalized recommendations make digital banking more relevant, while AI-supported employees deliver faster customer service and more contextual advice. AI-powered investment tools simplify complex financial analysis, and experiments in agent-initiated payments demonstrate potential future experiences where authorized financial transactions can be completed with fewer manual steps.
UX lesson: AI creates greater strategic value when it transforms banking from a collection of digital functions into a personalized, intent-driven financial experience. BBVA demonstrates how conversational interfaces, predictive personalization, intelligent financial decisions and agentic execution can work together to make banking more proactive and accessible. The critical design challenge is ensuring that this intelligence remains understandable, trustworthy and under the customer's control.
15. How bunq uses AI for conversational banking, personalized finance, customer support and fraud prevention
Financial AI Use Case: Conversational banking, personalized financial insights, generative AI customer support, fraud prevention, deepfake detection, AI-powered translation
Experience Impacted: CX – Banking Customer Experience; UX – Banking User Experience; EX – Employee Experience
AI Implementation: Netherlands-based neobank bunq expanded its generative AI financial assistant Finn, first launched in 2023, into an integrated platform for conversational banking, personalized money management and automated customer support. Finn enables customers to ask natural-language questions about spending, budgets, accounts, payments and savings, including transaction history from connected external bank accounts.
In December 2025, bunq launched an upgraded version of Finn offering more contextual conversations and assistance in 38 languages, supported by real-time AI speech-to-speech translation. By March 2026, Finn handled 97% of customer support interactions and fully resolved 84% without human intervention, up from 70% in August 2025. The assistant achieved a 90% user approval rating and resolved support requests in approximately 47 seconds, compared with an industry benchmark of one minute reported by bunq. The bank also reported 71% year-over-year growth in users actively interacting with Finn.
Beyond customer support, bunq expanded AI across its security operations, using artificial intelligence to improve fraud detection models, identify deepfake identity documents and strengthen customer verification. Its integration of AI-powered deepfake detection into KYC processes reportedly achieved over 90% detection accuracy, helping reduce manual reviews and strengthen digital onboarding security.
Financial customer experience impact: bunq demonstrates how conversational AI can simplify everyday financial management by replacing traditional navigation with contextual assistance. Customers can understand spending, monitor budgets and resolve banking issues through natural-language interactions, while multilingual AI support makes services more accessible. Intelligent fraud detection and identity verification further strengthen security, combining personalized assistance with safer digital banking experiences.
UX lesson: Conversational AI creates greater value when it connects financial understanding, customer support and security into one seamless banking experience. By combining intent-driven interactions, personalized insights and accessible human escalation, banks can reduce navigation friction and make financial services more intuitive, responsive and trustworthy.
16. How Mastercard uses AI for proactive fraud prevention, payment security and real-time risk detection
Financial AI Use Case: AI-powered fraud detection, payment security, predictive risk assessment, generative AI, transaction monitoring
Experience Impacted: CX – Financial Customer Experience; UX – Digital Payment Experience
AI Implementation: Global payments technology company Mastercard expanded its AI-powered fraud prevention capabilities, combining generative AI, graph analytics and predictive intelligence to identify compromised cards, suspicious transactions and emerging payment threats before fraud occurs.
Its generative AI-powered card security technology, introduced in 2024, doubled the detection rate of compromised cards, enabling banks to identify potentially stolen credentials earlier. Mastercard also scaled Decision Intelligence Pro, an AI-powered transaction risk assessment system that analyzes relationships between payment entities and generates risk scores in approximately 125 milliseconds, delivering an average 20% improvement in fraud detection.
In 2026, Mastercard further expanded proactive fraud prevention through Merchant Scam & Risk Indicator, which uses AI-driven intelligence to identify suspicious merchants before fraudulent activity escalates. In a pilot with a leading card issuer, the system detected approximately 80% of merchants identified as risky by the issuer, with some flagged up to 90 days before the issuer's initial escalation.
Financial customer experience impact: Mastercard's AI solutions help financial institutions detect fraud earlier while reducing unnecessary interruptions to legitimate payments. Real-time transaction risk assessment enables banks to make more informed authorization decisions, while proactive identification of compromised cards and suspicious merchants creates opportunities to prevent losses before customers are affected. These capabilities support safer payments, smoother checkout experiences and greater trust in digital financial services.
UX lesson: The most effective financial security experience prevents threats without creating unnecessary friction for legitimate customers. By combining predictive intelligence, real-time risk assessment and proactive fraud detection, financial institutions can move from reacting to fraudulent transactions toward anticipating and preventing risks throughout the payment journey.
17. How Nubank uses AI for personalized banking, conversational payments, credit decisions and customer service
Financial AI Use Case: AI-powered financial assistance, conversational payments, personalized banking, credit underwriting, customer service automation, fraud prevention, employee productivity
Experience Impacted: CX – Banking Customer Experience; UX – Digital Banking User Experience; EX – Employee Experience
AI Implementation: Latin American digital banking leader Nubank expanded artificial intelligence across its financial services ecosystem, moving beyond customer support toward AI-powered payments, credit decisions, personalized financial guidance and end-to-end banking automation.
In 2026, Nubank reported that its AI Private Banker capabilities were serving more than 15 million monthly active users, providing financial insights, payment assistance, credit guidance and debt resolution.
Nubank also introduced Pix with AI, transforming Brazil's instant payment experience through generative AI and conversational interactions. Customers can initiate transfers using natural-language text, voice messages or images through the Nubank app and WhatsApp, reducing the need to manually navigate traditional payment forms. Nubank reported that the solution reduces transaction completion time by up to 60%. Following its initial rollout in late 2024, Pix with AI surpassed 10 million monthly active users by early 2026, demonstrating the growing adoption of intent-driven payments. The experience combines conversational convenience with transaction limits, authentication and AI-powered fraud prevention to maintain security.
For lending, Nubank deployed NuFormer, its proprietary family of AI foundation models, across credit card decisioning in Brazil and Mexico and unsecured lending in Brazil. The technology enables real-time risk assessment and individualized loan pricing, with certain personal loan decisions completed in under one second.
Nubank also scaled its OpenAI-powered customer service assistant and employee copilots. Its AI support solutions handle millions of customer interactions, while AI agents managed more than 60% of customer support conversations in Brazil by the second quarter of 2026, with performance reported at or above human-agent quality benchmarks. Earlier deployments reduced chat response times by 70%, while internal enterprise search tools supported more than 5,000 employees. In 2026, Nubank also reported 50% year-over-year growth in engineering productivity and 90% faster testing cycles through AI-assisted workflows. Its AI initiatives additionally include intelligent fraud monitoring and a GPT-4o vision pilot supporting fraud investigation quality assurance.
Financial customer experience impact: Nubank demonstrates how AI can transform banking across the entire customer relationship rather than individual service interactions. Customers can make payments through natural language, receive contextual financial assistance, access more personalized credit decisions and resolve support inquiries faster. By integrating AI into customer-facing journeys and the operations behind them, Nubank creates opportunities for more accessible, proactive and individually relevant financial services.
UX lesson: AI creates greater strategic value when it transforms how customers manage money, make payments and access financial services—not simply how quickly banks answer questions. Nubank illustrates the transition toward AI-native banking, where conversational interactions, intelligent decision-making and personalized financial guidance work together to reduce friction across the customer journey.
18. How Visa uses AI for real-time fraud detection, transaction scoring and proactive payment security
Financial AI Use Case: AI-powered fraud detection, real-time transaction scoring, predictive risk assessment, scam prevention, payment security
Experience Impacted: CX – Financial Customer Experience; UX – Digital Payment Experience
AI Implementation: Global payments technology company Visa expanded its AI-powered fraud prevention capabilities, combining machine learning, generative AI, behavioral analytics and real-time transaction scoring to detect suspicious payments and prevent financial crime. Its AI-powered security systems help prevent more than $40 billion in fraud annually, while solutions such as Visa Advanced Authorization and Account Attack Intelligence identify transaction risks and emerging fraud patterns across the payment ecosystem.
In 2025–2026, Visa accelerated proactive scam prevention through its Visa Scam Disruption initiative, which uses AI-enabled intelligence, network analytics and human investigations to identify and dismantle fraudulent merchant networks. By October 2026, the initiative had identified more than $2.6 billion in attempted scam activity globally, including an additional $1.6 billion since October 2025. In September 2026, Visa also enhanced A2A Protect with real-time fraud scoring, reporting that the solution can reduce over 50% more fraud and over 40% of unnecessary fraud alerts in evaluated implementations.
Financial customer experience impact: Visa's AI capabilities help protect customers by detecting suspicious activity before fraudulent payments are completed while reducing unnecessary interruptions to legitimate transactions. More accurate risk scoring enables financial institutions to balance security with payment convenience, while proactive scam detection helps identify threats that customers may not recognize themselves. Together, these innovations support safer, more seamless and more trustworthy digital payment experiences.
UX lesson: The most effective AI-powered payment security protects customers without making security an obstacle to legitimate financial activity. By combining predictive fraud detection, contextual risk assessment and proactive scam prevention, financial institutions can strengthen customer trust while minimizing unnecessary payment friction.
19. How First Horizon Bank uses AI for fraud prevention, personalized banking and customer relationship management
Financial AI Use Case: AI fraud detection, cybersecurity, predictive marketing, customer segmentation, personalized banking, lead scoring, AI search optimization, customer relationship management, generative AI employee assistance
AI Implementation: US regional financial institution First Horizon Bank expanded AI across financial security, marketing and customer relationship management. Its implementation includes machine-learning fraud detection, AI-driven cybersecurity automation, predictive customer analytics and internal generative AI tools.
In fraud prevention and cybersecurity, First Horizon uses machine-learning-powered identity and access controls to identify suspicious behavior and reduce account takeover risks. AI-driven security automation helps employees investigate threats and respond to emerging fraud patterns.
In predictive marketing and customer personalization, First Horizon developed FirstHorizon360 (FH360), connecting customer data across digital channels, CRM, marketing, sales and banking services. Through its partnership with Dun & Bradstreet, the bank uses enriched customer data, predictive segmentation and intent-based modeling to identify potential customer needs, deliver more relevant communications and prioritize commercial banking opportunities. Its D&B Rev.Up ABX platform combines account characteristics and buying-intent signals to support targeted campaigns and personalized customer journeys.
In marketing automation and lead generation, First Horizon connects digital advertising, social media, landing pages and CRM to identify prospective customers and personalize follow-up interactions. Engagement signals and lead scoring help determine when prospects are ready for relationship-manager outreach, while campaign analytics support continuous optimization from initial awareness to conversion and retention.
In AI-powered digital marketing and brand discovery, First Horizon is adapting its digital presence for AI-driven search and customer discovery. Working with Yext and Hearsay, the bank connects localized marketing, banker visibility, compliant social media and digital content management. In 2026, First Horizon also redesigned its website around customer needs and clearer financial terminology to improve discoverability through traditional and AI-powered search.
In generative AI and employee productivity, First Horizon introduced internal AI knowledge-sharing tools and established an AI Council to evaluate applications across banking operations. The bank is also exploring AI-supported underwriting and more efficient customer relationship workflows.
Financial customer experience impact: First Horizon demonstrates how AI and predictive analytics can strengthen financial relationships beyond customer service chatbots. Intelligent segmentation and personalized marketing help customers discover more relevant financial products, while connected customer data supports more consistent interactions across digital and human channels. Proactive fraud detection strengthens security, and AI-supported employees can deliver more informed assistance.
UX lesson: AI-driven personalization creates strategic value when marketing intelligence becomes customer experience intelligence. First Horizon illustrates how banks can connect predictive insights, digital discovery, personalized communications and relationship management to deliver more relevant financial experiences throughout the customer lifecycle.
20. How Commonwealth Bank of Australia uses AI for fraud prevention, personalized banking, customer service and agentic banking
Financial AI Use Case: AI fraud detection, agentic AI, personalized banking, conversational financial assistance, customer service automation, employee productivity
Experience Impacted: CX – Banking Customer Experience; UX – Digital Banking User Experience; EX – Employee Experience
AI Implementation: Australia's largest bank, Commonwealth Bank of Australia (CBA), expanded AI across its banking ecosystem, integrating predictive intelligence, generative AI and agentic automation into fraud prevention, personalized financial management, customer service and internal operations.
In 2026, CBA deployed an agentic AI fraud detection system that analyzes more than 80 million signals daily, identifying emerging threats and proposing new detection rules under human supervision. Its wider AI-powered security systems generate over 40,000 proactive customer alerts per day, contributing to a more than 20% reduction in customer fraud losses in the first half of FY2026 compared with the same period a year earlier.
Beyond security, CBA expanded its AI-powered CommBank Companion, a conversational banking experience designed to provide personalized financial insights and assistance. By June 2026, the small-business version was serving 100,000 customers, while a retail banking version was being piloted. Its machine-learning Customer Engagement Engine also powers personalized recommendations and Benefits Finder, helping customers discover relevant financial support and government rebates.
CBA also scaled AI customer service and employee assistance. By December 2025, its virtual assistant Ceba resolved 85% of customer interactions through unassisted messaging channels, while the internal generative AI solution Compass AI answered more than 500,000 employee questions, retrieving business banking knowledge over three times faster than traditional methods. By June 2026, approximately 80% of CBA employees were actively engaging with enterprise AI platforms.
Financial customer experience impact: CBA demonstrates how AI can improve financial experiences across security, service, personalization and business banking. Proactive fraud detection protects customers before losses occur, conversational banking simplifies access to financial information, and automated customer support reduces dependence on traditional service channels. AI-assisted employees and personalized insights further support faster, more relevant banking interactions.
UX lesson: AI creates greater value when it connects proactive protection, personalized financial guidance and intelligent service across the entire banking experience. Commonwealth Bank illustrates how predictive and agentic AI can help financial institutions anticipate customer needs, reduce friction and improve service efficiency while preserving human oversight, transparency and trust.
21. How Capital One uses AI for conversational banking, personalized finance, fraud prevention and agentic car buying
Financial AI Use Case: Conversational banking, proactive financial monitoring, fraud detection, personalized digital experiences, agentic AI, customer service automation, employee productivity
Experience Impacted: CX – Banking Customer Experience; UX – Digital Banking User Experience; EX – Employee Experience
AI Implementation: US financial institution Capital One expanded artificial intelligence across its banking and financial services ecosystem, combining conversational assistance, proactive financial monitoring, personalized digital experiences and agentic AI.
Its AI-powered virtual assistant, Eno, helps customers manage accounts through the mobile app, online banking and text messages. Eno answers account-related questions, monitors transactions, identifies unusual charges and duplicate payments, and provides proactive notifications about recurring subscriptions and expiring free trials. It also supports safer online shopping through virtual card numbers, helping customers protect their actual card credentials.
In March 2025, Capital One introduced Chat Concierge, a proprietary multi-agentic AI assistant designed to simplify car buying. Built on Meta's Llama model and Capital One's proprietary data, the assistant can understand customer preferences, compare vehicles, recommend options and schedule dealership appointments. Unlike traditional chatbots that primarily provide information, Chat Concierge coordinates specialized AI agents to plan, validate and execute selected tasks while checking for errors and compliance with business rules.
Capital One also expanded AI-powered personalization across its digital channels, using a transformer-based recommendation system to deliver more relevant experiences based on customer context and behavior. Internally, its generative AI knowledge-retrieval assistant supports thousands of customer service employees by helping them find information and answer customer questions more efficiently. By 2026, the tool had been used more than 10,000 times, while a separate AI-agent initiative reduced a complex cloud infrastructure analysis project from an estimated 6–9 months to 10 days.
Financial customer experience impact: Capital One demonstrates how AI can connect everyday banking assistance, proactive financial insights, transaction security and more complex financial journeys. Eno helps customers monitor finances and recognize potential problems, while Chat Concierge simplifies vehicle discovery and dealership interactions. Personalized recommendations and AI-assisted employees create opportunities for more relevant services and faster problem resolution across digital and human channels.
UX lesson: AI creates greater value when it anticipates customer needs and helps complete meaningful financial tasks, rather than simply responding to questions. Capital One's evolution from Eno to agentic AI demonstrates how financial institutions can connect proactive assistance, personalization and intelligent task execution to reduce friction throughout the customer journey.
Bonus AI Banking Case Studies
How Klarna uses AI for customer support, personalized shopping, credit risk assessment and agentic commerce
Financial AI Use Case: Generative AI customer support, personalized shopping, conversational commerce, agentic payments, AI credit underwriting, employee productivity
Experience Impacted: CX – Financial Customer Experience; UX – Shopping and Payment Experience; EX – Employee Experience
AI Implementation: Swedish fintech Klarna expanded artificial intelligence across its payments and shopping ecosystem, combining generative AI customer service, intelligent product discovery, machine learning-based credit assessment and internal workflow automation.
Its OpenAI-powered customer service assistant, launched in 2024, handled 80% of customer service chats in 2025, totaling 31 million conversations since launch. Klarna estimates the assistant performed the equivalent work of more than 850 full-time agents, generating approximately $59 million in customer support cost savings in 2025. AI-handled conversations maintained customer satisfaction levels comparable to human agents, while earlier implementation results showed average resolution times of two minutes versus 12 minutes for human-assisted chats.
However, Klarna's rapid AI adoption also exposed the limitations of prioritizing automation and cost reduction over service quality. In May 2025, CEO Sebastian Siemiatkowski acknowledged that the company's aggressive cost-cutting approach had compromised customer service quality and announced renewed investment in human support. Klarna began recruiting customer service agents to ensure customers could reach a person when needed. Despite this strategic adjustment, its AI assistant continued to handle 80% of customer service chats in 2025, demonstrating that scalable automation and accessible human assistance can coexist.
In 2025–2026, Klarna expanded into AI-powered shopping and agentic commerce. Its Agentic Product Protocol, launched in December 2025, makes more than 100 million products and 400 million prices accessible to AI shopping agents. In May 2026, Klarna introduced its Shopping Search app in ChatGPT, allowing customers to discover and compare products through natural-language conversations using live prices and availability. It also announced integrations designed to bring flexible payment options into AI-assisted shopping and checkout experiences.
Beyond customer-facing AI, Klarna uses machine learning for real-time credit underwriting, assessing payment risk and supporting financing decisions. Internally, AI coding assistants, automated document analysis, marketing content generation and its Kiki knowledge assistant help employees work more efficiently. By 2025, Klarna reported approximately $1.24 million in annual revenue per employee, compared with $344,000 in 2022, reflecting productivity gains alongside broader operational restructuring and growth.
Financial customer experience impact: Klarna demonstrates both the opportunities and limitations of AI-driven financial services. Its AI assistant significantly reduced resolution times and support costs, while AI-powered shopping, personalization and credit assessment simplified other parts of the customer journey. However, Klarna's subsequent investment in human customer service highlighted the importance of service quality, empathy and appropriate escalation for complex or sensitive situations. Its evolving approach illustrates how financial institutions can combine the efficiency of AI with human judgment to deliver more reliable, personalized and trustworthy customer experiences.
UX lesson: AI transformation succeeds when efficiency and automation improve customer experience without sacrificing human judgment, empathy or trust. Klarna demonstrates that replacing human interactions with AI is not the same as redesigning the financial experience. Banks must define where AI creates value, where human assistance remains essential and how customers move seamlessly between them.
How Upstart uses AI for credit underwriting, automated lending and personalized loan decisions
Financial AI Use Case: AI-powered credit underwriting, automated loan approvals, predictive risk assessment, personalized loan pricing, fraud detection
Experience Impacted: CX – Financial Customer Experience; UX – Digital Lending Experience
AI Implementation: US-based fintech Upstart expanded its AI-powered lending marketplace, enabling more than 100 partner banks and credit unions to assess creditworthiness, automate lending decisions and offer personalized financing. Its machine learning models evaluate thousands of variables beyond traditional credit scores to predict default risk, verify income and identity, detect fraud and determine risk-based loan pricing.
According to Upstart's 2025 Access to Credit Report, its AI underwriting model demonstrated the potential to approve 41% more applicants with 33% lower average APRs compared with a traditional underwriting model. The comparison used 2025 applicant data and a hypothetical traditional model. In the second quarter of 2026, 91% of loans originated through Upstart were fully automated, while the platform facilitated approximately 558,000 originations worth $4.23 billion, representing 50% year-over-year growth in origination volume.
In 2025–2026, Upstart also expanded AI-powered lending beyond personal loans into automotive financing, home equity lines of credit (HELOCs), small-dollar loans and Cash Line, a revolving credit product launched in February 2026. Its proprietary Upstart Macro Index (UMI) helps calibrate underwriting models to changing economic conditions, while continuous model improvements support more accurate risk assessment and automated credit decisions.
Financial customer experience impact: Upstart demonstrates how AI can improve financial access by enabling faster credit assessments, more personalized loan pricing and streamlined digital applications. Automated underwriting reduces manual documentation and waiting times, while more detailed risk analysis can help lenders identify creditworthy applicants who might be overlooked by conventional scoring approaches. By simplifying decisions across multiple lending products, Upstart creates opportunities for faster, more accessible and more relevant borrowing experiences.
UX lesson: AI can transform financial customer experience by redesigning the decisions behind the interface, not simply improving the interface itself. Intelligent underwriting and automated lending can remove friction, expand access to credit and personalize financial products, provided decisions remain transparent, explainable and appropriately governed.
How Lunar uses AI for voice banking, personalized financial management, customer support and agentic banking
Financial AI Use Case: Generative AI voice assistant, conversational banking, personalized financial insights, customer support automation, employee productivity, agentic banking
Experience Impacted: CX – Banking Customer Experience; UX – Banking User Experience; EX – Employee Experience
AI Implementation: Danish digital bank Lunar expanded AI across customer experience, financial management and internal operations. Its GPT-powered in-app financial assistant helps customers analyze spending, identify recurring expenses, plan savings goals and receive contextual money-management insights. In October 2024, Lunar also launched a GPT-4o-powered, voice-native banking assistant capable of natural conversations, interruptions and follow-up questions, offering 24/7 support without traditional call queues.
In 2025, Lunar achieved measurable results with its separate in-app AI Support service. By August, the assistant was independently resolving 85% of incoming customer cases, with 65% of AI-handled cases rated 4 or 5 out of 5. Lunar emphasized continuous monitoring and improvement by its Customer Experience team rather than relying solely on automated responses.
In June 2026, Lunar reported that AI-assisted development had helped its engineering teams double productivity compared with the end of 2025. The bank also outlined its vision for agentic and invisible banking, in which authorized AI agents could interact directly with regulated banking infrastructure to manage financial tasks, initiate payments and support customers beyond the traditional banking app. These agentic capabilities remain a strategic development direction rather than a fully deployed customer service with verified results.
Financial customer experience impact: Lunar demonstrates how AI can improve banking accessibility, financial understanding and service efficiency. Voice-native interactions offer an alternative to complex app navigation, personalized insights help customers understand spending and savings, and AI-powered customer support enables faster independent resolution of common problems. Its emerging agentic banking strategy could further reduce friction by embedding financial services into customers' everyday digital activities.
UX lesson: AI creates greater value when banking adapts to customers' intentions and preferred ways of interacting, rather than requiring customers to adapt to banking interfaces. Combining voice, conversational assistance, personalized financial intelligence and controlled automation can make financial services more accessible and intuitive—but trust, explicit authorization and human oversight remain essential as AI moves from providing information to executing financial actions.
What Do Real-World AI Banking Case Studies Reveal
Our analysis of 24 financial institutions and fintechs, covering nearly 200 AI use-case examples, reveals that AI is transforming banking across three dimensions: operational efficiency, personalized financial experiences and intelligent execution.
The most widespread applications focus on employee productivity, financial personalization, fraud prevention and customer service automation. These improve existing banking processes and help institutions operate more efficiently.
However, some of the most transformative implementations are emerging in automated lending, conversational payments, predictive financial guidance and agentic banking. They go beyond optimizing existing interactions to change how customers access financial services, make decisions and complete tasks.
Biggest improvements in speed and efficiency
| Organization | Reported AI result | What it measures |
|---|---|---|
| RBC | Up to 95% faster | Selected investment research drafts |
| NatWest | 15 minutes → under 60 seconds | Selected business onboarding checks |
| BNY | 80% faster | AI-assisted transaction inquiries |
| JPMorganChase | 80% less time | Selected investment research workflows using SpectrumIQ |
| Lloyds | Several hours → ~5 minutes | Selected commercial real-estate document reviews |
| Nubank | Up to 60% faster | Pix payment completion |
| DBS | 60% faster | Selected trade finance condition processing |
| Bank of America | Up to 4 hours potentially saved | Advisor meeting preparation and documentation |
Most significant customer and financial outcomes
- +40% | RBC—Credit access | More credit-limit increases for customers with under two years of credit history, enabling nearly CAD 300 million in additional credit.
- 91% | Upstart—Automated lending | Share of originated loans processed fully automatically in Q2 2026, using Upstart's defined automation measure.
- +25% | JPMorganChase—Engagement | Higher engagement with its AI-personalized mobile banking home screen.
- +17% | DBS Joy—Satisfaction | Reported increase in customer satisfaction for its Singapore corporate banking assistant in H1 2026.
Largest reported economic value
- DBS: ~SGD 1 billion in 2025—Bank-reported economic value from data analytics and AI
- Klarna: ~$59 million in 2025—Estimated customer support cost savings
- Lloyds: ~£50 million in 2025—Reported generative AI economic value
- RBC: CAD 9.6 billion cumulatively—Customer funds set aside using NOMI Find & Save since 2017; not bank profit
Most significant fraud prevention improvements
- HSBC: 2–4× more suspicious activity identified, with approximately 60% fewer false-positive alerts versus its former AML system
- Mastercard: Average 20% improvement in fraud detection using Decision Intelligence Pro
- Visa: A2A Protect evaluation reported over 50% more fraud detected and over 40% fewer unnecessary alerts
- BNY: NAV accounting false-positive alerts reduced from 90% to below 20% in a selected fund-accounting application
- CBA: More than 80 million fraud signals analyzed daily
What Are the Most Unusual AI Implementations
These are the applications that go furthest beyond generic chatbots, document summarization and conventional fraud detection.
Nubank — Paying by speaking, typing or sending an image
Pix with AI lets customers express payment intentions through natural language instead of completing a traditional payment form.
Reported result: up to 60% less transaction time.
BNY — Digital employees repairing failed payments
Specialized agents perform defined institutional operations, including payment repair, reconciliations and settlement inquiry handling.
Reported result: more than 10% of global payment-repair activities handled by AI.
Royal Bank of Canada — Reinforcement learning for electronic trading
RBC's Aiden adapts trading execution strategies to changing market conditions, applying AI to financial decisions that customers rarely see directly.
Unusual because AI is embedded in trading execution, not merely research support.
BBVA — A payment initiated by an AI agent
BBVA and Visa demonstrated an AI agent initiating a card transaction using real payment credentials and security controls.
Status: controlled demonstration, not a broadly deployed autonomous payment product.
Commonwealth Bank of Australia — AI agents proposing new fraud detection rules
Instead of only scoring transactions, an agentic system analyzes emerging threats and proposes changes to detection rules under human supervision.
Scale: more than 80 million fraud signals analyzed daily.
Capital One — AI coordinating the car-buying journey
Chat Concierge helps discover and compare vehicles and schedule dealership appointments, extending financial AI into the broader purchase experience.
Unusual because it coordinates decisions and actions beyond the bank's core interface.
HSBC — Connecting customers' own AI agents to banking data
HSBCnio supports permissioned connections between business banking information and customers' AI-enabled systems through standardized interfaces.
Unusual because the interaction may take place outside the bank's app; it does not imply unrestricted autonomous payments.
What Does This Mean for the Future of Financial Experience
These examples demonstrate that the greatest opportunity is not simply implementing more AI applications.
It is redesigning financial experiences around what AI makes possible—so banking becomes more intuitive, proactive, accessible and trustworthy.
For financial institutions, the competitive question is shifting from “Where can we implement AI?” to “How should banking work differently because AI exists?”
Stage 1: Optimize
AI reduces manual effort, improves fraud detection and speeds up internal processes.
Examples: Goldman Sachs, HSBC, BNY
Stage 2: Personalize
AI understands financial context, anticipates needs and delivers relevant guidance.
Examples: RBC NOMI, DBS Intelligent Banking, Morgan Stanley Next Best Action
Stage 3: Transform
AI changes how customers express intent and how financial services are delivered.
Examples: Nubank Pix with AI, NatWest onboarding agents, DBS Joy, BNY digital employees
Five strategic conclusions
- Employee productivity dominates mature deployments, but does not automatically produce customer differentiation. Saving staff time creates capacity; banks still need to redesign journeys to turn that capacity into better service.
- The most significant speed improvements come from removing steps. Nubank, NatWest and BNY illustrate how AI can eliminate parts of a process or coordinate tasks behind the scenes.
- Personalization is moving from marketing toward financial decision support. RBC's credit assessment and NOMI, DBS's financial nudges, and Morgan Stanley's advisor intelligence are more meaningful than simply personalizing promotional content.
- AI trust and governance will increasingly be part of the customer experience itself. Customers need understandable recommendations, permissions, confirmations, explanations and recovery mechanisms when AI influences financial decisions or takes actions.
- The strongest long-term differentiation may come from invisible AI. Customers might never see the fraud models, credit engines or institutional agents delivering the outcome. They experience their consequences: less friction, faster access, more relevant advice and more reliable service.
Why Is AI Adoption Accelerating in Banking
AI adoption in banking is accelerating because financial institutions can apply artificial intelligence across high-volume operations, risk management and customer-facing services. Banks manage large volumes of transactions, financial data and customer interactions, creating opportunities to improve efficiency, detect risks and provide more relevant financial assistance.
According to McKinsey's 2026 Global AI Survey, nearly 90% of surveyed organizations use AI in at least one business function. More importantly, 44% report scaling AI across their enterprises, compared with 38% in 2025. This demonstrates that organizations are moving beyond experimentation toward broader implementation.
A McKinsey survey indicates that AI adoption is now mainstream across industries. Overall, about 78% of organizations worldwide report using some form of AI in at least one business function in 2024, a huge increase from just 20% in 2017. Within this landscape, banking/financial services is a leading adopter of AI.
IDC's 2026 AI Spending Guide estimates approximately $400 billion in enterprise AI platform and services spending in 2026, with the market continuing to expand toward 2029. IDC estimates the banking industry will invest about $31.3 billion in financial AI, making it the second-largest industry for AI spending (after software/IT services at $33 billion and ahead of retail at approximately $25 billion). Together, software, banking and retail account for 38% of the global AI spend.
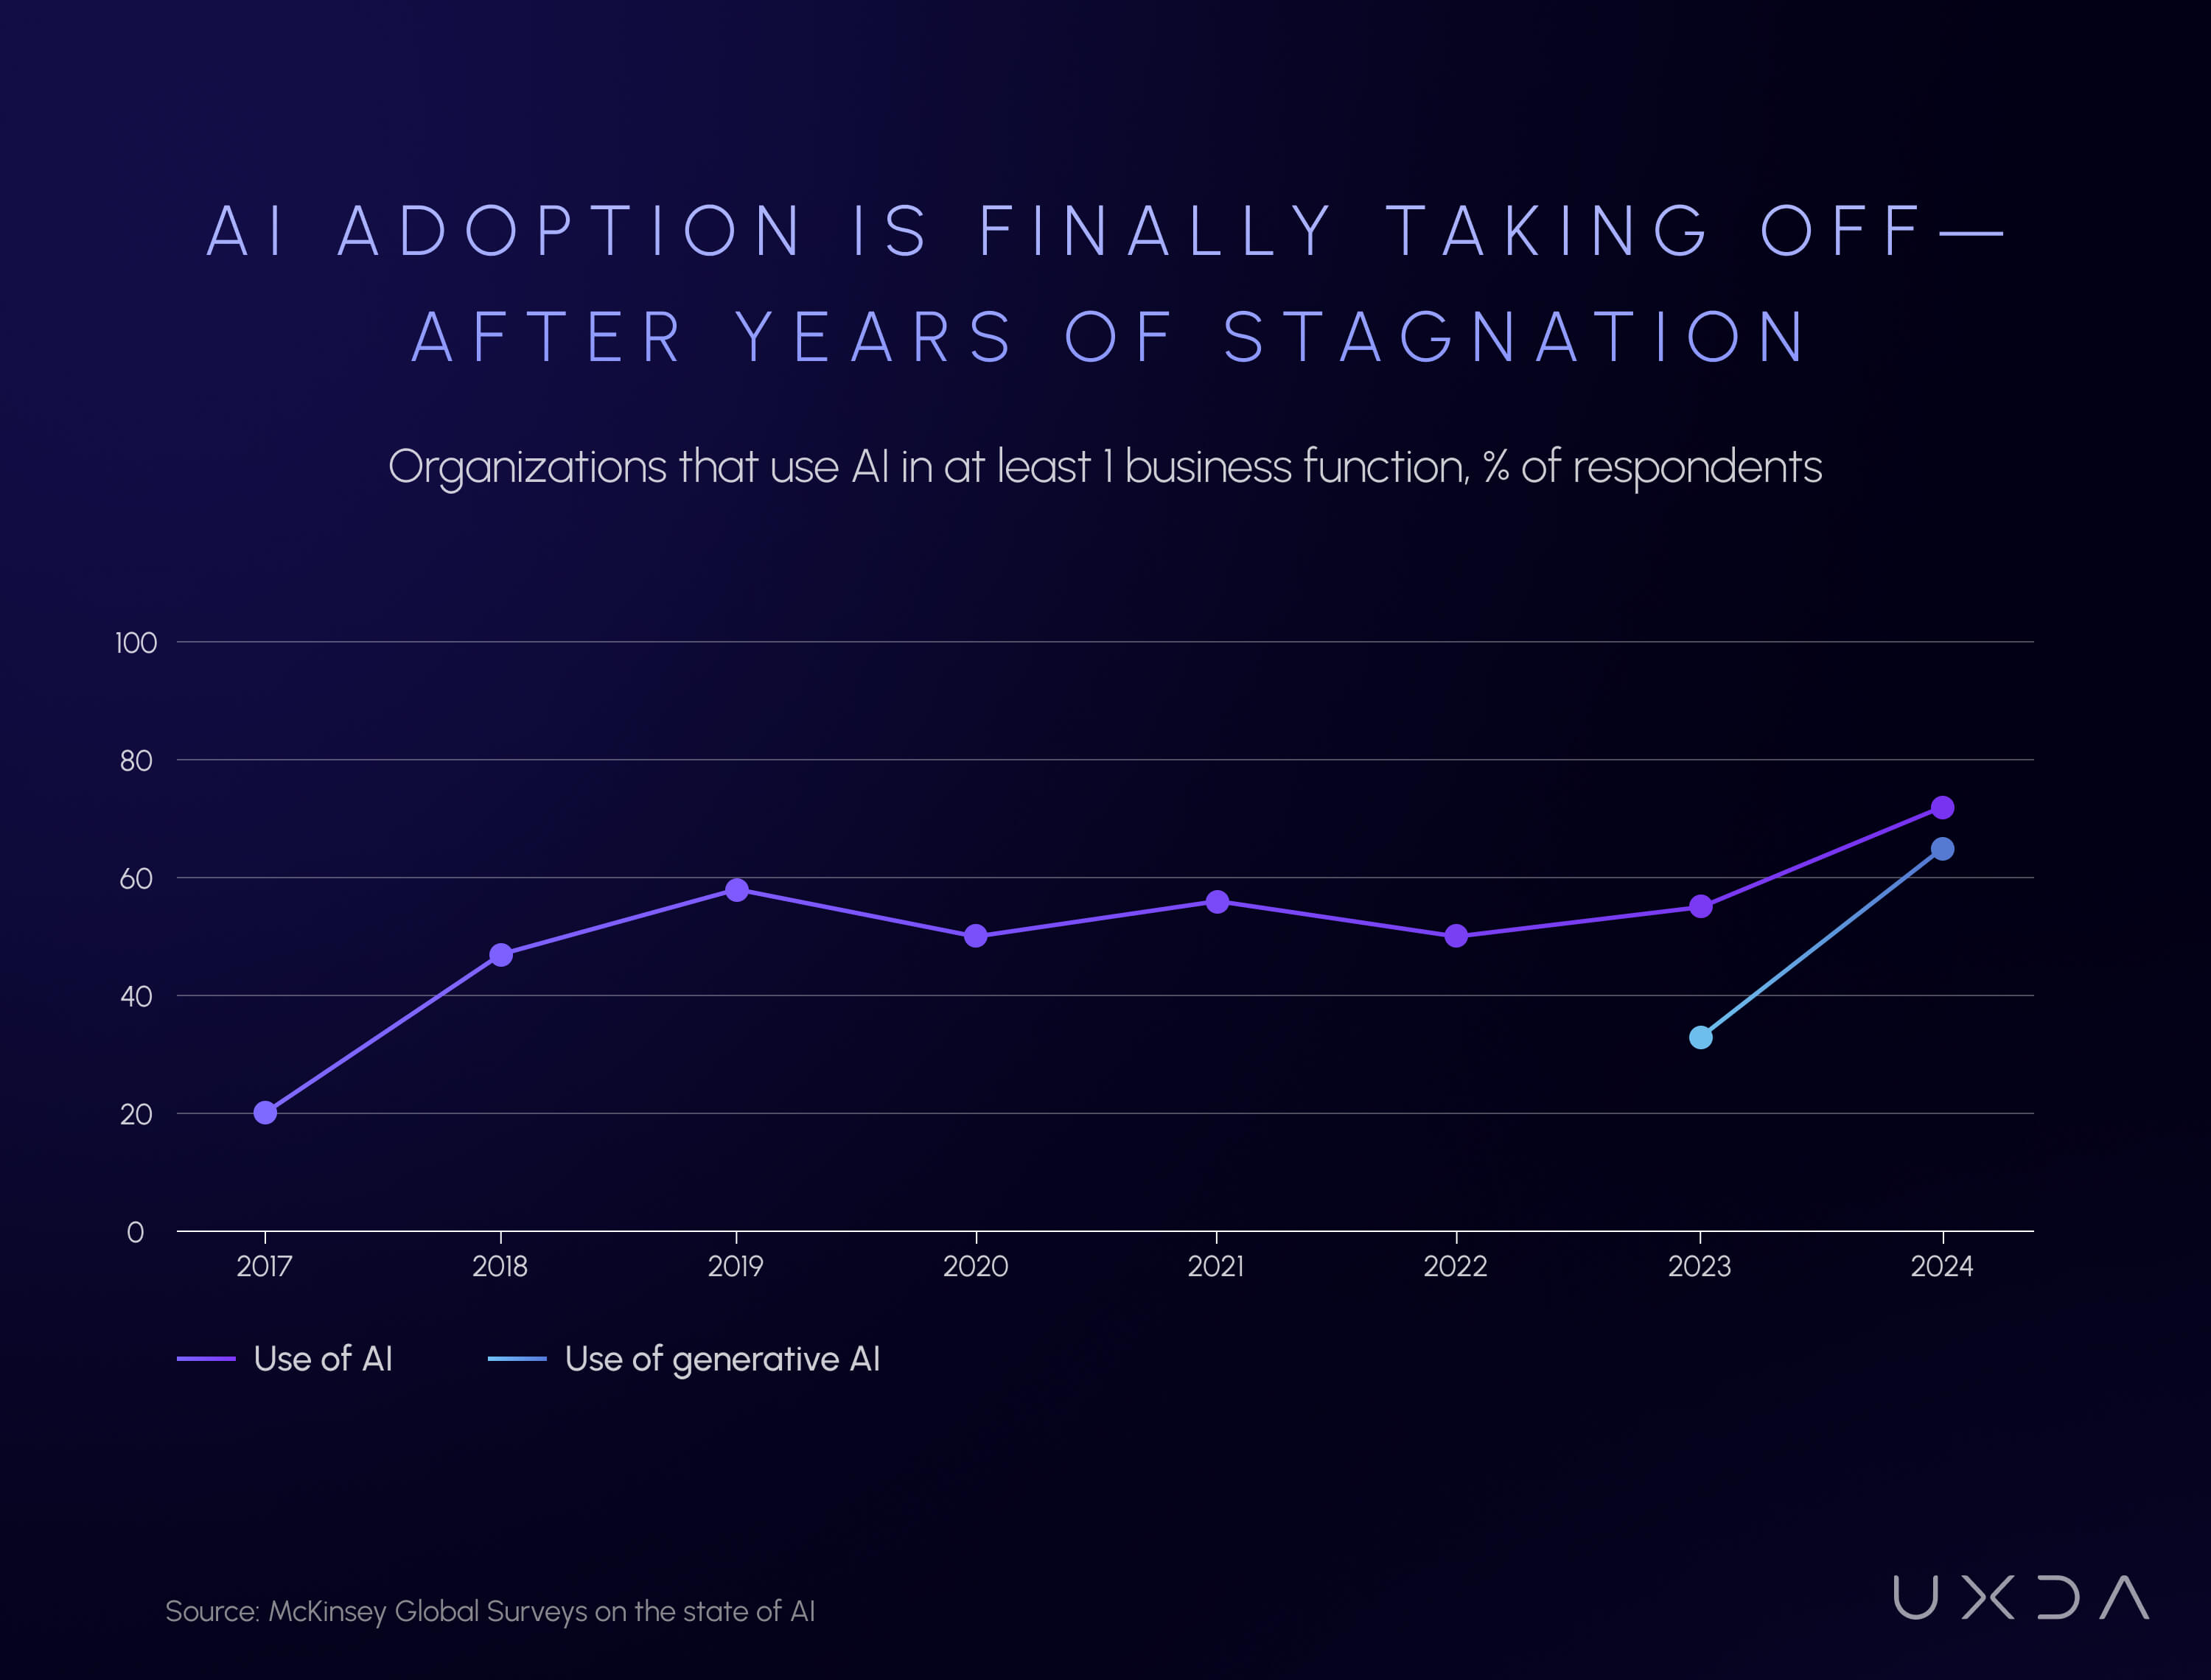 Source: McKinsey Global Surveys on the state of AI
Banking is among the industries investing heavily in this transformation. According to Boston Consulting Group's June 2026 Global Financial Institutions Report, financial institutions plan to invest approximately 2% of revenue in AI during 2026, with only the technology industry investing more relative to revenue.
The recent years saw an explosion of interest in generative AI (GenAI)—AI that can produce human-like text, code, images, etc. And banking has been at the forefront of deploying generative AI compared to other sectors.
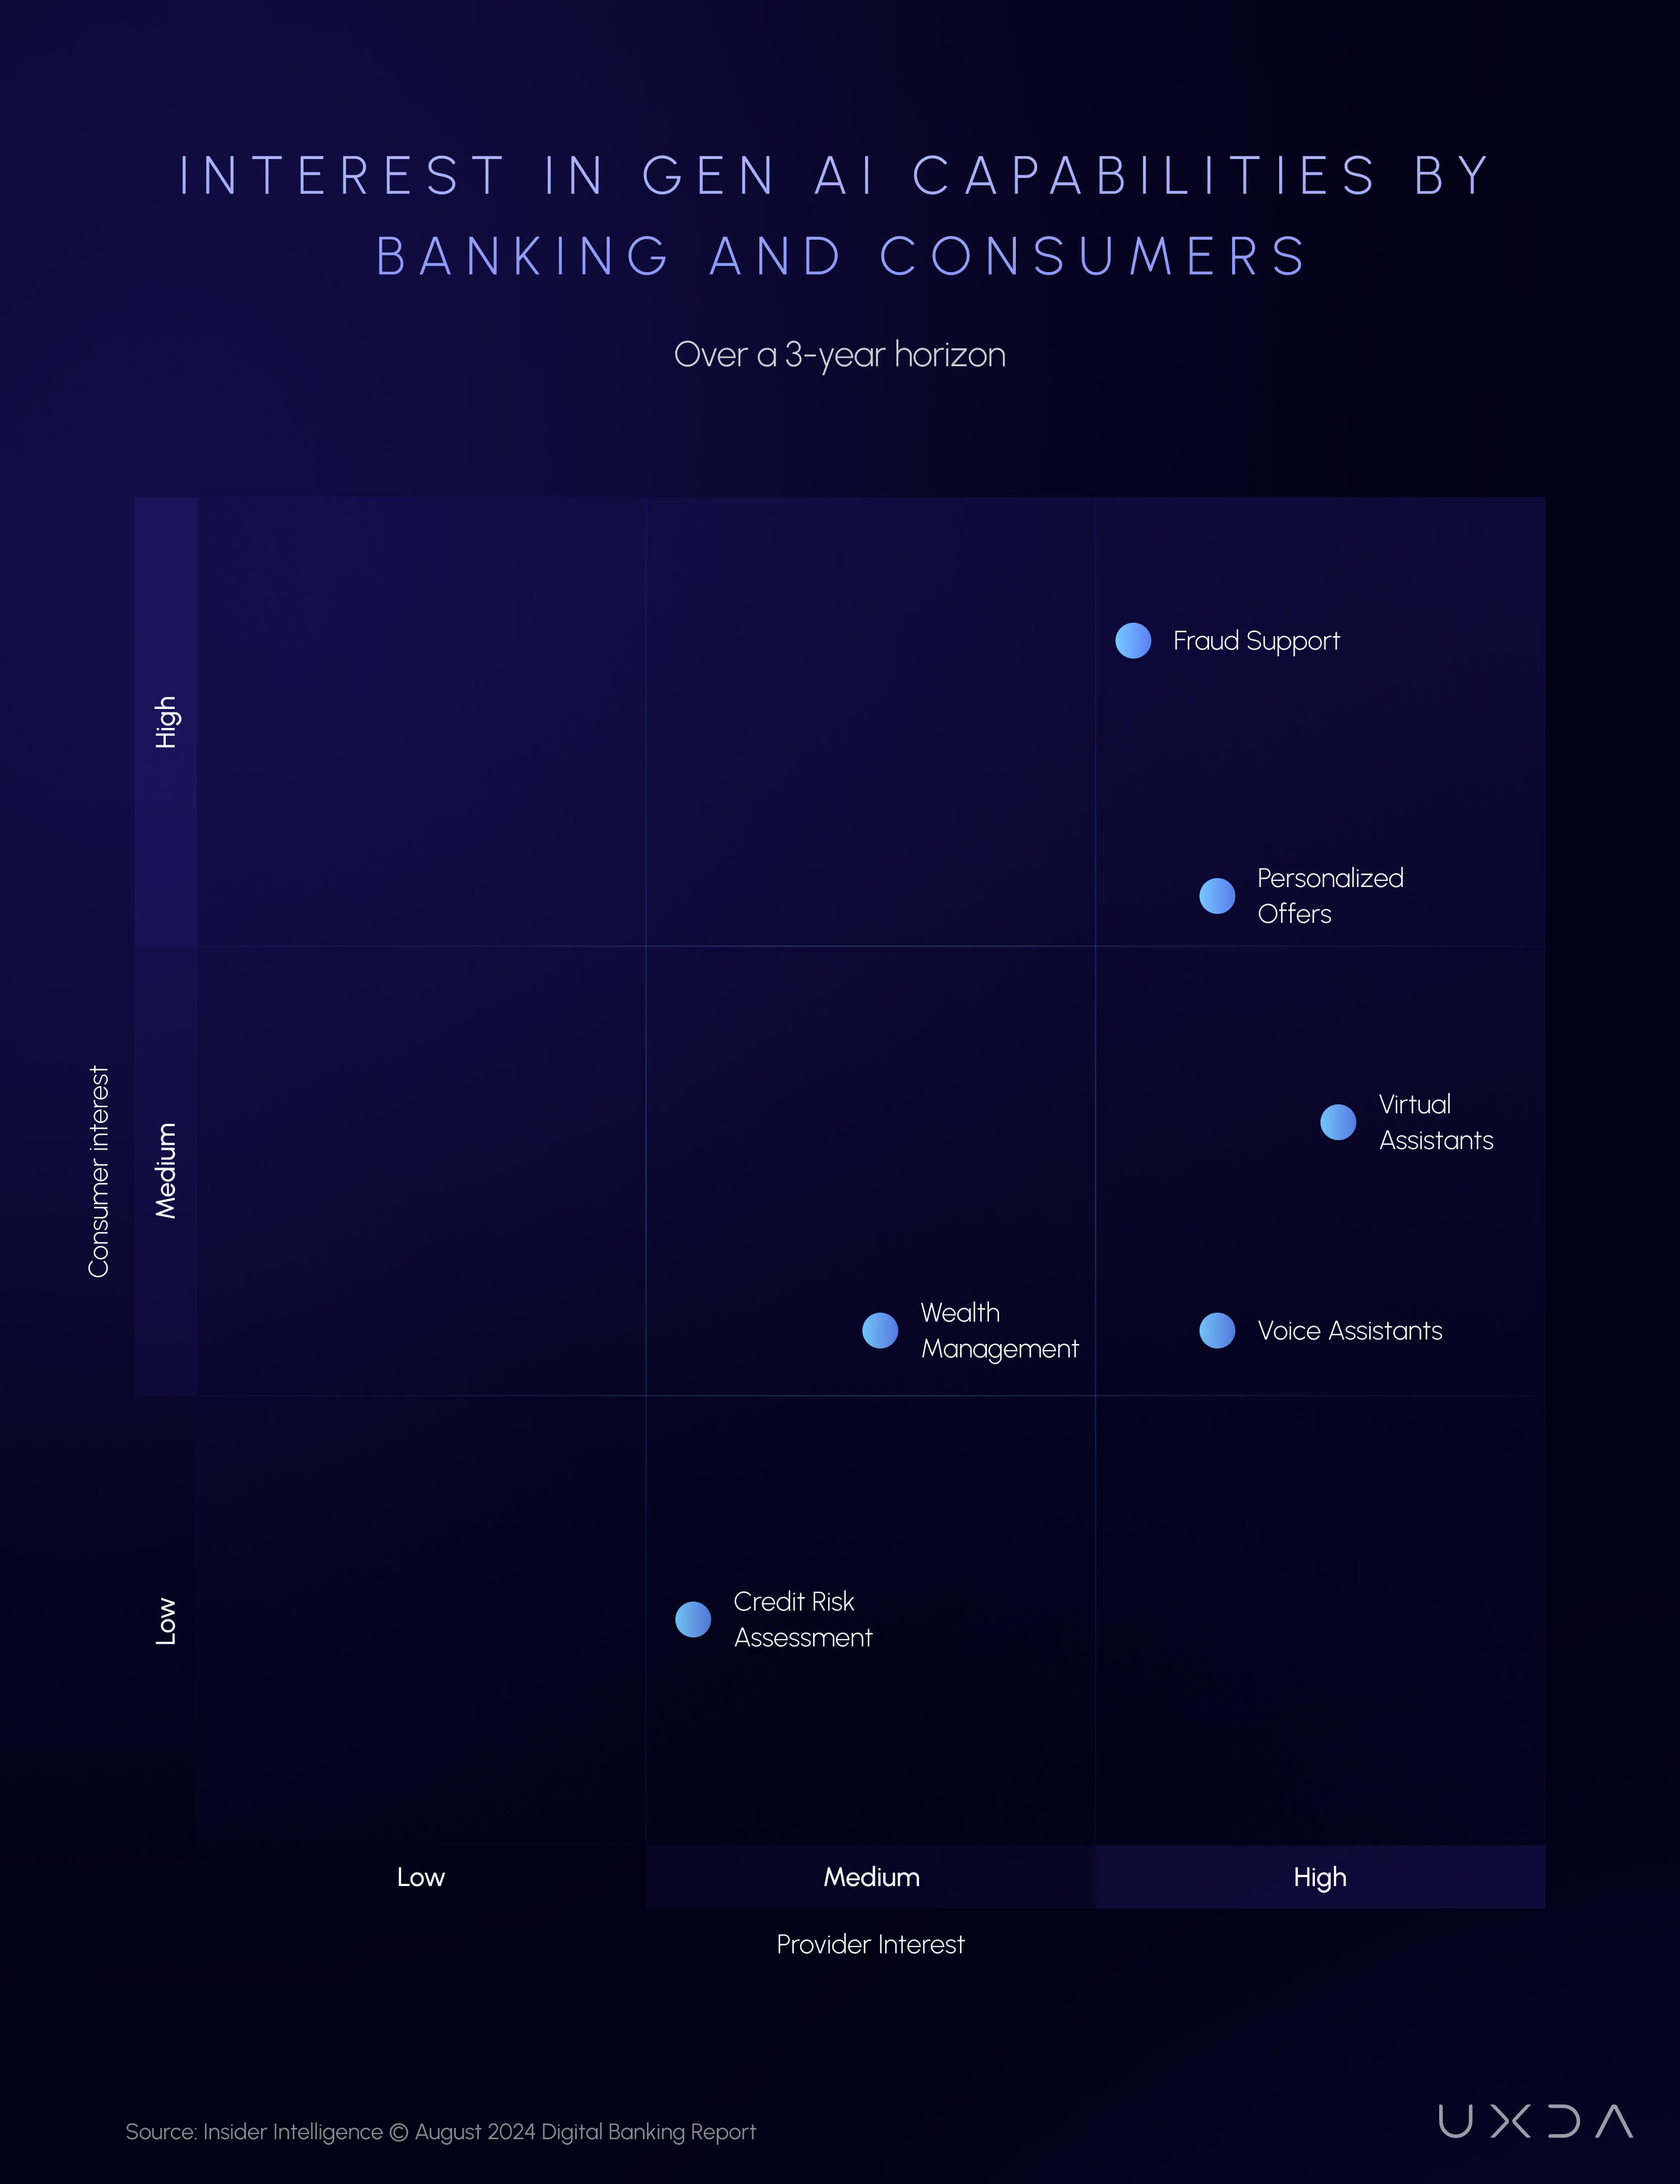 Source: Insider Intelligence © August 2024 Digital Banking Report
The significance for digital banking is that AI is moving from isolated operational applications toward intelligent, personalized and increasingly agentic financial experiences. Banks are expanding AI beyond detecting problems or generating information toward anticipating customer needs, supporting financial decisions and completing selected tasks.
However, AI investment and adoption rates do not necessarily indicate successful transformation. The more meaningful question is whether implementation improves measurable customer outcomes, operational performance, risk management or competitive differentiation.
How Is Generative AI Changing Banking
Generative AI is expanding banking AI beyond prediction and automation into conversational interfaces, personalized financial guidance, employee assistance and agentic workflows. Unlike traditional AI systems that primarily classify, forecast or identify patterns, generative AI can interpret natural language, synthesize complex financial information and support multi-step interactions.
According to McKinsey's 2025 Global AI Survey, 79% of surveyed organizations reported regularly using generative AI in at least one business function, up from 71% in 2024.
The next stage is agentic AI: systems that can plan, coordinate and execute defined tasks across workflows. McKinsey's 2026 research found that 40% of surveyed organizations with more than $1 billion in annual revenue were scaling AI agents, up from 27% the previous year.
Financial institutions are increasingly exploring these capabilities across customer service, financial advisory, transaction processing, credit decisions and operational workflows.
For example, Morgan Stanley uses generative AI to help financial advisors research investments and prepare client interactions. DBS has introduced agentic capabilities into its corporate banking assistant, while BNY uses specialized AI agents for selected onboarding, payment-repair and settlement workflows.
Source: Insider Intelligence © August 2024 Digital Banking Report
Almost every bank is at least planning for GenAI. A global survey found that 98% of banking leaders either use generative AI now (60%) or plan to within two years (38%). This virtually unanimous interest is unique—other sectors showed lower current usage and more hesitancy. Banks also back up these plans with resources: 90% of banks surveyed have a dedicated GenAI budget for the coming year, indicating significant investment in AI talent and tools.
The strategic shift is from AI that answers questions to AI that helps deliver financial outcomes. For banks, this creates opportunities to simplify complex journeys—but also introduces new requirements for permissions, explainability, security and human oversight.
Why Is Banking One of the Leading Industries for AI Adoption
Banking is among the leading industries for AI implementation because financial services combine extensive digital data, repetitive processes, complex decisions and strong demand for security, efficiency and personalization.
Banking (often grouped with finance/insurance) figures prominently among the industries with the highest AI adoption. Research by IBM found that about 50% of enterprises in financial services have actively deployed AI, the highest of any sector. By comparison, the next-highest was telecommunications, at 37%, with other sectors generally lower.
The European Central Bank reported in March 2026 that nearly 90% of significant euro-area banks already use AI technologies. The most common applications include fraud and cybercrime detection, used by more than half of surveyed banks, followed by marketing at approximately 50%, chatbots at 40% and credit scoring at 30%.
Research from Boston Consulting Group likewise shows 35% of banking companies qualify as financial AI “leaders” (having scaled AI with high impact), a proportion surpassed only by fintech (49%) and software/IT firms (46%)
While detailed GenAI adoption rates for every industry vary by study, indicators show sectors like technology, finance and insurance are ahead of others like manufacturing or government in GenAI experimentation. For instance, a 2024 Statista study noted generative AI usage in financial services jumped to 52% of firms actively using it (up significantly from 2023).
Another survey of AI-savvy firms found that industries that underwent early digital disruption (e.g. finance, tech) have been quicker to adopt GenAI as well. A survey from SAS underscores that financial institutions lead in integrating AI into operations. The study found nearly 98% of banks (and insurers) either already use or plan to use generative AI in the near term—the highest among industries.
Meanwhile, BCG's 2026 financial institutions research identifies AI as a major opportunity to improve productivity across banking operations, underwriting, wealth management and customer service.
Several structural factors accelerate adoption: banks already operate large digital platforms, handle substantial volumes of structured financial data, face significant compliance costs and compete to deliver faster, more personalized experiences.
However, widespread adoption does not mean banks have fully transformed their operating models. As BCG's 2025 retail banking research emphasizes, realizing AI's potential requires strong data foundations, redesigned workflows and governance—not simply deploying more individual use cases.
Banking's advantage is its ability to integrate intelligence into everyday financial decisions and interactions. Its challenge is turning that capability into measurable value and distinctive customer experiences.
What Business Results Are Banks Achieving With AI
AI in banking creates business value through operational efficiency, stronger financial security, faster customer service, more accurate decisions and personalized financial relationships. However, the results differ significantly by institution, implementation maturity and use case.
For example, among banks that have implemented GenAI, 88% have seen improvements in risk management and compliance, and 85% report time/cost savings. These are significant positive outcomes.
BCG's 2025 Global Retail Banking Report estimates that large-scale adoption of AI could unlock more than $370 billion in additional annual retail banking profits by 2030. This is a modeled future opportunity, not value already realized.
Banks also use GenAI in diverse departments: marketing is the most common area (47% of banks use GenAI there), followed by IT (39%), sales (36%), finance (35%) and customer service (24%)—all higher rates than cross-industry averages.
The banking AI case studies illustrate four principal sources of value:
1. Lower Operational Costs and Higher Productivity
AI assistants and employee copilots reduce repetitive administrative work, accelerate information retrieval and support faster processing of complex banking workflows.
For example, Goldman Sachs scaled its GS AI Assistant to approximately 40,000 users by May 2026, while BNY reported that AI-assisted onboarding was completed 20% faster for the clients supported by its AI workflows.
2. Better Fraud Detection and Financial Security
Predictive models and AI-powered risk assessment help banks identify suspicious behavior, investigate financial crime and reduce unnecessary interruptions to legitimate transactions.
HSBC's AI-powered anti-money laundering system identified two to four times more suspicious activity while reducing false-positive alerts by approximately 60% compared with its previous rules-based approach, according to its earlier deployment results.
3. Faster Customer Service and Self-Service
Conversational banking and service automation help customers resolve inquiries independently, reduce waiting times and complete selected banking tasks through natural-language interactions.
NatWest's Cora handled 12.9 million customer conversations in 2025, with 50% requiring no human intervention. Its GenAI-supported journeys achieved approximately 20 percentage points higher autonomous resolution rates than comparable conventional journeys.
4. More Personalized Financial Relationships
AI-driven insights, predictive cash-flow analysis and proactive recommendations help customers understand their finances, anticipate needs and make more informed decisions.
RBC's NOMI Find & Save helped customers set aside more than CAD 9.6 billion cumulatively through 2025, while JPMorganChase reported 25% higher engagement from AI-powered mobile banking home-screen personalization.
These results demonstrate that AI value should be measured through improved financial and customer outcomes, not simply the number of models, assistants or automated interactions deployed.
What Are the Most Common AI Use Cases in Banking
Banks initially focused AI on fraud detection, credit-risk assessment, customer service automation, personalized financial recommendations, anti-money laundering, investment analytics and operational automation. Indeed, 64% of finance leaders report using AI for fraud detection and risk management in their institutions.
According to the European Central Bank's March 2026 analysis, significant euro-area banks report AI usage across several key functions:
- Fraud and cybercrime detection: More than 50% of banks.
- Marketing and customer targeting: Approximately 50%.
- Chatbots and customer assistance: Approximately 40%.
- Credit scoring and risk assessment: Approximately 30%.
These risk-oriented uses remain vital, but as AI capabilities have matured, banks are expanding into investment research, wealth management, trade finance, client onboarding, document processing, software development and agentic payment workflows.
A 2025 KPMG banking technology survey found that 78% of surveyed banking executives were already using AI or GenAI pilots for security and fraud prevention, while 77% were considering AI to enhance digital customer experience. The survey also found that 67% intended to prioritize enterprise GenAI enablement over the next three years.
These figures show how priorities are shifting from traditional risk-focused applications toward broader customer-facing and operational transformation.
The most important emerging development is agentic banking, where AI can coordinate actions across multiple systems rather than simply provide information or recommendations.
Banks are moving from using AI to detect, predict and inform toward using AI to assist, personalize and execute selected financial tasks. The greatest opportunity is making banking more intelligent without making it less transparent, secure or controllable.
Why AI Implementation Alone Does Not Guarantee Better Banking Customer Experience
AI implementation in banking does not automatically improve customer experience. When applied to fragmented digital journeys, unclear service processes or poorly understood customer needs, AI can automate existing friction rather than eliminate it.
This creates a strategic risk for financial institutions: investing in more intelligent technology without ensuring that it solves the right customer problems.
The evidence increasingly supports this distinction. McKinsey's 2026 Global AI Survey found that only 6% of surveyed organizations qualified as AI high performers. Nearly three-quarters of these high performers reported fundamentally redesigning workflows around AI, compared with approximately one-quarter of other respondents.
For example, an AI assistant may help customers navigate a complex banking app, but the underlying problem could be an unnecessarily complicated service journey. Automating that journey may improve speed while leaving its fundamental weaknesses unresolved.
UXDA's perspective is that financial institutions should define the intended customer experience before deciding where AI belongs within it.
This requires connecting customer research, financial UX strategy, AI experience design and UX governance so that artificial intelligence supports consistent business and customer outcomes across products, channels and interactions.
The goal is not to make every banking interaction AI-powered. It is to identify where intelligence can meaningfully improve the financial experience—and where simpler design, clearer processes or human assistance would create greater value.
The competitive advantage will not come from how much AI a bank implements, but from how effectively that intelligence makes its customer experience more valuable, distinctive and trustworthy.
Where Is AI Adoption in Banking Growing the Fastest
AI adoption is growing globally, but the pace differs significantly across countries and financial markets. The United Arab Emirates and Singapore lead in population-level generative AI usage, while the United States remains a major center of AI development and banking investment. European countries are also among the fastest adopters, demonstrating that AI implementation is increasingly shaped by digital infrastructure, national strategies, skills and institutional readiness.
According to Microsoft's September 2026 Global AI Diffusion Report, 18.8% of the world's working-age population used generative AI in Q2 2026, compared with 17.8% in the previous quarter. Adoption increased across almost every economy measured.
These figures measure general generative AI usage, not specifically the percentage of banks deploying AI. However, they provide important context for the digital expectations and technology readiness of financial customers.
Which Countries Are Leading in AI Adoption
According to the Microsoft AI Economy Institute's Q2 2026 research, the countries with the highest measured generative AI usage among working-age populations are:
- United Arab Emirates – 73.3%
- Singapore – 64.3%
- Ireland – 49.9%
- France – 49.6%
- Norway – 49.4%
The UAE and Singapore have maintained their leadership through sustained investment in digital infrastructure, AI capabilities, government initiatives and technology adoption.
However, the latest findings also challenge the assumption that Western economies are necessarily slower adopters. Ireland, France and Norway rank among the top five, demonstrating substantial AI diffusion across Europe.
The United States leads in many areas of AI infrastructure and model development but has a lower rate of population-level adoption. Microsoft's Q1 2026 report recorded 31.3% generative AI usage among working-age Americans, placing the country 21st globally at that time.
For banking, these differences matter because customer familiarity with AI can influence expectations for conversational assistance, personalized financial recommendations and intelligent digital services.
Nevertheless, high consumer AI adoption does not automatically mean a country's banking sector has the most advanced AI implementation. Enterprise readiness, regulation, legacy infrastructure and financial customer trust also influence deployment.
How Widely Is Generative AI Being Used
Generative AI usage has expanded rapidly in both developed and emerging economies, although access and adoption remain uneven.
According to Microsoft's September 2026 AI Diffusion Report, generative AI usage reached 28.8% of working-age populations in the Global North, compared with 16.2% in the Global South during Q2 2026.
These figures reveal a widening divide between economies with strong digital infrastructure and those facing greater barriers to access.
At the same time, several Asian and Middle Eastern markets are accelerating. South Korea recorded a 3.5-percentage-point increase in adoption during Q2 2026, while Saudi Arabia climbed five positions in the global rankings. Japan also recorded increasing usage, supported partly by improvements in local-language AI capabilities.
For financial institutions, growing customer familiarity with generative AI creates opportunities to offer more intuitive digital experiences. Customers increasingly understand how to interact with AI through natural language, potentially reducing the learning curve for conversational banking and personalized financial assistants.
However, using AI for everyday information is different from trusting AI with financial decisions, sensitive data or transactions. Banks must translate technological familiarity into financial confidence through secure, transparent and controllable experiences.
How Do Regulation and Policy Affect Banking AI Adoption
National AI strategies, financial regulation, data infrastructure and technology policies significantly influence how banks implement artificial intelligence.
In the European Union, the AI Act establishes a risk-based regulatory framework, including requirements relevant to high-risk financial applications such as certain creditworthiness assessments. Combined with GDPR and existing financial regulations, this increases the importance of explainability, data governance, risk management and human oversight.
However, regulation does not necessarily prevent adoption. The European Central Bank reported in March 2026 that nearly 90% of significant euro-area banks already use AI technologies, demonstrating widespread implementation within a regulated banking environment.
In the United States, regulatory attention focuses on model risk, fair lending, cybersecurity, consumer protection and third-party technology dependencies. Updated interagency model risk management guidance issued in April 2026 emphasizes a risk-based approach to governance and validation while distinguishing traditional quantitative models from newer generative and agentic AI systems.
In the UAE and Singapore, national AI initiatives, advanced digital infrastructure and supportive technology ecosystems create favorable conditions for financial innovation. Banks are expanding applications in customer service, financial security, wealth management and intelligent automation.
In China, strong domestic AI development and locally available models support adoption within the country's financial technology ecosystem, alongside requirements relating to data security and AI governance.
The broader implication is that AI adoption is not simply a race to deploy technology fastest. Financial institutions must balance innovation with regulatory compliance, operational resilience and customer trust.
For banks operating internationally, consistent AI experience standards become particularly important as implementation requirements differ between markets.
How Are U.S. Banks Using AI
U.S. banks are moving from generative AI experimentation toward large-scale implementation across customer service, financial security, wealth management, lending and operational workflows. Leading institutions are combining predictive AI with generative and agentic capabilities to improve both customer-facing experiences and the processes behind financial services.
JPMorganChase, Bank of America, Morgan Stanley, Goldman Sachs and Wells Fargo have expanded AI beyond isolated pilots into enterprise platforms, specialized assistants and business-specific applications.
The strategic challenge is increasingly shifting from whether banks should adopt AI to where intelligence can create measurable financial and customer value.
How Widely Are U.S. Banks Adopting AI
The banking industry's transition toward production AI is evident in recent research.
According to EY's 2025 banking generative AI survey, 47% of surveyed banks had fully implemented generative AI applications in 2025, compared with only 10% in 2023. In addition, 90% had reached at least the beta-testing stage, compared with 64% two years earlier.
These figures represent the survey's banking respondents across its covered markets, not a U.S.-only national adoption rate.
AI implementation is also becoming more common among smaller financial institutions and specialized banking teams. According to the American Bankers Association's June 2026 research, the proportion of surveyed bank marketers using AI-powered marketing tools increased from 16.9% in 2024 to 29.9% in 2025 and 50.4% in 2026.
The growing adoption is also visible in banking operations. For example, Bank of America's virtual financial assistant Erica surpassed 3.2 billion cumulative customer interactions by March 2026, including nearly 700 million interactions during 2025, according to the bank's official disclosure.
These developments indicate that AI has progressed beyond experimentation at major U.S. financial institutions, although implementation maturity varies considerably between banks and individual use cases.
What Are the Main AI Use Cases in U.S. Banking?
U.S. financial institutions apply AI across customer-facing services, financial decision-making and internal operations.
The most established applications include fraud detection, credit-risk assessment, anti-money-laundering monitoring, investment analytics and customer personalization.
Generative AI has accelerated additional applications in conversational banking, financial advisory assistance, document analysis, software development and operational automation.
According to EY's 2025 banking GenAI survey, banks are increasingly moving from pilots to implementation, although data quality, regulation and execution remain significant challenges.
The most relevant AI banking use cases include:
- Fraud prevention and financial security: Predictive models identify suspicious transactions, assess payment risks and support investigations.
- Conversational banking and customer self-service: Virtual assistants help customers understand finances, access information and complete selected tasks.
- Personalized financial guidance: AI analyzes financial behavior to generate relevant insights, recommendations and proactive notifications.
- Wealth management and investment research: Intelligent assistants support advisors with portfolio analysis, research synthesis and client preparation.
- Credit underwriting and lending: AI supports risk assessment, document processing and more efficient credit decisions.
- Agentic banking and operational automation: Specialized AI agents coordinate selected workflows across onboarding, payments, servicing and compliance.
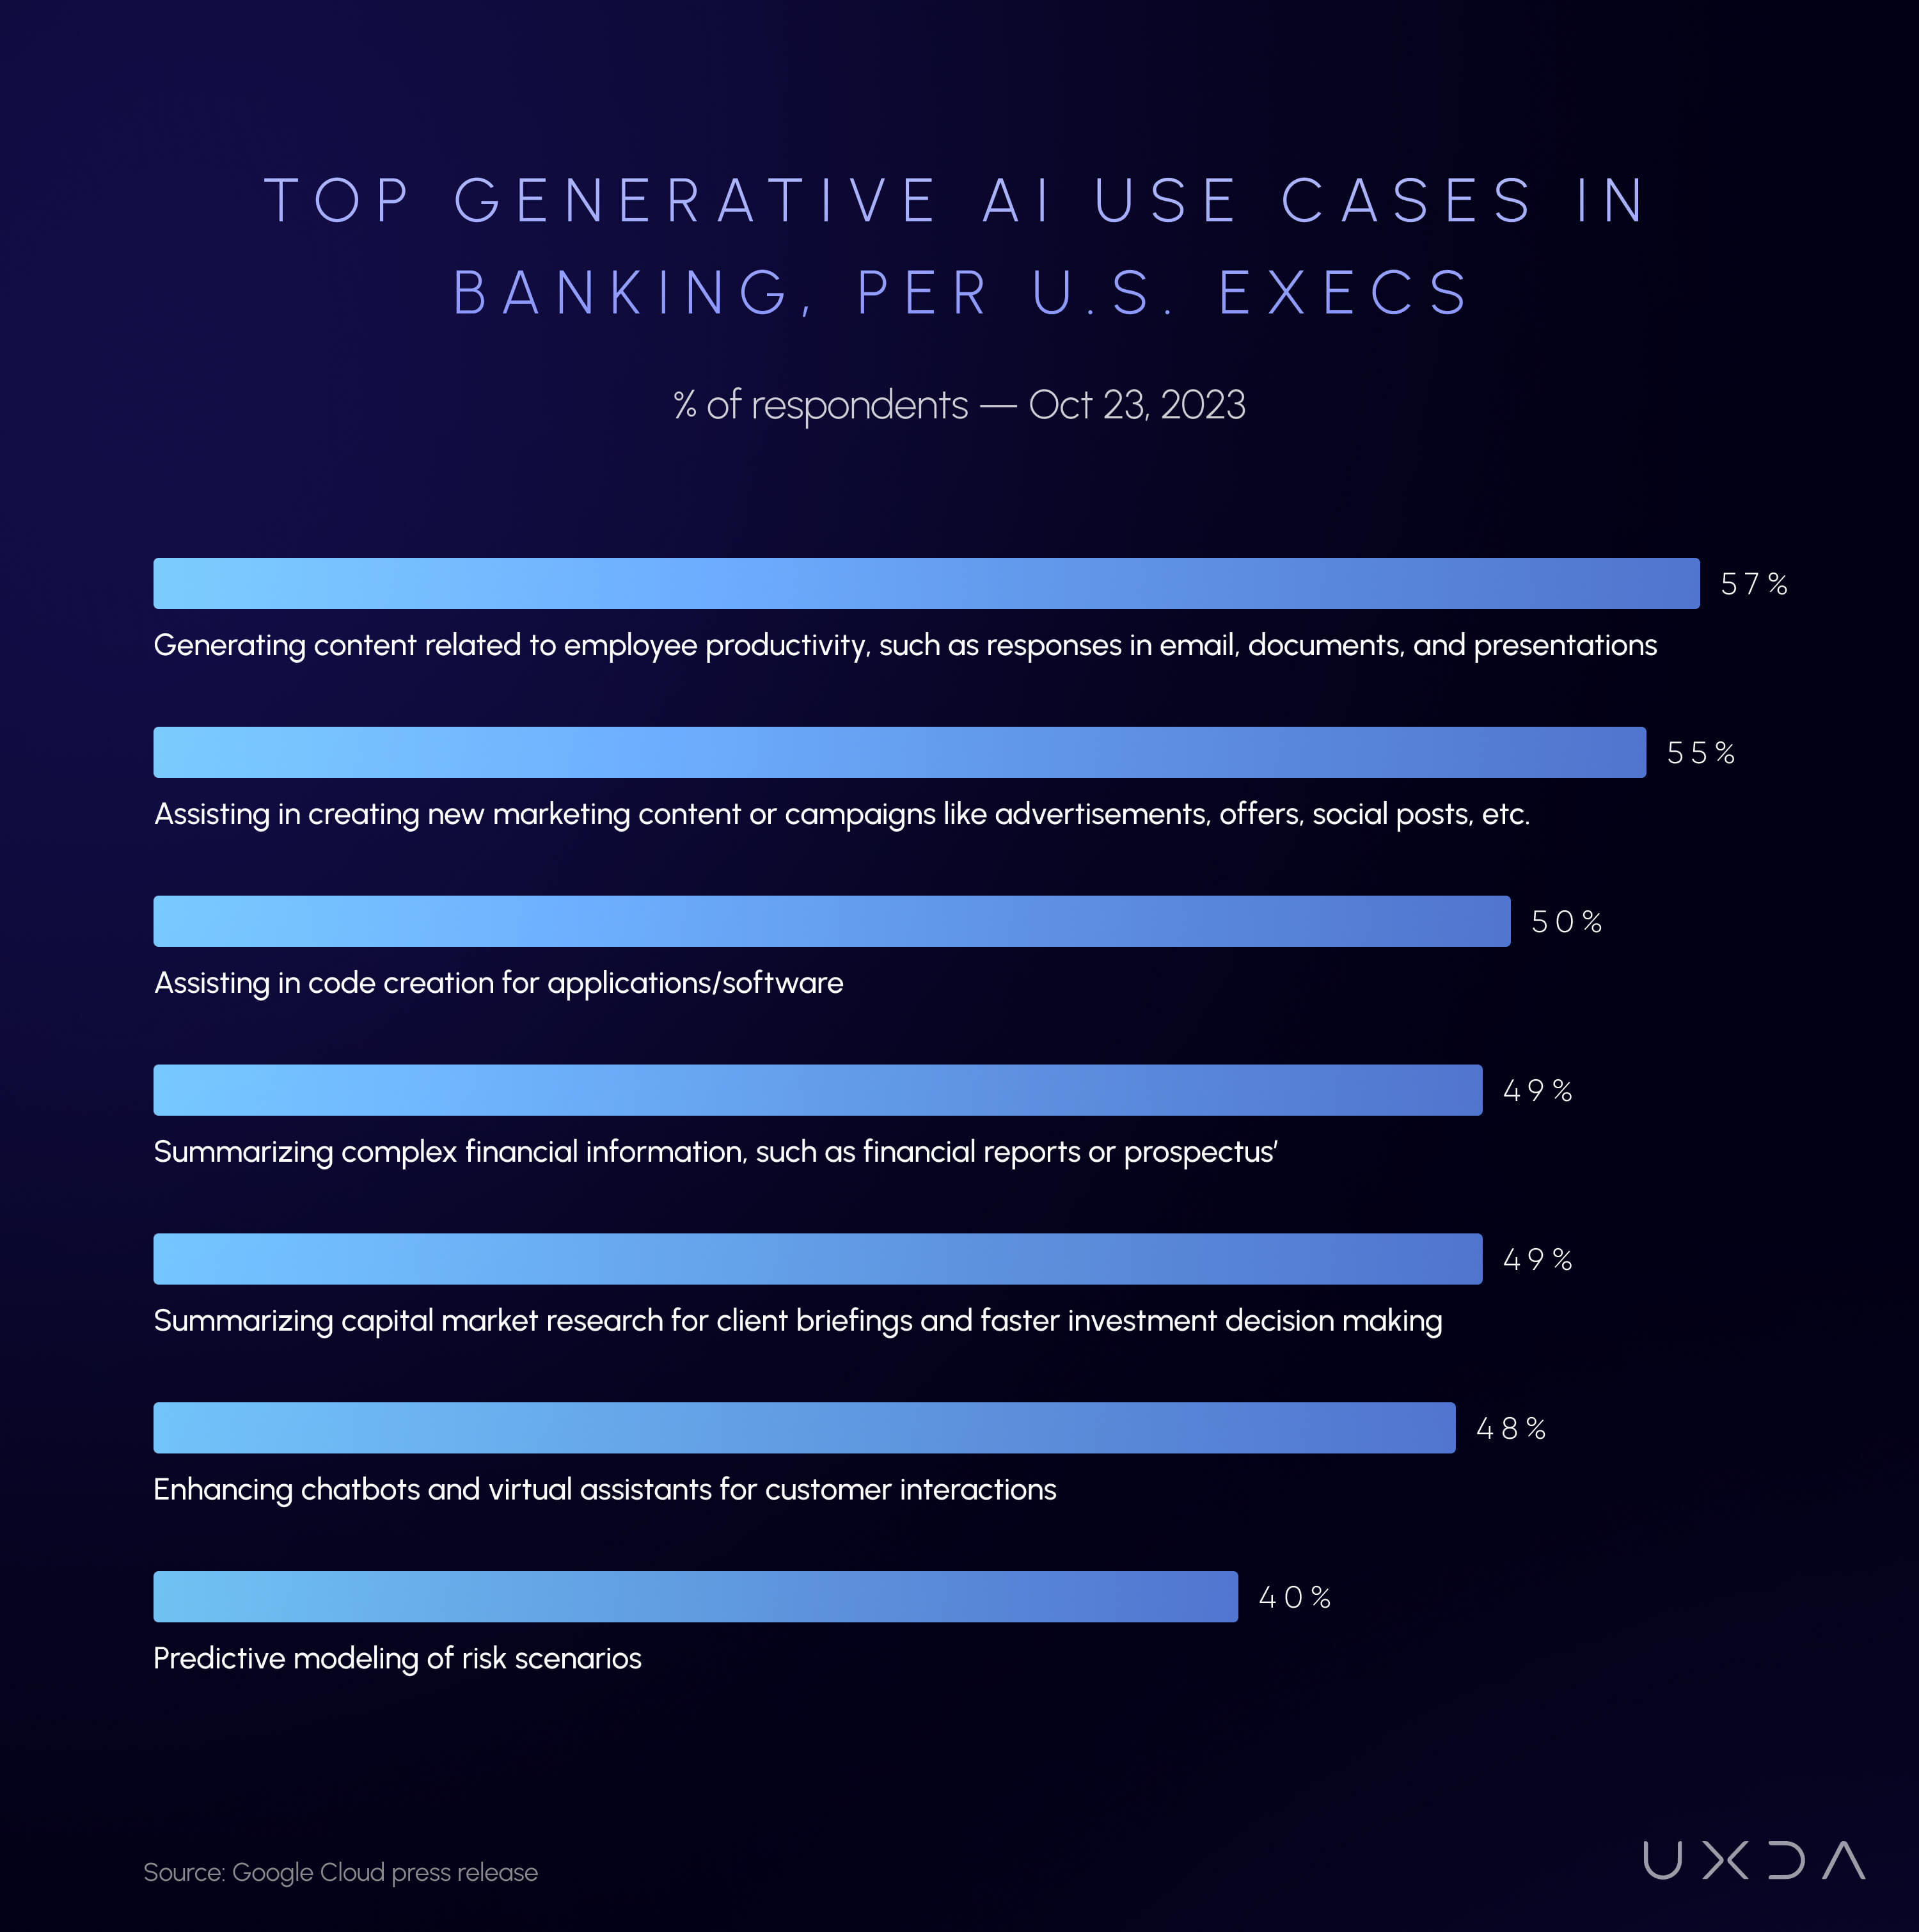 Source: Google Cloud press release / 2023
The most significant development is the shift from AI systems that provide information toward AI systems that can help complete defined financial tasks.
For example, Morgan Stanley's AI tools assist advisors with research and client meetings, while JPMorganChase uses specialized AI agents in wealth management workflows. Capital One's agentic car-buying assistant supports vehicle discovery and dealership appointments.
This evolution creates opportunities to redesign financial services around customer intentions rather than traditional navigation structures.
How Much Are U.S. Banks Investing in AI?
U.S. financial institutions are increasing investment in AI as part of broader technology modernization, operational transformation and digital customer experience strategies.
According to Boston Consulting Group's June 2026 Global Financial Institutions Report, financial institutions globally planned to invest approximately 2% of revenue in AI during 2026, with only the technology industry investing more relative to revenue.
One example of the scale of U.S. banking technology investment is JPMorganChase's approximately $19.8 billion technology budget for 2026, representing an increase of approximately 10% year over year.
This is JPMorganChase's total technology budget, not its dedicated AI investment. The spending supports technology infrastructure, cybersecurity, cloud, data, modernization and AI initiatives.
The potential financial value is substantial. In its 2025 Global Banking Annual Review discussion, McKinsey described a central scenario involving approximately $700 billion in potential banking cost savings from thoughtful AI adoption, while emphasizing that competitive pressure could pass much of this value to customers.
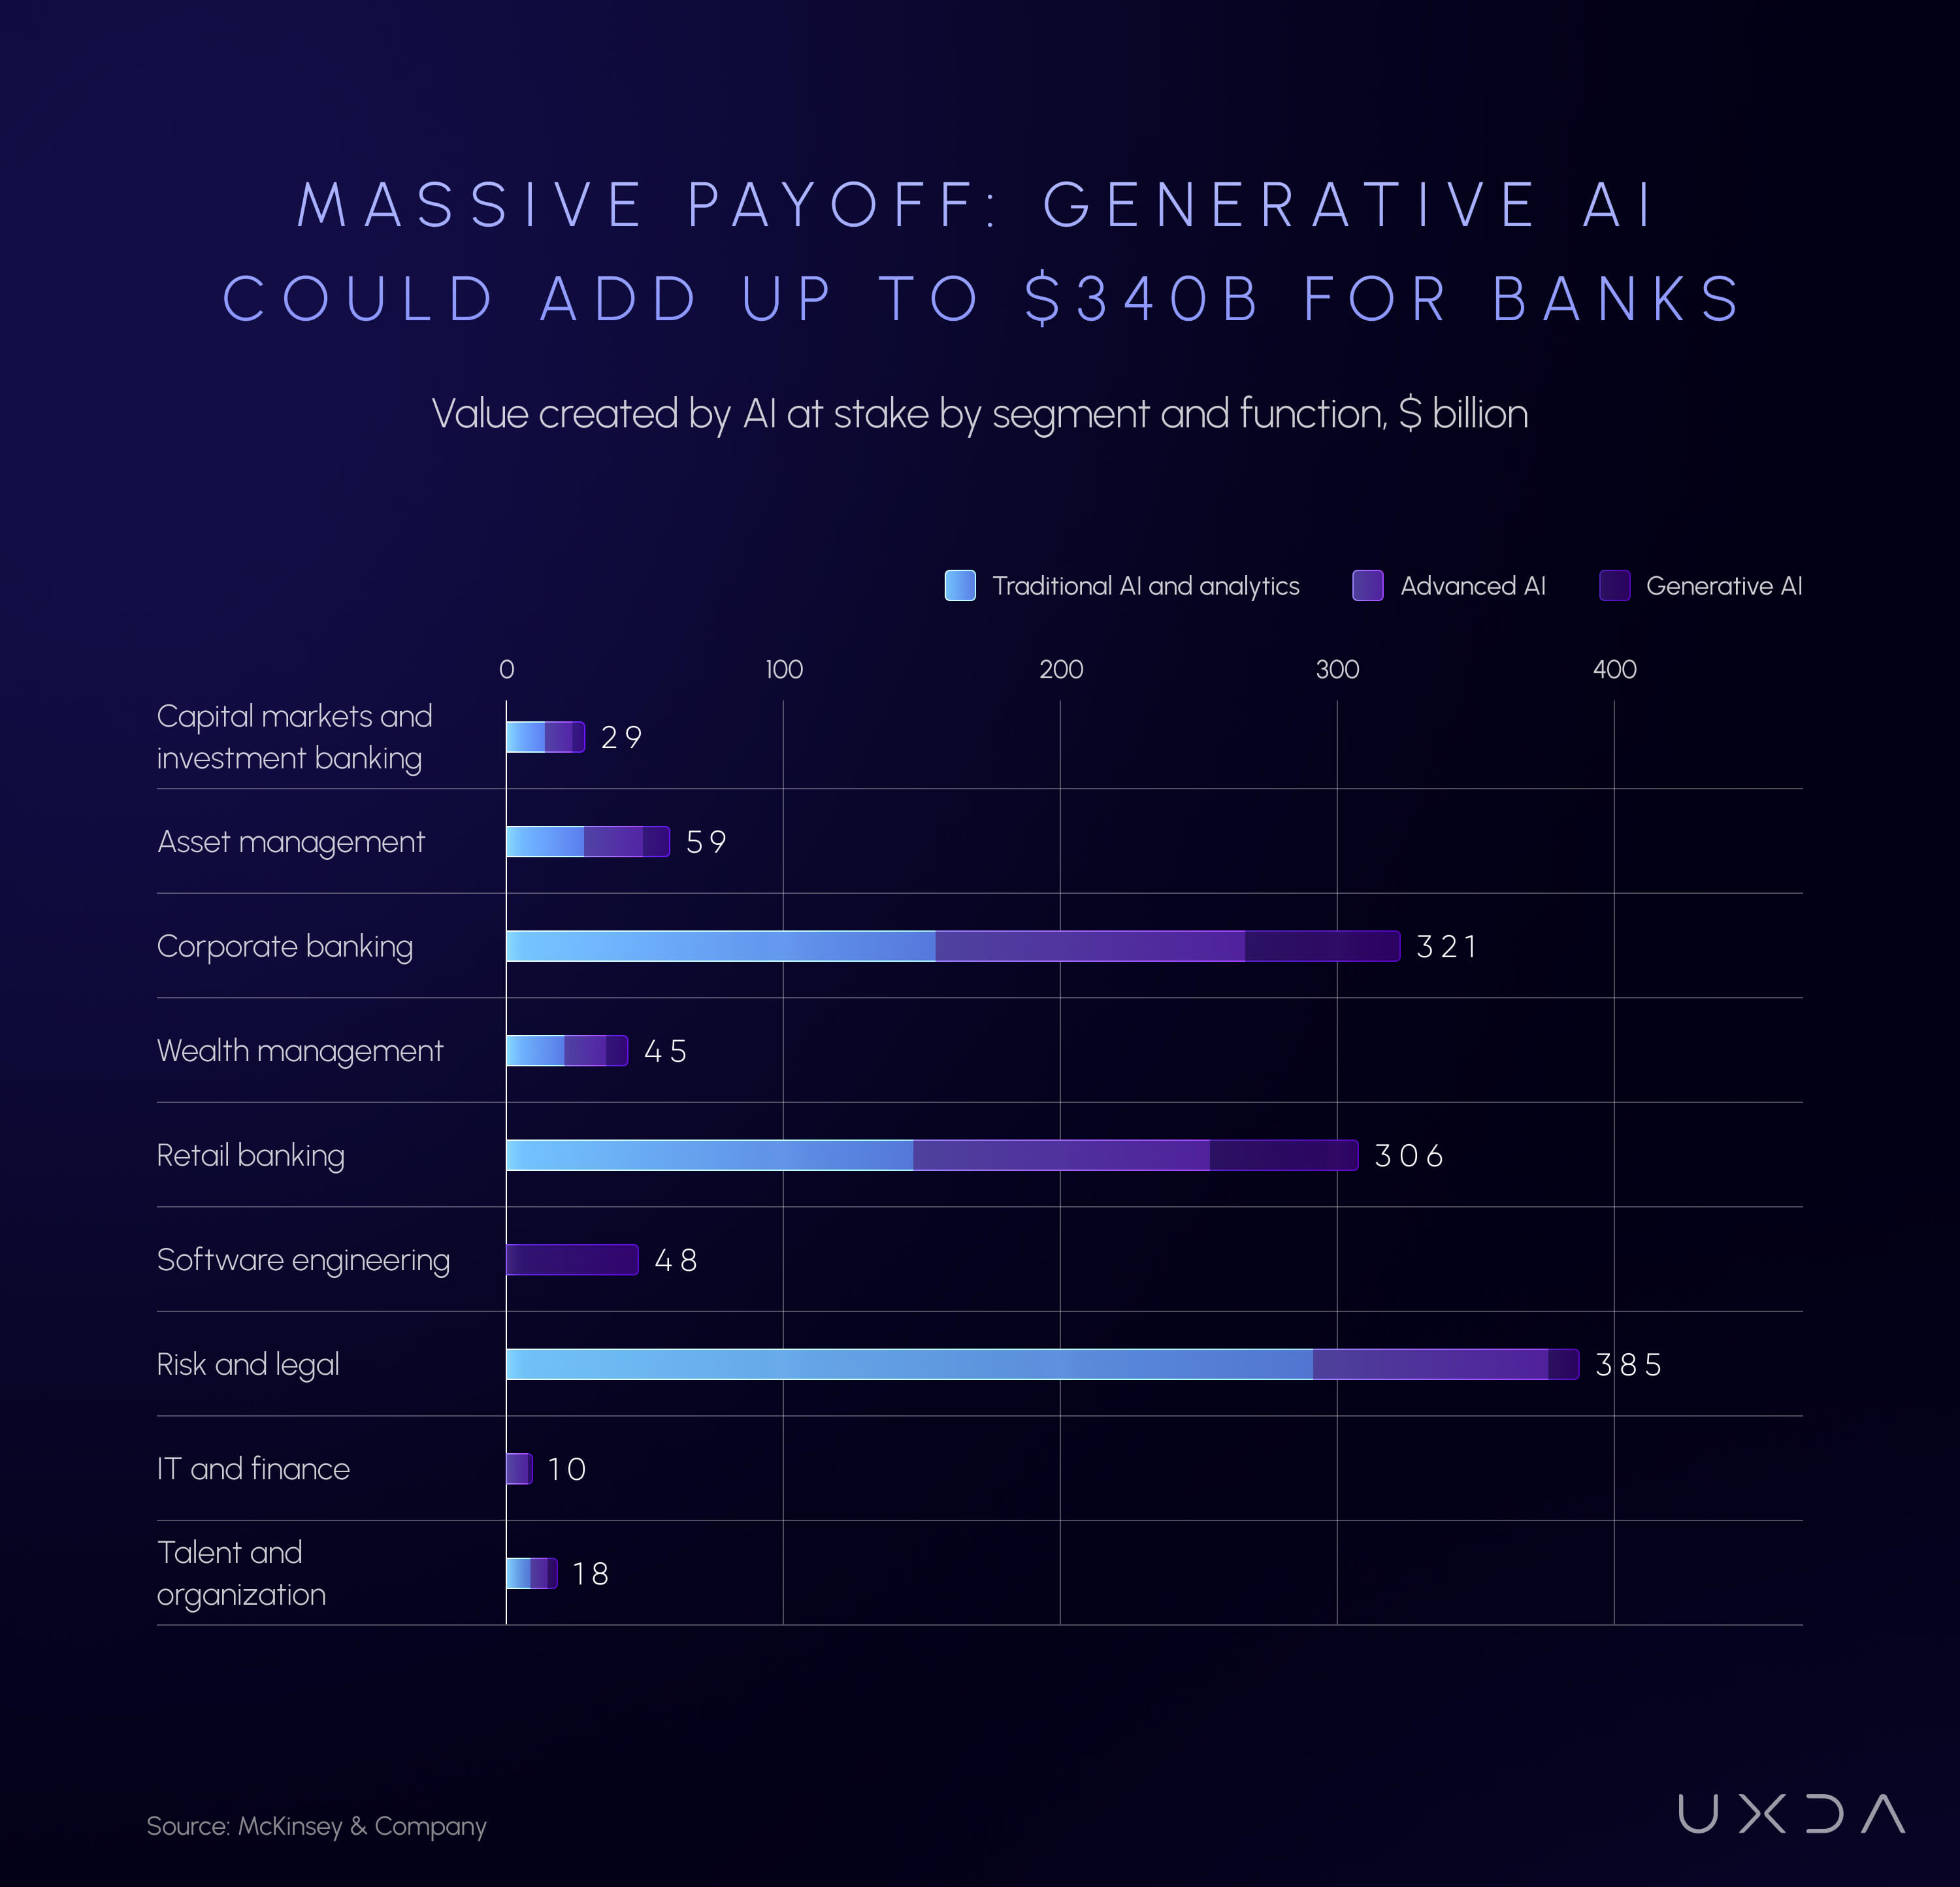 Source: McKinsey & Company
For financial executives, the important distinction is between technology expenditure and realized customer or business value. Increasing AI budgets is not evidence of successful transformation unless implementation improves service quality, productivity, risk management, growth or competitive differentiation.
What AI Banking Developments Emerged So Far?
U.S. banking AI advanced significantly during 2025–2026, moving beyond general-purpose employee assistants into specialized AI tools and increasingly integrated financial workflows.
Several developments illustrate this transition:
- JPMorganChase scaled LLM Suite to more than 200,000 users and expanded specialized AI agents for wealth management, investment research and operational workflows.
- Morgan Stanley expanded AI-assisted financial research, advisor meeting automation and institutional knowledge retrieval, with its advisory AI assistant achieving 98% adoption among financial advisor teams.
- Goldman Sachs scaled GS AI Assistant to approximately 40,000 employees by May 2026 and expanded AI development for banking operations, risk management and complex workflows.
- Bank of America surpassed 3.2 billion cumulative Erica interactions and expanded AI into wealth management meeting preparation, employee assistance, corporate banking and fraud detection.
- Wells Fargo exceeded one billion cumulative Fargo assistant interactions and introduced AI-powered wealth advisor assistance through its Advisor Gateway ecosystem.
- BNY scaled its Eliza platform to more than 300 AI solutions, applying specialized digital employees to client onboarding, payment repair and settlement processing.
- Capital One introduced Chat Concierge, a multi-agent AI assistant supporting selected stages of the car-buying journey.
Together, these cases demonstrate the expanding role of AI across retail banking, wealth management, investment banking and institutional financial services.
The most important change is that AI is increasingly being integrated into the underlying delivery of financial services, not simply added as another customer-facing chatbot.
What Are the Main Challenges for AI Adoption in U.S. Banking
Despite rapid implementation, U.S. banks face significant challenges in scaling AI responsibly and demonstrating sustainable business value.
Financial institutions must address data privacy, cybersecurity, biased or inaccurate decisions, model reliability, third-party dependencies and regulatory compliance.
The expansion of agentic AI introduces additional questions about authorization, accountability and control. When AI systems can initiate actions or coordinate financial transactions, banks must establish clear limits on what agents can access, recommend and execute.
Regulators continue adapting their supervisory approaches. The OCC, Federal Reserve and FDIC issued revised model risk management guidance in April 2026, emphasizing governance proportional to the complexity and risks of financial models. Generative and agentic AI models are outside the specific scope of that guidance, reflecting the need for further consideration of these technologies.
Customer trust remains another significant challenge.
According to a 2026 Deloitte banking customer survey reported by the American Bankers Association, 72% of respondents were hesitant to share their financial information with generative AI tools, while 64% expressed concerns about potential bias in AI-generated financial recommendations.
Only 49% trusted banking information provided by generative AI, compared with 79% who trusted information from bank websites.
At the same time, 58% reported using generative AI to research banking products, indicating that customer adoption is advancing faster than confidence in the technology.
These findings highlight a critical distinction for financial institutions: customers may be willing to use AI to explore financial options without being ready to trust it with financial decisions or autonomous transactions.
For UXDA, this reinforces the importance of human-centered AI experience design. Financial institutions must provide transparent recommendations, understandable explanations, clear permissions, reliable outcomes and access to human assistance when needed.
In summary, U.S. banks are advancing from AI experimentation toward enterprise-wide implementation across fraud prevention, personalized banking, financial advisory, lending and agentic automation. The competitive advantage will not come from deploying the most AI tools, but from using intelligence to make financial experiences more valuable, secure, intuitive and trustworthy.
How Are UK Banks Using AI
UK banks are accelerating artificial intelligence adoption across customer service, fraud prevention, personalized banking, lending and operational automation. The UK financial services sector is progressing from predictive AI and generative AI experimentation toward integrated customer-facing applications and increasingly agentic banking workflows.
Recent regulatory research and industry surveys show that AI is already widely adopted, while 2025–2026 developments demonstrate growing investment in scaling intelligent financial services, improving productivity and redesigning customer interactions.
How Widely Are UK Banks Adopting AI
According to the Bank of England and Financial Conduct Authority's latest published joint AI adoption survey, 75% of surveyed UK financial services firms were already using AI, up from 58% in 2022. Adoption was particularly high among international banks operating in the UK, reaching 94%.
More recent research indicates that AI implementation is becoming more mature. According to EY's September 2025 Responsible AI Pulse Survey, 34% of surveyed UK financial services firms reported fully integrated AI solutions, while another 44% had embedded multiple AI systems into their operations.
The same survey found that 48% of financial services firms were already using agentic AI, with a further 16% planning implementation within six months. However, these figures reflect a survey of 50 executives across banking, insurance and wealth management, rather than a representative census of UK banks.
The Bank of England and FCA launched another joint AI survey in June 2026 to assess the deployment of machine learning, generative AI and agentic AI. Its findings are expected to provide a more comprehensive picture of the latest industry-wide adoption.
The strategic shift is from whether banks use AI toward how deeply intelligence is integrated into financial services and customer journeys.
How Quickly Is AI Adoption Growing in UK Banking
AI adoption is accelerating as UK financial institutions increase investment, expand enterprise deployments and move beyond experimental use cases.
According to EY's May 2026 financial services CEO survey, 88% of surveyed UK financial services CEOs increased their planned AI investment for 2026 compared with 2025.
The Lloyds Bank Financial Institutions Sentiment Survey 2025 found that 91% of surveyed financial institutions viewed AI as more of an opportunity than a threat, compared with 80% the previous year. Additionally, 51% planned to increase AI investment and 48% had established dedicated AI teams.
By June 2026, Lloyds' latest Financial Institutions Sentiment Survey described a further transition from AI pilots toward embedded business capabilities.
Investment is increasingly directed toward generative AI, agentic automation, data infrastructure, customer experience modernization and employee productivity.
However, increasing budgets and widespread experimentation do not automatically translate into measurable transformation. Financial institutions must redesign workflows, develop employee capabilities and establish governance to scale AI effectively.
What Are UK Banks Using Generative AI For
UK banks use generative AI for conversational customer service, personalized financial guidance, employee knowledge assistance, document processing, software development and increasingly agentic automation.
Applications are expanding from internal productivity tools into direct customer interactions and complex financial workflows.
Recent implementations demonstrate this evolution:
- NatWest expanded generative AI across 21 Cora customer journeys by the end of 2025. GenAI-supported journeys achieved approximately 20 percentage points higher autonomous resolution rates than comparable conventional journeys.
- Lloyds Banking Group introduced an AI financial assistant for Bank of Scotland customers, reaching more than 500,000 customers by June 2026. It also deployed agentic AI to support real-time fraud detection and launched the Envoy platform for developing specialized AI agents.
- HSBC scaled AI across more than 600 operational use cases, including financial crime detection, wealth management, corporate banking and employee support.
- NatWest and Lloyds also expanded AI-assisted knowledge retrieval, helping customer service employees access relevant information more efficiently and reduce administrative work.
The shift toward agentic AI is especially significant because these systems can coordinate defined tasks across applications and workflows rather than simply generate information.
According to the FCA's July 2026 Mills Review, approximately one in five UK adults—equivalent to 11 million people—said they were likely to use AI capable of acting autonomously within predefined goals.
This signals potential demand for more proactive and outcome-oriented financial experiences, although stated willingness does not establish actual adoption of autonomous banking services.
For financial institutions, the opportunity is to progress from AI assistants that explain banking processes toward intelligent experiences that help customers accomplish financial goals securely, transparently and with appropriate control.
Use Cases: What Benefits Are UK Banks Getting From AI
UK financial institutions are increasingly reporting measurable benefits from AI across productivity, customer service, financial security and business growth.
According to the Lloyds Bank Financial Institutions Sentiment Survey 2025, the proportion of surveyed institutions already experiencing specific AI benefits increased significantly compared with 2024:
- 59% reported improved productivity, up from 32% in 2024.
- 33% reported better client experiences, up from 14%.
- 34% reported greater customer insights, up from 18%.
- 21% reported business growth benefits, up from 8%.
These are self-reported benefits among surveyed financial institutions, not independently measured financial returns across all UK banks.
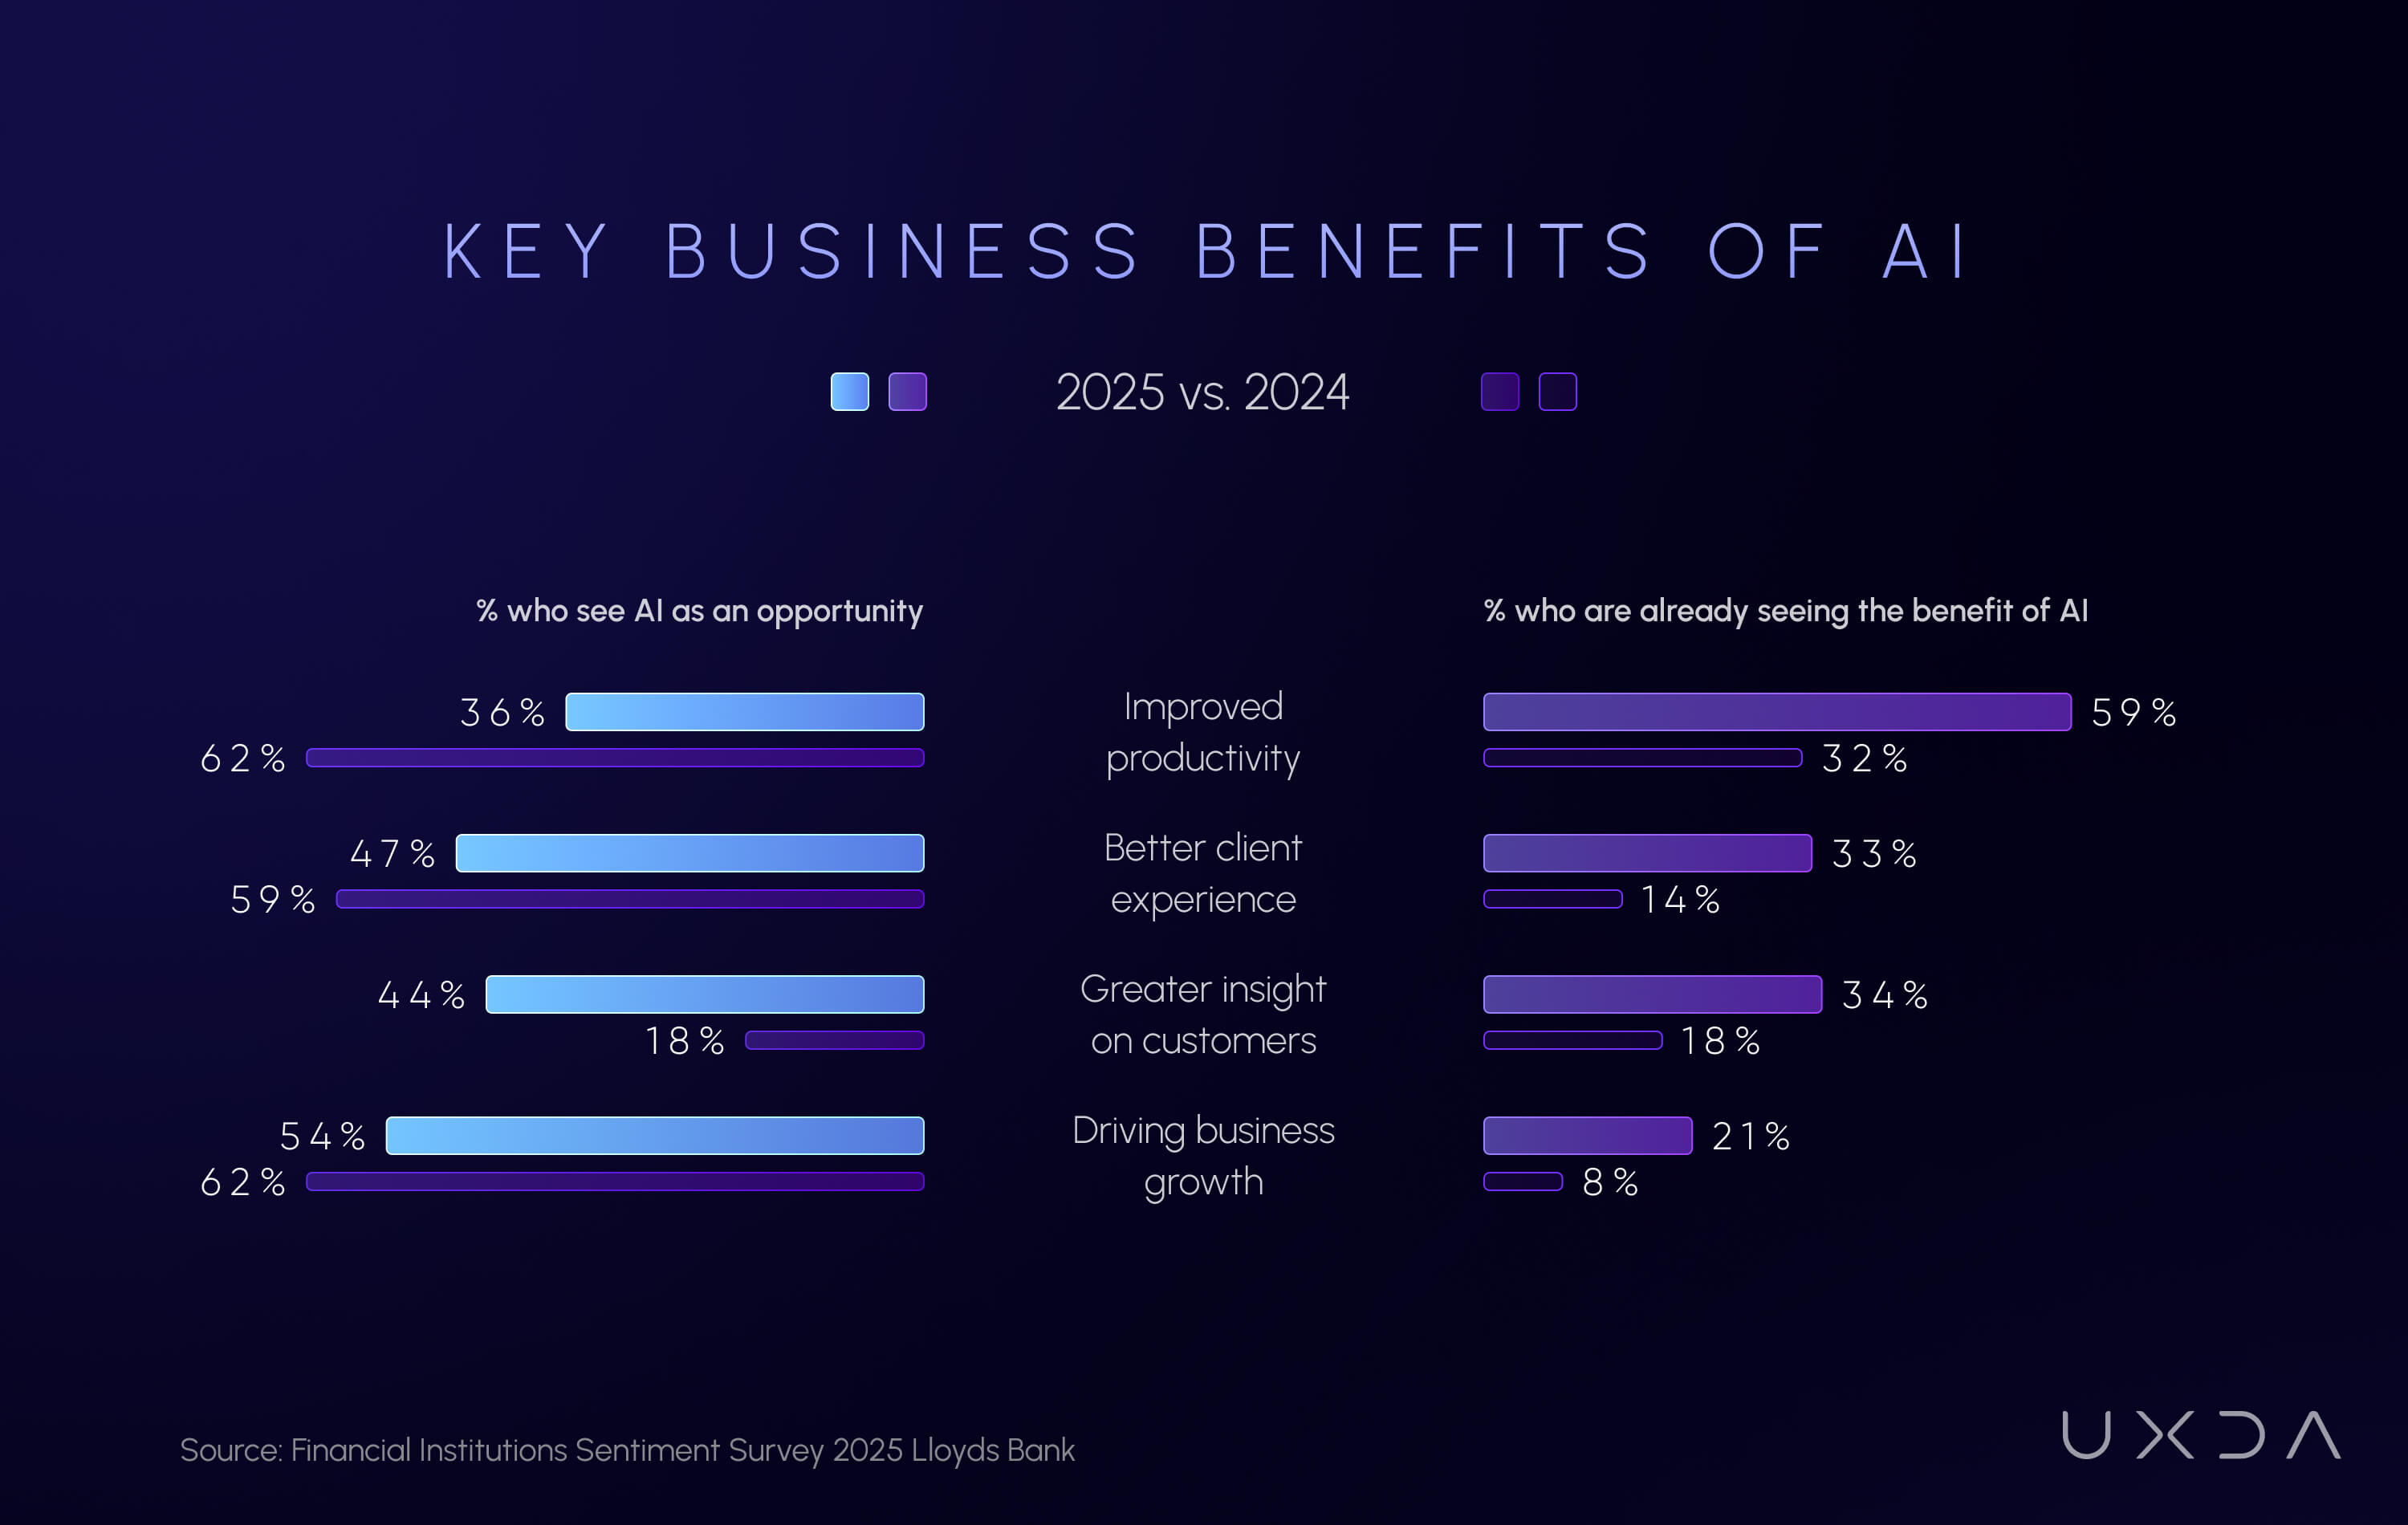 Source: Financial Institutions Sentiment Survey 2025 Lloyds Bank
Individual banking implementations provide further evidence of AI's operational and customer impact.
- NatWest reported that its Cora assistant handled 12.9 million customer conversations in 2025, with 50% requiring no human intervention. Its AI-assisted employee workflows also reduced time spent on routine documentation and customer support activities.
- Lloyds Banking Group reported approximately £50 million of economic value from generative AI in 2025. Its Athena knowledge assistant, used by approximately 20,000 employees, reduced average information search times by 66%.
- HSBC's AI-powered financial crime monitoring has demonstrated the ability to identify two to four times more suspicious activity while reducing false-positive alerts by approximately 60% compared with its previous rules-based approach, according to earlier deployment results.
These results illustrate four principal sources of AI value in UK banking: higher productivity, stronger financial security, faster customer service and more personalized financial relationships.
However, realized economic value, employee efficiency, customer satisfaction and AI adoption must be measured separately. More automated interactions do not necessarily mean customers receive better financial outcomes.
How Is Regulation Affecting AI Adoption in UK Banking?
The UK is pursuing a principles-based, regulator-led approach to financial AI, balancing innovation with customer protection, operational resilience and market stability.
Rather than relying on one comprehensive cross-sector AI law equivalent to the EU AI Act, the UK applies existing financial services requirements and regulatory principles to AI applications.
The Financial Conduct Authority and Bank of England are increasingly focused on model governance, accountability, transparency, consumer outcomes, cybersecurity and third-party dependencies.
According to the Bank of England and FCA's AI survey, one-third of reported AI use cases relied on third-party implementations, while 46% of firms reported only partial understanding of the AI technologies they used. Only 2% of surveyed AI use cases involved fully autonomous decision-making.
These findings highlight the importance of managing AI systems whose decisions, dependencies and risks may be difficult to understand or control.
More recent research identifies continuing governance gaps. EY's September 2025 survey found that 24% of surveyed UK financial services firms reported insufficient controls against unauthorized access or corruption, while 26% reported no or limited controls to ensure AI systems complied with laws and regulations.
Regulators are also actively supporting responsible innovation. The FCA launched its AI Live Testing initiative in 2025, with a second testing cohort beginning in 2026, providing a supervised environment for firms to test AI applications under real-world conditions.
The FCA's July 2026 Mills Review identified four major changes AI could create in retail financial services: transformation of financial operations, evolution of customer journeys, changes in competition and increased fraud and cybersecurity risks.
The Bank of England's July 2026 Financial Stability Report also highlighted emerging risks associated with advanced AI models, financial decision-making, third-party service providers and the evolving cyber threat environment.
For UK banks, the challenge is no longer simply implementing AI responsibly within individual functions. It is establishing AI experience governance across customer journeys, decisions, channels and operational workflows. This is especially important as agentic systems gain the ability to access customer information, recommend actions and execute selected financial tasks.
In summary, UK banks are progressing from widespread AI adoption toward more integrated, personalized and increasingly agentic financial services. Investment is rising, operational benefits are becoming measurable and customer-facing implementations are expanding. However, the next stage of banking AI transformation depends on translating technological capability into secure, transparent and genuinely better financial experiences.
For UXDA, the strategic opportunity is to help financial institutions define how AI should improve the customer relationship before deciding which technologies, agents or automated workflows to implement. The institutions that differentiate will not necessarily be those using the most AI, but those designing the most valuable, intuitive and trustworthy financial experiences.
How Is AI Transforming Digital Banking Customer Experience
AI in banking customer experience is shifting digital financial services from reactive, menu-driven interactions toward more personalized, conversational and proactive assistance. Its impact extends beyond chatbots to how banks understand customer needs, automate tasks, prevent problems and support financial decisions.
How Does AI Improve Personalization in Banking
AI personalization in banking uses financial data, transaction history and behavioral signals to adapt content, recommendations and services to individual customer needs. Rather than presenting the same experience to everyone, banks can anticipate relevant needs and offer contextual financial guidance.
Customer expectations for personalization are well established. McKinsey's Next in Personalization research found that 71% of consumers expect personalized interactions, while 76% become frustrated when these are missing. Although the figures come from a 2021 cross-industry survey, they remain useful historical context rather than new banking-specific data.
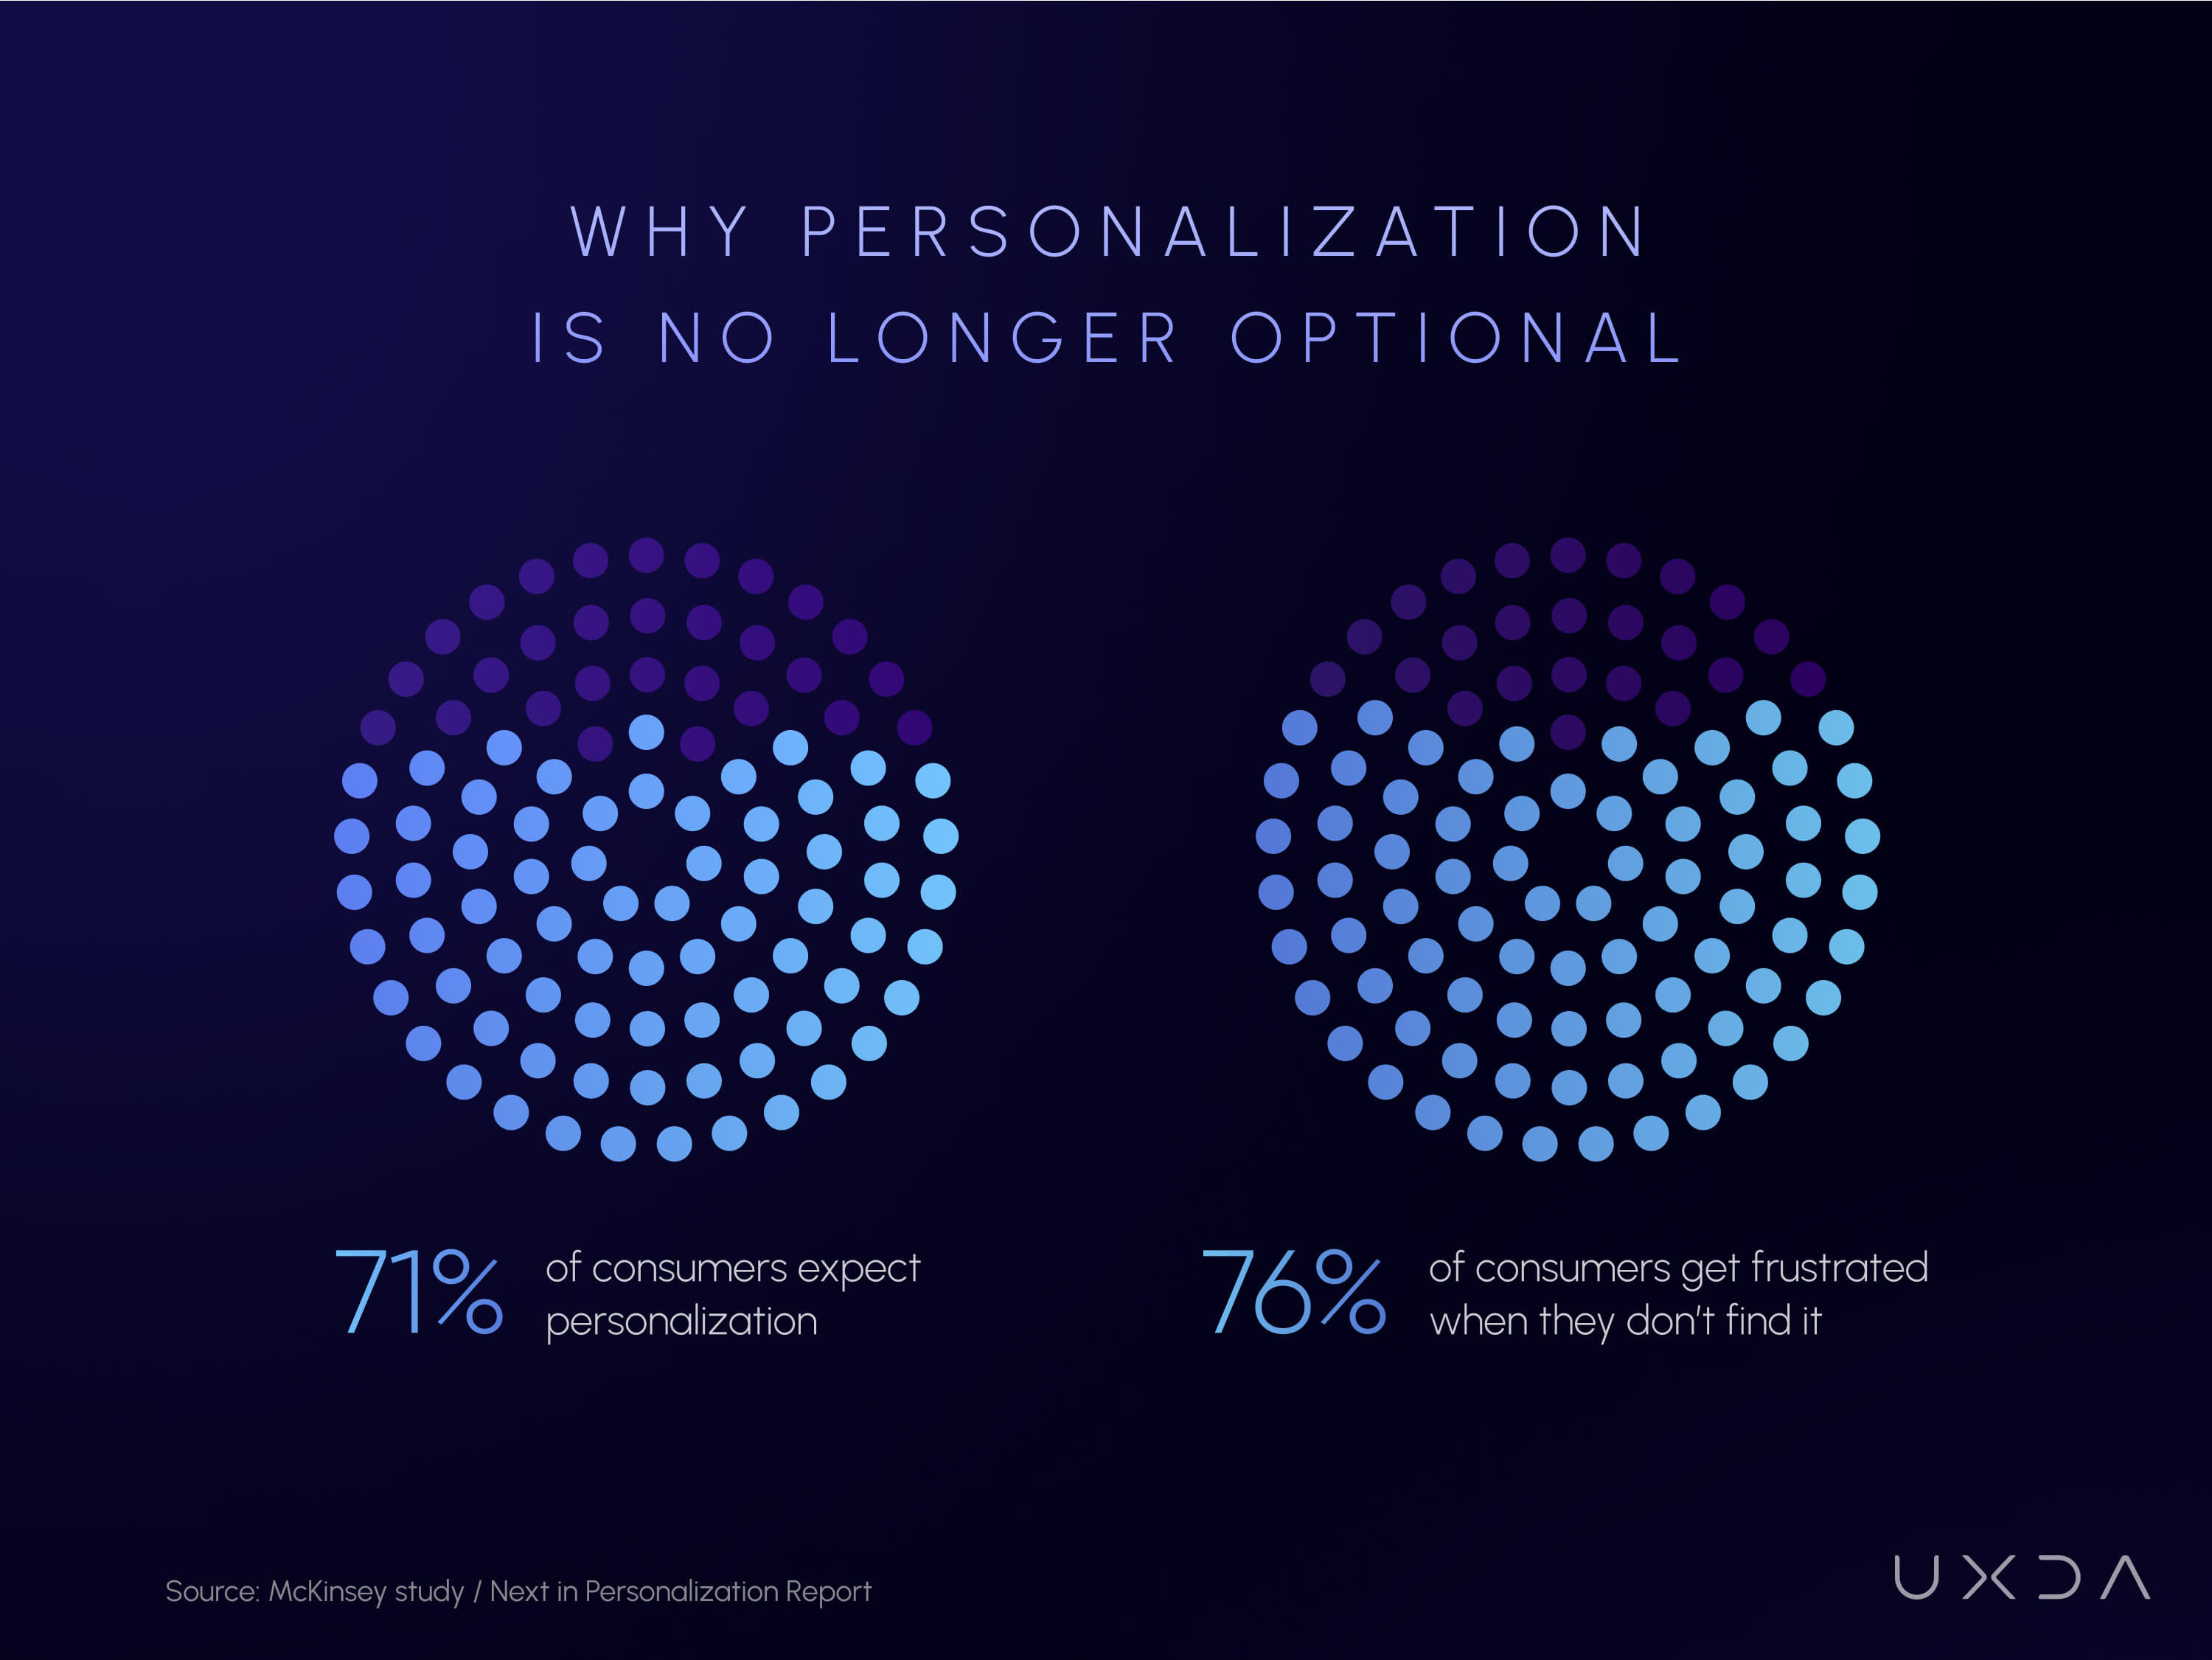 Source: McKinsey study / Next in Personalization Report
In banking, personalization is increasingly moving beyond targeted product offers toward intelligent financial management. For example, JPMorganChase reported 25% higher engagement from machine-learning-powered personalization of its mobile banking home screen.
Similarly, RBC's NOMI Find & Save uses predictive analysis of transaction patterns to help customers save automatically, contributing to more than CAD 9.6 billion cumulatively set aside since its 2017 launch.
In fact, a global marketing survey found personalization is the predominant use case for AI in finance, with 44% of organizations scaling AI to tailor customer experiences, anticipate needs and boost loyalty. This shift toward hyper-personalization is yielding tangible results: one analysis reported that using AI-driven insights for customer experience led to “double-digit boosts in revenue, customer satisfaction and campaign conversions” for financial institutions. In other words, AI isn’t just a gimmick; it’s translating into happier customers and improved business outcomes.
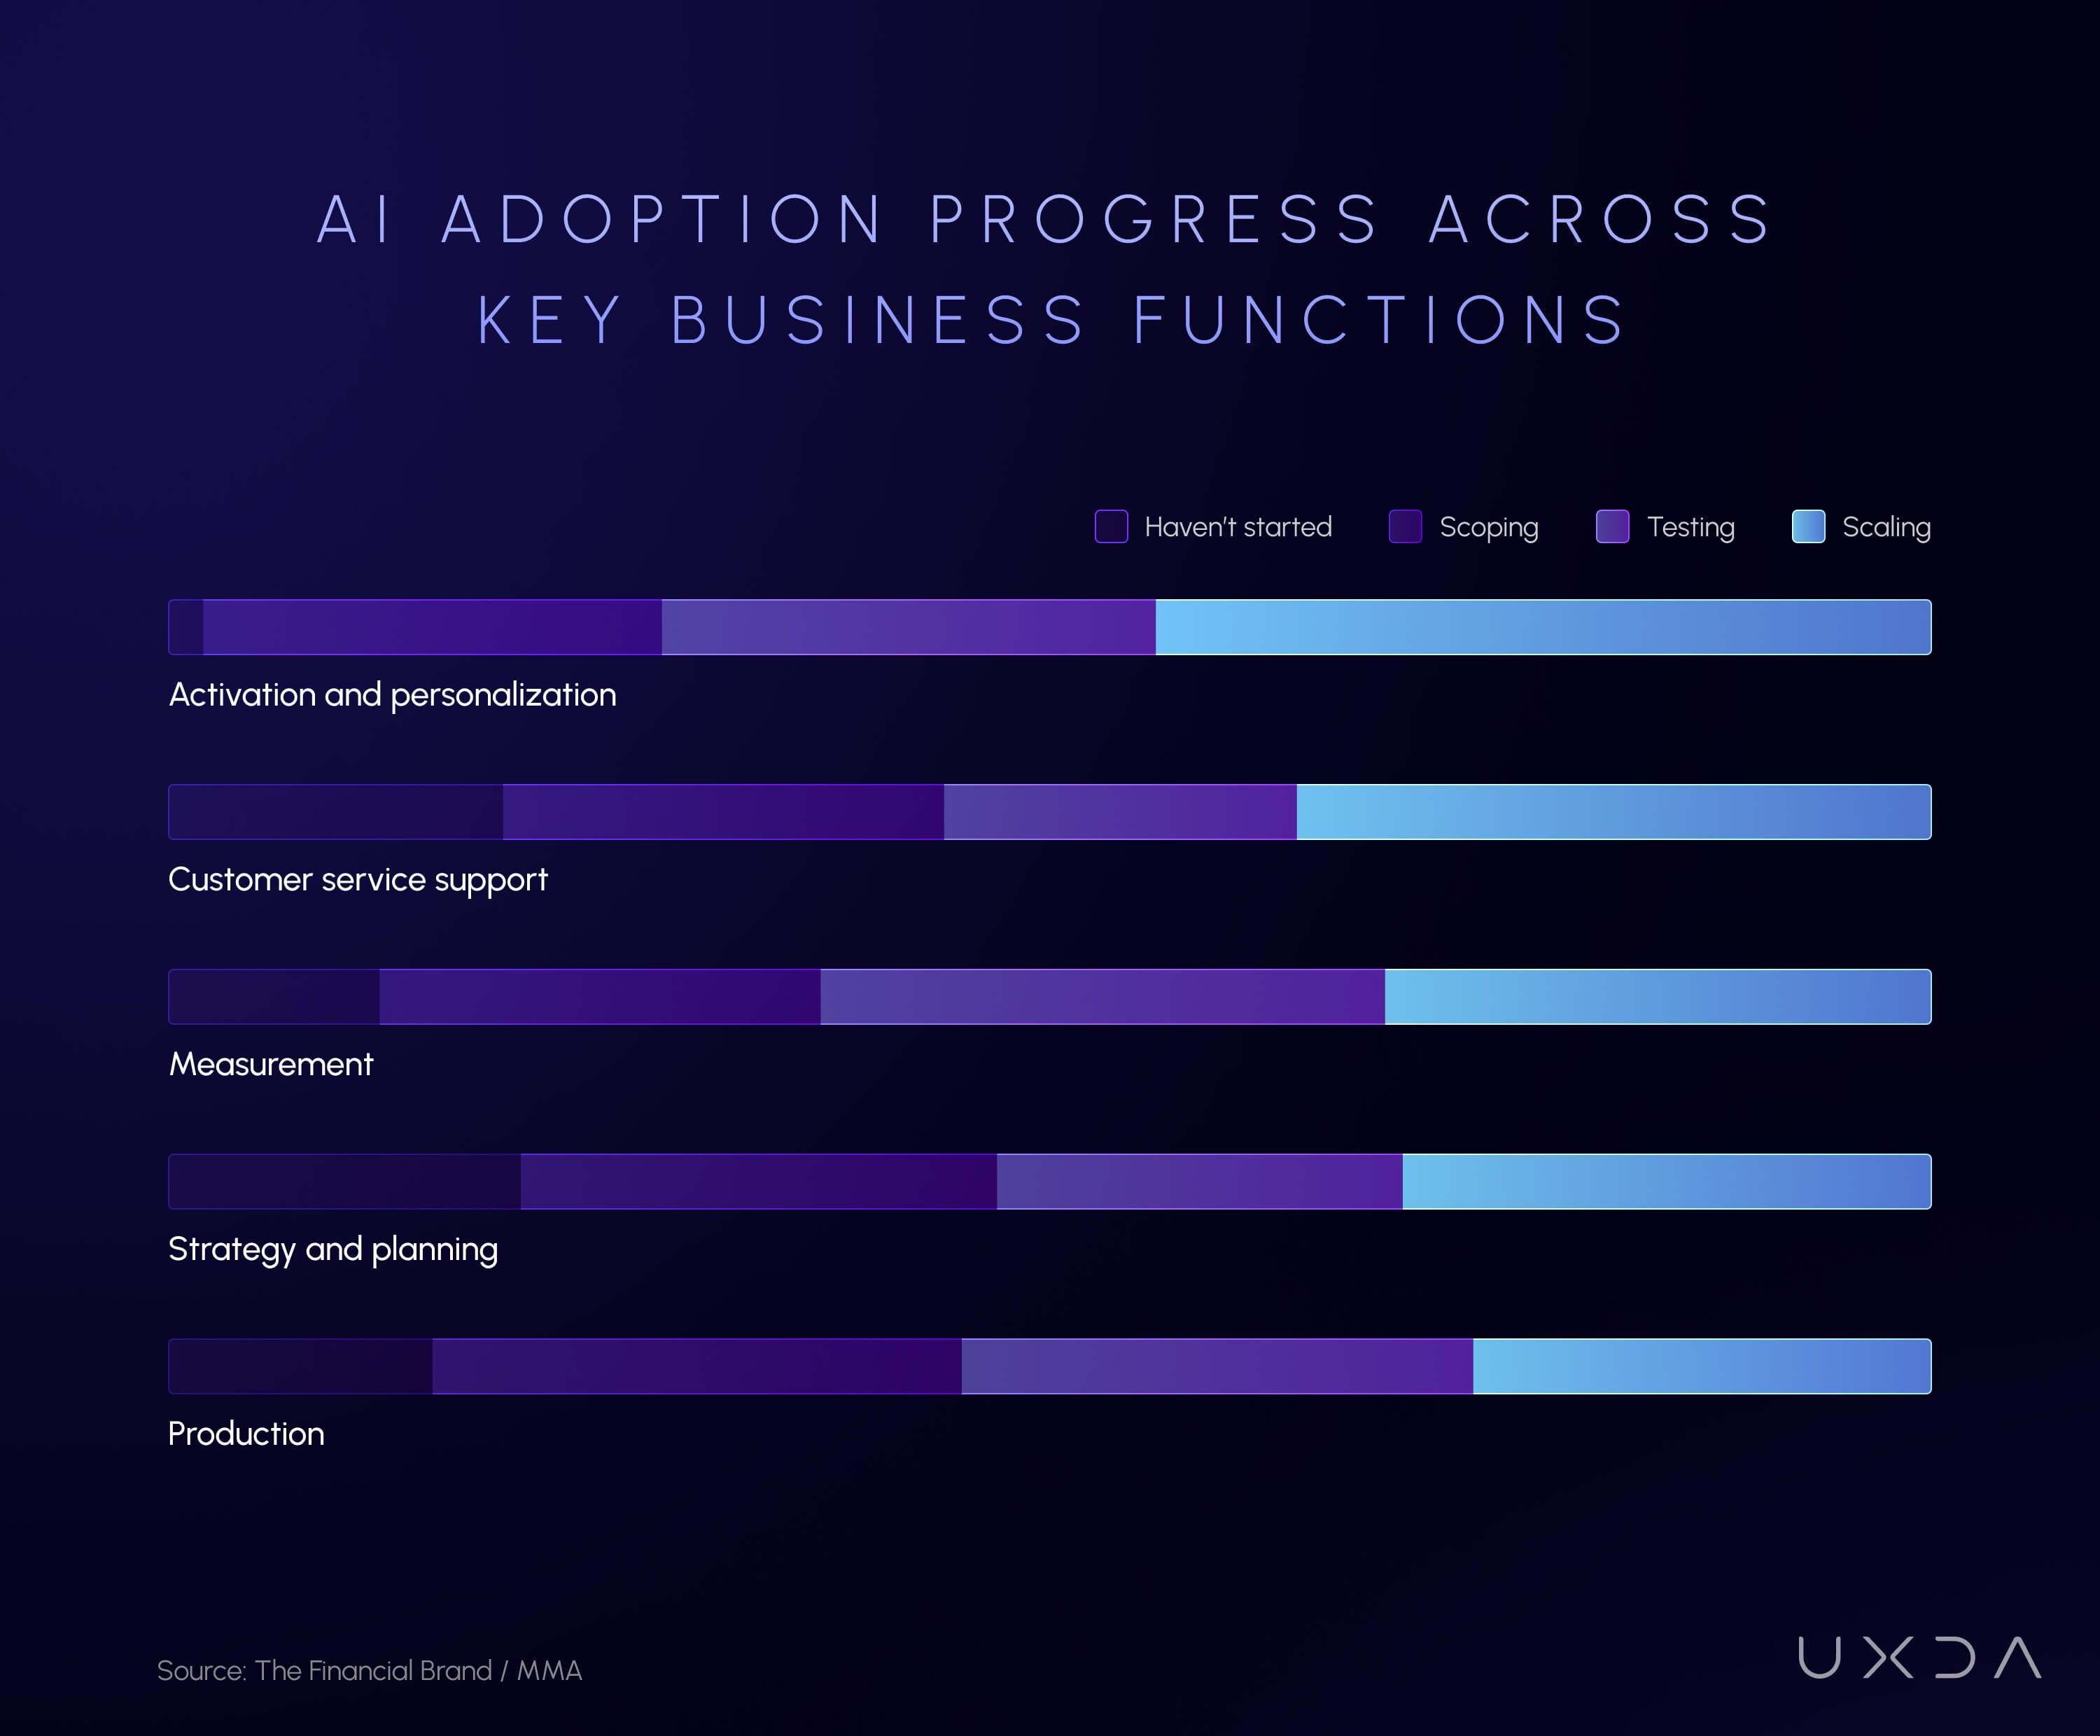 Source: The Financial Brand / MMA
Banks around the world rolled out AI-powered personalization features. Many mobile banking apps started offering AI-generated insights and advice customized to each user’s financial situation. For example, some banks use AI to automatically notify customers of unusual spending, predict upcoming bills or suggest budget adjustments—all tailored to the individual. In the US, Wells Fargo began leveraging predictive analytics and generative AI for dynamic content creation, aiming to deliver “hyper-personalized interactions that drive engagement and revenue.”
Regional banks also saw success: First Horizon Bank’s marketing team integrated AI to predict client needs and personalize messages, reporting “promising results” in deepening customer relationships. Meanwhile, in the UK, both incumbents and digital challengers invested in personalization. Digital-only banks like Starling Bank and Revolut (which reached 52.5 million customers in 2024) built their growth in part on personalized financial tools, prompting incumbents to follow suit.
The demand is high: a large majority of banking customers (in all age groups) want more personalized experiences, and almost half are willing to let banks use their data for this purpose. This pushed banks in 2024 to use AI not only for targeted product offers, but also to tailor content, notifications and even the user interface to each customer’s profile.
Beyond marketing, AI-driven personalization extended to financial advice and planning. Some banks piloted virtual financial advisors that analyze a customer’s goals and spending patterns to offer bespoke advice—for example, suggesting how to save for a house or which debt to pay down first. While these AI advisors gained some traction, trust remained a hurdle for sensitive advice: a survey found only 27% of consumers fully trust AI for financial guidance. To address this, banks paired AI insights with human validation or made AI recommendations fully transparent.
The overall trajectory is clear: personalization became a must-have aspect of digital banking, and AI provided the engine to deliver it at scale. Banks that executed well saw improvements in customer loyalty, whereas those with generic one-size-fits-all digital experiences risked falling behind.
As Capgemini’s global head of data for financial services noted, “AI and generative AI are rapidly transforming how we view personalized banking experiences… enabling analysis of vast data to generate tailored content, recommendations and interactions,” which is proving “transformational” for customer engagement.
The strategic shift is from personalized marketing to personalized financial experience: AI can increasingly adapt not only what a bank offers customers, but how the entire digital experience responds to their financial context.
How Does AI Improve Banking Self-Service
AI-powered banking self-service enables customers to find information, complete transactions and resolve problems without navigating complex interfaces or waiting for human assistance.
Digital banking has become mainstream. According to UK Finance's 2026 Payments Market Report, 91% of UK adults used some form of remote banking in 2025, including 75% who used mobile banking. These figures reflect overall digital adoption, not an improvement attributable specifically to AI.
AI is making these channels more conversational and task-oriented. Instead of searching through menus, customers can increasingly describe what they want to accomplish.
One of the clearest impacts of AI is the proliferation of virtual assistants and chat interfaces that empower customers to get things done on their own. From simple tasks, like checking a balance or paying a bill, to more complex actions like applying for a loan, AI has made self-service more convenient. A survey by Zendesk noted that self-service adoption in financial services has grown 5.4× in recent times, as banks provide more useful tools like searchable knowledge bases and intelligent chatbots.
Customers appreciate these improvements: about 75% say self-service is a convenient way to address issues, and 67% actually prefer self-service over speaking to a human rep.
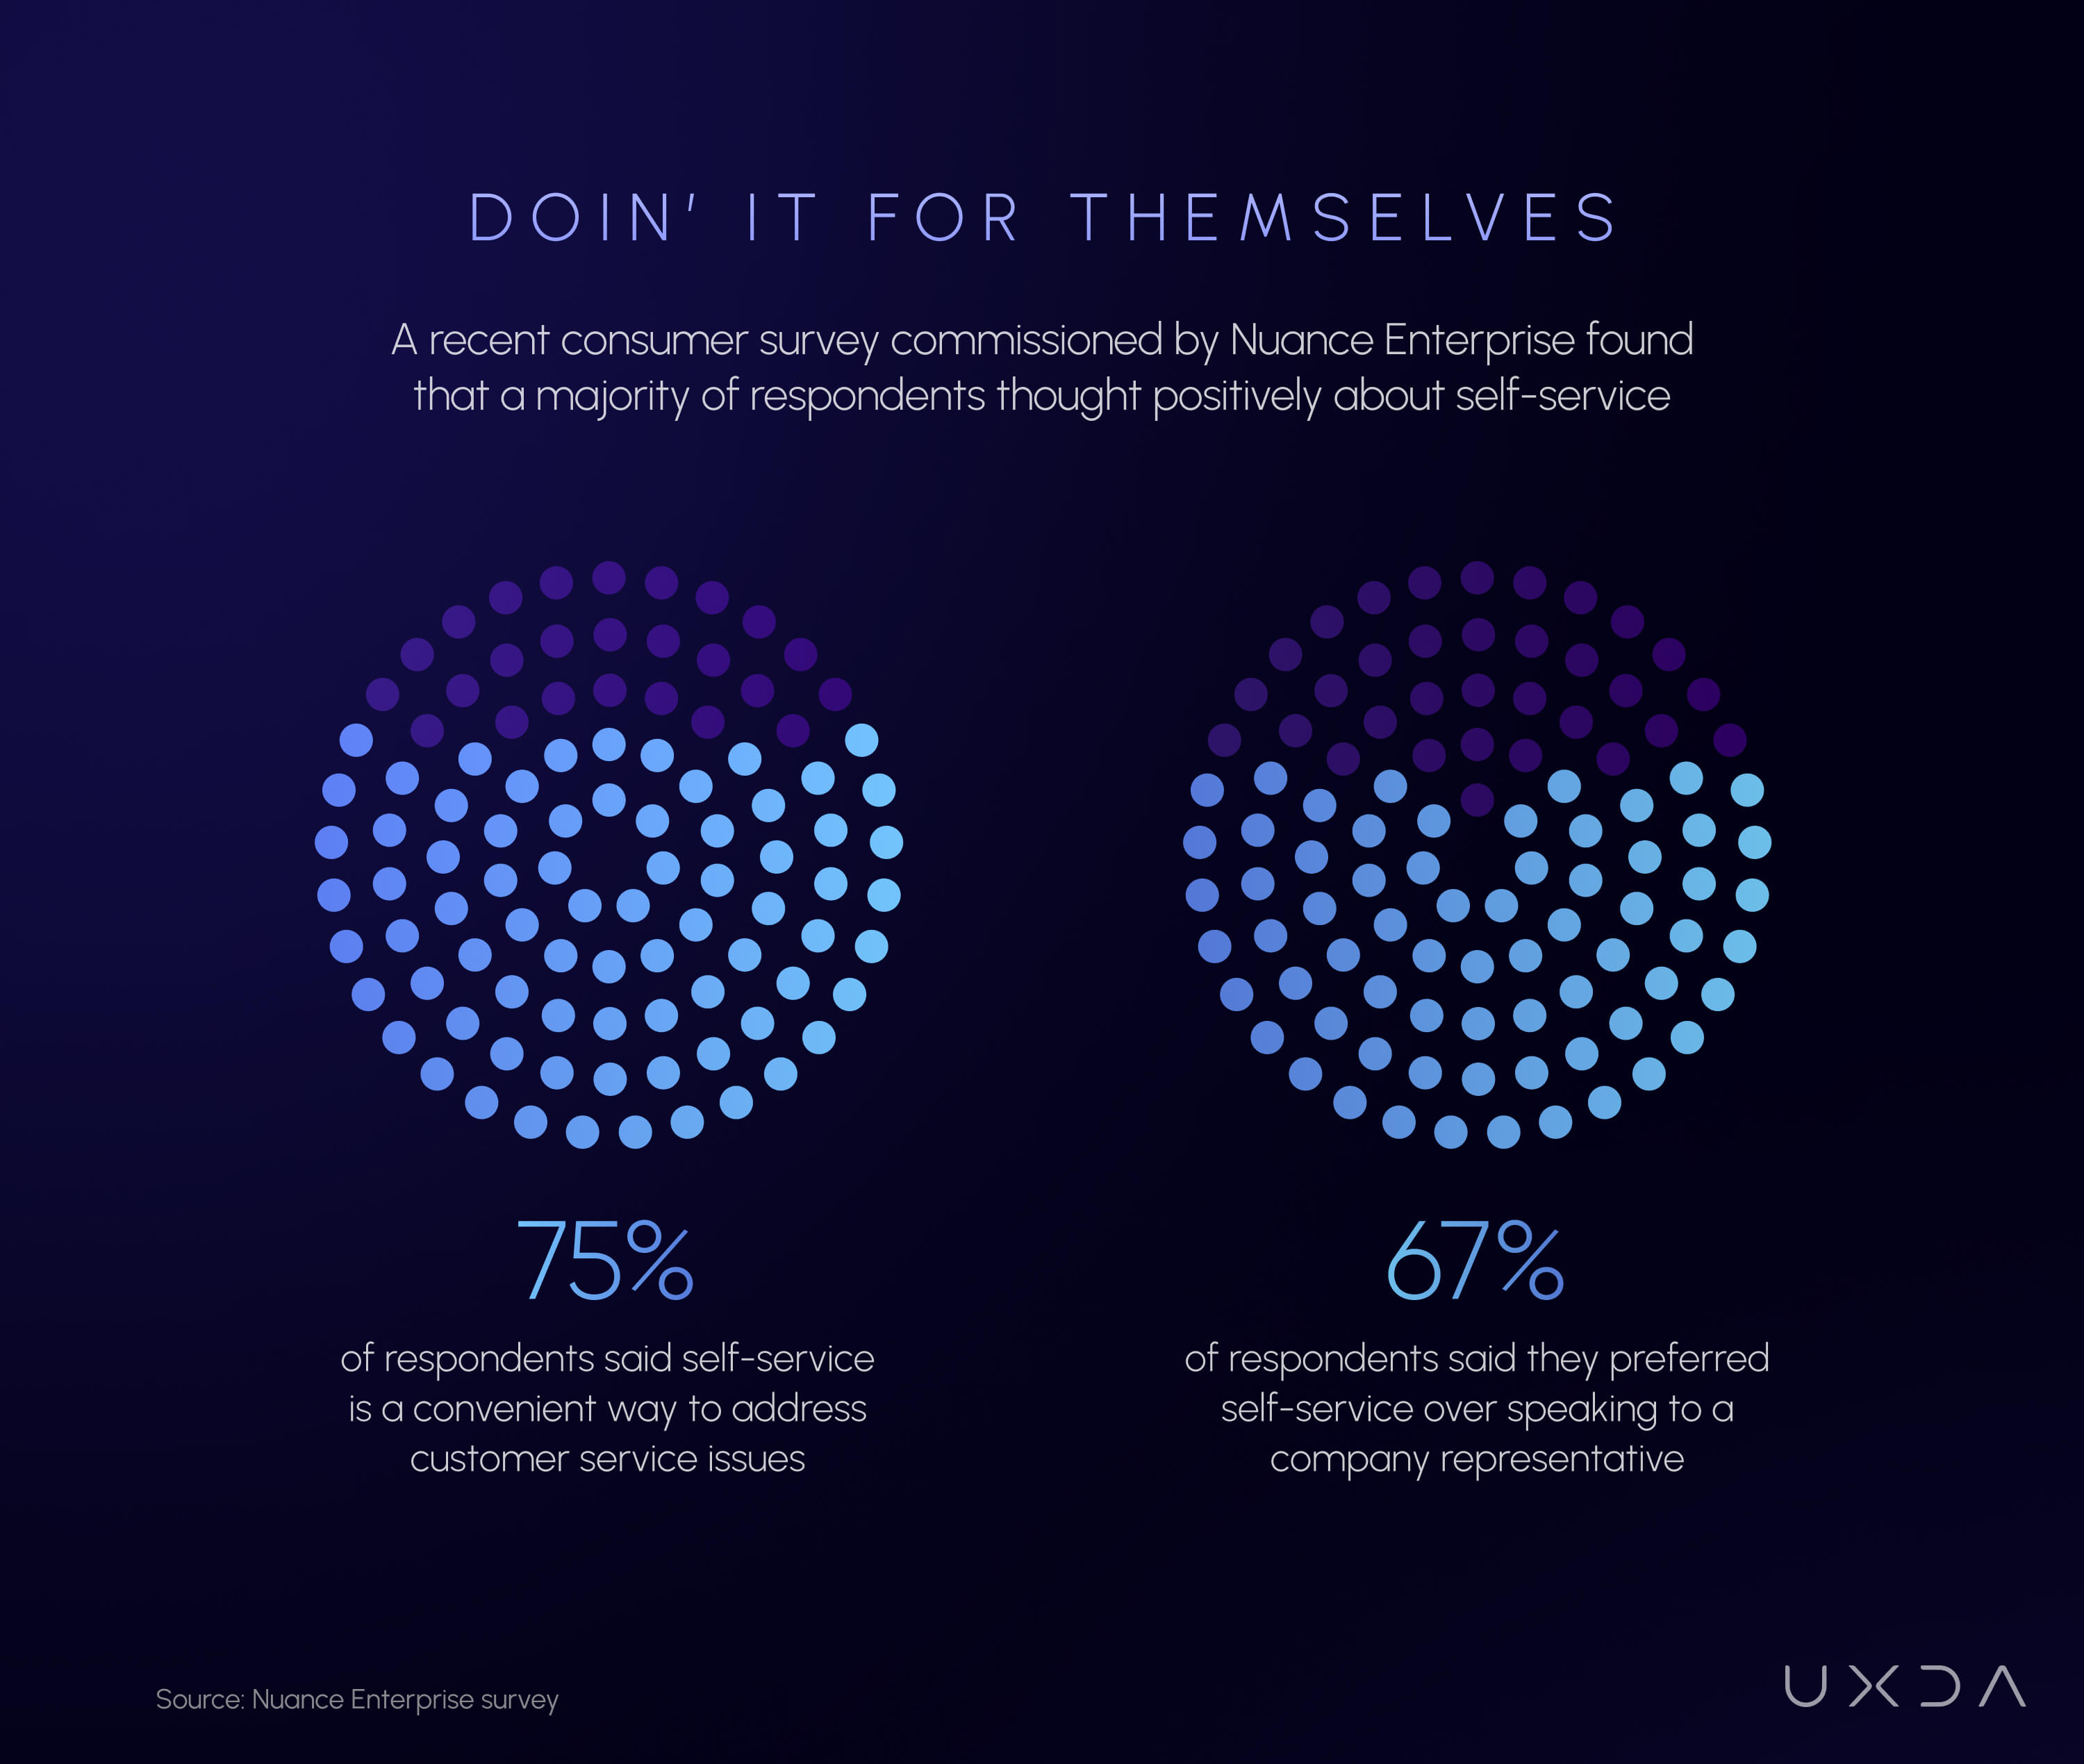 Source: Nuance Enterprise survey
Especially for tech-savvy segments (millennials and Gen Z), digital banking is the default—60% of millennials primarily use mobile banking apps as their main way to bank. In 2024, banks responded to this demand by expanding what customers can do without human intervention.
AI-powered chatbots and voice assistants played a dual role in boosting self-service. First, they act as 24/7 guides: an AI bot can understand a customer’s query in natural language and either provide the answer or walk the user through the steps to complete a task. Second, these bots leverage AI to handle multi-step requests that previously might have required an employee.
For example, Brazil’s Nubank (one of the largest digital banks) offers a self-service model in which customers can do “everything from paying a bill or raising their credit limit to setting travel notices” via the app. Over 80% of Nubank’s customers handle their needs through these digital self-service features without the need for additional support.
For example, Wells Fargo's Fargo assistant surpassed one billion cumulative interactions by March 2026, helping customers manage payments, transfers and everyday banking questions.
In the UK, NatWest's Cora handled 12.9 million customer conversations in 2025, with 50% requiring no human intervention. Generative AI-supported journeys achieved approximately 20 percentage points higher autonomous resolution rates than comparable conventional journeys.
These implementations demonstrate how AI can reduce service friction and increase the availability of self-service. However, automated interactions should not be confused with successful problem resolution.
Industry analysis estimated that bank chatbots will save around $7.3 billion globally in customer service costs, roughly $0.70 per interaction handled by AI instead of a human. Moreover, customers who get quick, effective answers on their own tend to be more satisfied. A survey by Zendesk in 2024 found 77% of consumers say AI is helpful for simple issues, indicating that when AI works, it meets customer expectations. However, it’s worth noting that AI self-service is not yet perfect.
The J.D. Power 2024 banking satisfaction study found that while overall satisfaction with big banks rose, the one area that saw a dip was when customers tried to contact the bank through self-service digital channels for help. This suggests that some banks’ self-service tools in 2024 still left a gap when customers had more detailed questions or problems. Banks are learning from this, enhancing their knowledge bases and making AI bots more context-aware so they can handle nuanced inquiries.
AI self-service improves customer experience when it helps customers accomplish their goals—not simply when it reduces contact with employees.
How Does AI Enable Proactive Banking
Proactive banking uses predictive AI to anticipate relevant financial needs, risks and opportunities before customers initiate an action. Instead of waiting for users to identify problems, banks can offer timely warnings, insights and recommended next steps.
For example, Bank of America reported 13.3 billion proactive alerts in 2025, helping customers monitor balances, payments and account activity. These notifications form part of the bank's broader digital engagement ecosystem and are not all necessarily generated by AI.
RBC's NOMI Forecast helps customers anticipate upcoming cash-flow changes, while Capital One's Eno provides notifications about unusual charges, duplicate payments and recurring subscriptions.
By analyzing customer data and context, AI allows banks to initiate contact at the right moment: sending a helpful tip, a security alert or a personalized offer exactly when it’s relevant. 70% of consumers value a consistent experience across channels, and AI helps achieve this by maintaining context across mobile apps, web and chat. A customer might start a task in a chatbot and finish in the app, or vice versa, with AI ensuring a seamless handoff.
AI also creates opportunities for more contextual financial assistance: identifying potential cash-flow shortages, suggesting savings opportunities or warning customers about suspicious transactions.
The challenge is ensuring that proactive engagement remains useful rather than intrusive. Excessive notifications and irrelevant recommendations can undermine trust.
The shift is from reactive banking UX to anticipatory banking UX—where financial institutions help customers recognize and address needs at the right moment.
How Is AI Changing Banking Customer Support
AI-powered banking customer support combines conversational interfaces, customer context and intelligent automation to resolve inquiries faster and make human assistance more effective.
Traditional chatbots primarily guided customers toward information. Newer generative AI assistants can interpret more complex requests, maintain conversational context and support selected financial tasks.
Bank of America's Erica surpassed 3.2 billion cumulative interactions by March 2026, including nearly 700 million interactions during 2025.
NatWest expanded generative AI across 21 Cora customer journeys by the end of 2025, improving the proportion of queries resolved without human intervention. Meanwhile, Lloyds Banking Group's Athena assistant reduced employee information search times by 66%, helping service teams retrieve relevant knowledge more efficiently.
These examples illustrate two complementary approaches: AI that helps customers directly and AI that assists employees behind the scenes.
As AI becomes more capable, successful customer support increasingly depends on accurate answers, contextual understanding, smooth escalation and human accountability.
The next stage of banking customer support is not simply answering more questions with AI, but resolving more customer problems through connected digital and human service.
How Can AI Make Digital Banking More Accessible and Inclusive
AI can improve digital banking accessibility by enabling customers to interact through natural language, voice, translation and simplified financial guidance. These capabilities can help reduce barriers created by complex navigation, unfamiliar terminology and language differences.
In 2026, Wells Fargo reported that more than 3 million Spanish-speaking customers had used Fargo, generating over 160 million interactions. This illustrates how conversational assistance can support more inclusive banking across languages.
Similarly, bunq supports AI-assisted app translation in 38 languages, helping customers access financial services in their preferred language.
AI can also support customers through voice interaction, text simplification, document recognition and more flexible ways to complete financial tasks.
However, AI does not replace accessible UX design. Banks must still meet established accessibility standards, including readable interfaces, screen-reader compatibility, keyboard navigation, clear language and predictable interactions. AI-generated responses and translations also require accuracy controls, particularly when financial information is involved.
The opportunity extends beyond supporting customers with disabilities. More inclusive interfaces can benefit older adults, non-native speakers, customers with limited financial literacy and anyone encountering difficult financial situations.
The strategic value of accessible AI is not simply making banking available to more people, but making financial services easier to understand, navigate and use with confidence.
Conclusion: What Can Banks Learn From AI Banking Case Studies
AI banking case studies demonstrate that artificial intelligence can create substantial value across financial services—but technology adoption alone does not guarantee competitive differentiation.
AI in banking has moved beyond experimentation. Banks worldwide are deploying artificial intelligence across fraud detection, personalization, customer support, financial guidance, self-service, risk management and employee workflows. Generative AI is accelerating this shift by allowing banks to move from predefined digital interactions toward more conversational, contextual and adaptive experiences.
Both in the United States and the United Kingdom, recent years was a breakthrough for artificial intelligence in banking. Virtually every major bank in every major market is now either using generative AI or actively planning to use it. They are motivated by clear benefits: better fraud detection, cost reductions, personalized customer experiences and by competitive pressure as fintech players and “AI-native” firms disrupt traditional banking. Surveys show upwards of 90% of bank executives in the US and UK have greenlit AI projects or increased budgets for GenAI, demonstrating strong confidence in the technology.
Going forward, the banking sector is expected to continue investing aggressively in AI capabilities. Analysts project exponential growth in AI spending by banks (e.g., global generative AI spending in banking could reach ~$85 billion by 2030). Key use cases like fraud detection, chatbots, credit scoring and algorithmic trading will become further enhanced by advanced AI. Banks will also likely collaborate with regulators to develop frameworks for responsible AI (as seen in the UK’s surveys) and address challenges like bias and transparency. In sum, banking’s early embrace of AI—now turbocharged by generative AI—is positioning the sector for significant transformation in the years ahead, outpacing many other industries in the AI adoption curve.
Recent years were pivotal for artificial intelligence in banking, as institutions worldwide moved from pilot projects to real deployments that tangibly improved the digital customer experience. Globally, banks observed that AI could boost both customer satisfaction and operational performance—a true win-win. By automating routine tasks and augmenting human employees, AI allowed banks to serve more customers with greater consistency.
Quantitatively, we saw metrics trend in the right direction: higher Net Promoter Scores in markets in which digital CX was strong, record digital adoption rates (with active digital users exceeding 75%–80% at many banks) and significant increases in self-service transactions and chatbot interaction counts. One Capgemini study even linked AI-driven CX improvements to double-digit gains in satisfaction and revenue, underscoring the financial payoff of more satisfied customers. Qualitatively, customers now enjoying more personalized, convenient and engaging banking services than ever before—from receiving tailored financial advice in-app to getting instant help from a friendly AI assistant at midnight. Use cases like generative AI chatbots went from novelty to mainstream, with major banks in the US and UK launching or refining such tools.
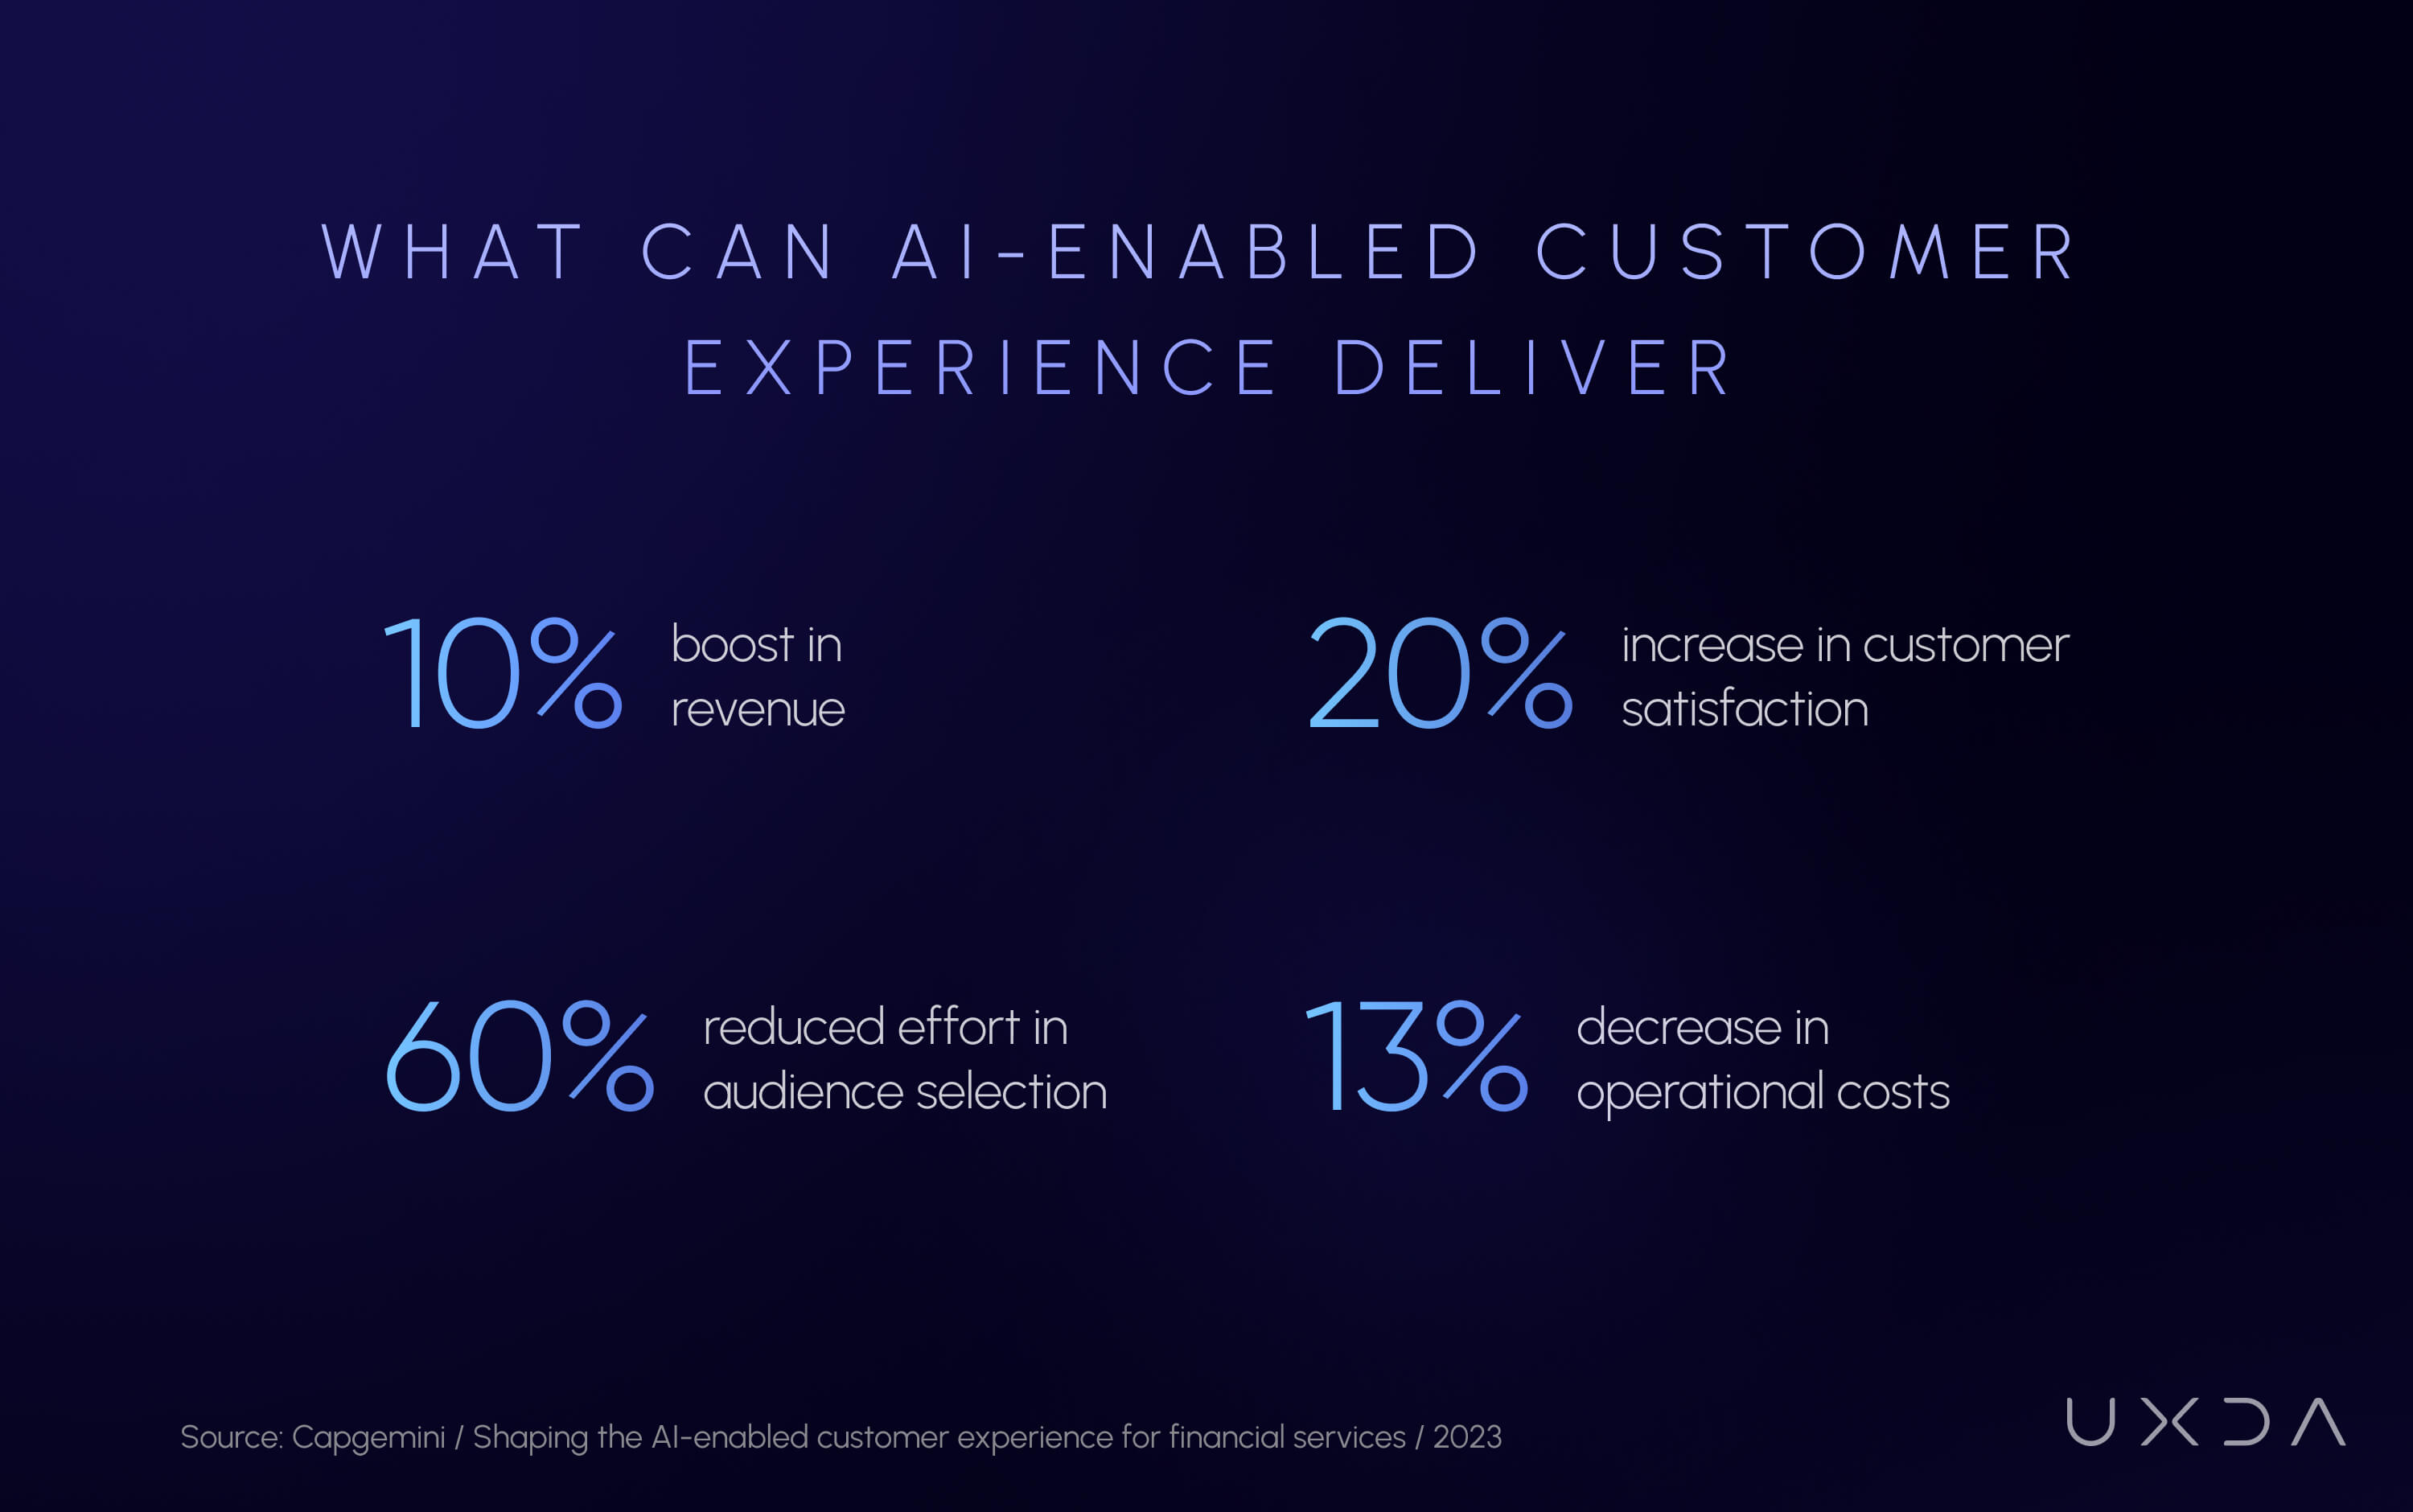 Source: Capgemini, Shaping the AI-enabled customer experience for financial services
Leading financial institutions are applying AI to prevent fraud, improve operational efficiency, personalize financial guidance and simplify customer interactions. Generative AI is accelerating this evolution by introducing more conversational, contextual and adaptive ways to access financial services. Yet the most important distinction is not between banks that have AI and those that do not. It is between institutions that simply deploy AI capabilities and those that use AI to fundamentally improve their customer experience.
For banking leaders, the strategic priorities are clear: identify the right customer problems, define meaningful experience outcomes, integrate AI across the broader financial journey and establish the governance needed to maintain quality and trust.
Banks had to address customer trust and security concerns around AI. Surveys revealed that while people welcomed convenience, many remained cautious about AI handling their finances: over 57% of customers hesitated to use AI-generated financial advice, and a minority outright refused to use AI for banking tasks. Incidents of AI errors (or “hallucinations”) were taken seriously, and institutions implemented guardrails and testing to maintain accuracy.
The human element also proved vital—leading banks found the best outcomes by combining AI efficiency with human empathy, ensuring that customers could seamlessly escalate to a person when needed. Regulatory and ethical considerations started to surface as well, prompting discussions on transparent AI algorithms and data privacy. Nonetheless, the overall impact is clearly positive.
Banks that embraced AI saw improved customer engagement, whether through more frequent app usage or deeper emotional connection (feeling that the bank “understands me”). In markets like the US and UK, which we highlighted, AI became a key differentiator among competitors: those who leveraged it wisely reaped reputational gains, while those who lagged faced pressure to catch up.
This represents a fundamental shift in digital banking UX. Traditional digital banking was largely built around interfaces, navigation and predefined journeys. Future AI in banking will enable experiences increasingly built around intent, context and outcomes. Instead of asking customers to learn how the bank works, the experience will adapt to what the customer is trying to accomplish.
But AI adoption alone does not guarantee better customer experience.
The same technology that can remove friction can also scale existing friction. If a bank automates a poorly designed process, personalizes an irrelevant proposition or deploys an AI assistant on top of a fundamentally broken journey, AI can make the problem faster, more pervasive and harder to see. The issue is not whether AI works. It is whether the bank is applying it to the right customer problem.
By delivering personalization at scale, enabling full-service banking at customers’ fingertips, engaging users in proactive conversations, automating support and broadening accessibility, AI made banking more customer-centric than ever. The past year’s advancements indicate that we are entering a new era of digital banking—one in which AI is embedded in every facet of the customer journey, often invisibly, making interactions smoother and more meaningful.
This makes UX diagnosis as important as AI deployment.
Before asking “Where can we use AI?”, banks should ask:
- What customer problem are we actually trying to solve?
- Is the problem supported by behavioral and UX research?
- Where does friction occur across the entire journey, rather than a single screen?
- What should be automated, and what should remain human?
- Will AI remove friction—or simply hide it?
- How will we measure whether the experience actually improved?
The competitive advantage of AI in banking will therefore not come simply from having more AI features. It will come from knowing where AI can create meaningful customer and business value—and integrating it into an experience system designed around those outcomes to ensuring it improves the experience rather than scaling existing friction.
This is where financial UX strategy becomes a critical part of AI transformation—ensuring that artificial intelligence strengthens customer relationships, differentiates digital financial experiences and creates sustainable business value.
AI in Banking: Frequently Asked Questions
What Is AI in Banking?
AI in banking is the use of artificial intelligence technologies to automate financial processes, analyze data, support decisions and improve customer experiences. Applications include fraud detection, credit assessment, virtual assistants, personalized financial guidance and operational automation.
What Are the Most Common AI Use Cases in Banking?
The most common AI banking use cases include fraud detection, risk management, customer service automation, credit scoring, financial personalization, predictive analytics and employee productivity. Generative AI is also expanding the use of conversational banking, intelligent assistants and automated financial workflows.
Which Banks Are Using Artificial Intelligence?
Leading financial institutions applying AI include JPMorgan Chase, Bank of America, Morgan Stanley, HSBC, DBS, Wells Fargo, NatWest and Commonwealth Bank of Australia. Their implementations range from internal AI copilots to customer-facing virtual assistants, fraud prevention and personalized financial services.
What Are Examples of Generative AI in Banking?
Generative AI banking examples include Morgan Stanley's advisor knowledge assistant, JPMorgan Chase's internal LLM Suite, Goldman Sachs' employee AI assistant and NatWest's work on AI-enabled customer support. These applications illustrate how large language models can support knowledge retrieval, employee productivity and conversational interactions.
How Does AI Improve Banking Customer Experience?
AI can improve banking customer experience by reducing service friction, enabling faster self-service, identifying financial risks, personalizing recommendations and providing contextual assistance. The benefits depend on how well AI capabilities are integrated into customer journeys and measured against real customer outcomes.
What Are the Benefits of AI in Banking?
The potential benefits include lower operating costs, faster service delivery, improved fraud detection, increased productivity, more personalized financial relationships and better decision support. The scale of these benefits depends on implementation maturity, data quality, governance and user adoption.
What Are the Main Challenges of AI Implementation in Banking?
Key challenges include customer trust, data privacy, model reliability, explainability, cybersecurity, regulatory compliance, integration with legacy systems and the risk of automating ineffective processes. Banks must also ensure that customers retain appropriate control over consequential financial decisions.
How Can Banks Measure the ROI of AI Implementation?
Banks should evaluate AI ROI through measurable outcomes such as task completion, first-contact resolution, cost-to-serve, fraud losses prevented, processing times, customer satisfaction, conversion rates and retention. AI interaction volume and feature adoption alone are insufficient measures of transformation success.
How Will AI Change the Future of Digital Banking?
AI is expected to shift digital banking from predominantly reactive self-service toward more proactive, conversational and increasingly agentic financial assistance. Instead of requiring customers to navigate predefined journeys, banks may increasingly support customers through intent-based interactions, contextual recommendations and authorized task execution.
Why Is UX Strategy Important for AI in Banking?
UX strategy helps banks determine where AI can create meaningful customer and business value before implementation. By identifying customer needs, journey friction and experience requirements, financial institutions can avoid introducing AI features that add complexity or automate poorly designed processes.
Discover our clients' next-gen financial products & AI innovations in UXDA's latest showreel:
Make AI a Strategic Advantage for Your Financial Institution
AI creates competitive advantage when it transforms the financial customer experience—not when it becomes just another feature. UXDA partners with banks and financial institutions to define human-centered AI experience strategies, identify high-value customer opportunities and shape differentiated digital experiences.
From AI-enabled banking journeys to proactive financial assistance and conversational experiences, we help financial leaders translate technological possibilities into meaningful customer and business value.
- E-mail us at info@theuxda.com
- Chat with us in Whatsapp
- Send a direct message to UXDA's CEO Alex Kreger on Linkedin