

Banking customer experience strategy is the strategic approach financial institutions use to align customer needs, business objectives, digital products, service delivery and brand identity to create measurable customer and business value. It connects how customers experience the bank with how the institution grows, differentiates, operates and builds long-term relationships. The challenge is not just to make banking easier. It is to turn customer experience into a competitive advantage that competitors cannot easily replicate.
For banking executives, customer experience is no longer simply a matter of satisfaction or digital usability. It influences customer acquisition, product adoption, retention, operational efficiency, trust and profitability. Yet many financial institutions continue to invest millions in digital transformation without creating experiences that customers perceive as meaningfully different.
Drawing on UXDA's experience across more than 150 financial products in 39 countries, this article explores how banks can connect CX strategy, financial UX, Digital Brand Identity and experience governance to improve business performance and create lasting differentiation.
Why Is Customer Experience a Strategic Growth Driver for Banks
Customer experience has become a competitive factor in banking because digital channels increasingly determine how customers evaluate, use and trust financial services. Customers compare banks not only by interest rates, fees and product availability, but also by how easily they can manage their finances, make decisions and achieve their goals.
We all have witnessed how quickly markets can shift when a more compelling digital experience arrives:
- Netflix’s streaming overtook Blockbuster’s rental model.
- Apple’s iPhone disrupted Nokia and BlackBerry.
- Facebook and Twitter outpaced traditional media.
- Google left Yahoo behind in searches.
- Zoom outperformed Skype in video calls.
- Uber challenged traditional taxis.
- Amazon reshaped retail with customer focus.
- iTunes and Spotify transformed music consumption.
Finance faces the same reality: bold, user-first design delivered through seamless digital platforms is what separates the leaders from those destined to become footnotes.
For financial institutions, this creates three strategic challenges:
- Functional commoditization: Similar banking features, technologies and platforms make it increasingly difficult to differentiate through functionality alone.
- Experience fragmentation: Disconnected products, channels, teams and service processes create friction that undermines trust and operational efficiency.
- The promise–experience gap: Banks invest in brand positioning and digital innovation, but customers may still encounter generic, complicated or inconsistent experiences.
The strategic opportunity is to transform CX from a collection of isolated service improvements into a coherent system that strengthens customer relationships, improves business outcomes and makes the financial brand meaningfully distinctive.
1. From Mobile Banking Apps to the Entire Banking Experience
Mobile banking has become a central point of interaction between financial institutions and their customers. However, improving the mobile app alone does not guarantee a better banking customer experience.
Customers experience the bank across account opening, payments, lending, investments, notifications, support, AI assistants and physical interactions. When these services operate independently, even a well-designed app can become part of a fragmented customer relationship.
Bank-as-a-Product is a strategic approach that treats the entire banking experience as one continuously evolving product ecosystem rather than a collection of disconnected features, channels and projects.
For banks, this means establishing a shared experience vision that connects customer journeys, product strategy, service operations, technology and Digital Brand Identity. The objective is not simply to deliver more digital functionality, but to create one coherent banking experience that customers can recognize, understand and trust.
2. Digital Transformation Does Not Automatically Improve Banking CX
Digital transformation can modernize banking infrastructure without fundamentally improving the customer experience. A new core banking platform, mobile application or AI capability may increase technical capacity while leaving the underlying customer journey, service complexity and institutional fragmentation largely unchanged.
This happens when technology decisions precede a clear definition of the experience the bank wants to deliver.
Financial institutions risk digitizing existing friction rather than eliminating it. Complicated approval processes become digital forms, disconnected departments become fragmented app sections, and generic platform capabilities produce experiences that are difficult to distinguish from competitors.
EPAM research (2020) shows 63% of people choose their primary bank based on trust. But trust isn’t earned by just having a mobile-friendly app. A customer-centered transformation starts by defining the desired customer and business outcomes, validating critical journeys and establishing experience requirements before committing to major technology and implementation decisions.
Technology should enable the intended customer experience—not determine it by default.
3. AI Transform Banking Customer Experience
AI in banking is shifting digital customer experience from reactive self-service toward more contextual, proactive and increasingly agentic financial assistance.
Traditional digital banking requires customers to identify what they need, locate the right service and complete the process themselves. AI-powered experiences can increasingly interpret customer intent, explain financial information, identify relevant opportunities, reduce administrative work and support the execution of financial tasks.
If you’re not yet using AI, machine learning or personalized insights, you’re already falling behind. According to a McKinsey report (2022), companies using AI-driven personalization have seen up to a 15% boost in customer engagement and a 10-20% increase in cross-sell revenue. The right technology understands what customers need and delivers solutions that truly make their lives easier—whether that’s faster loan approvals or budgeting tips tailored just for them.
The greatest CX opportunities extend beyond conversational chatbots:
- Contextual financial assistance: Explaining spending patterns, cash flow, financial changes and relevant next steps.
- Proactive banking: Anticipating potential financial needs and offering timely, relevant guidance.
- Intelligent journey orchestration: Simplifying onboarding, service requests, lending and other complex processes.
- Personalized financial decision support: Helping customers understand options, trade-offs and potential consequences.
- Agentic banking: Supporting or executing authorized multi-step activities under clearly defined permissions and controls.
However, greater automation does not automatically create a better customer experience. Financial institutions must design for transparency, explainability, customer control, privacy, security and appropriate human intervention.
The strategic question is no longer whether a bank should add AI. It is how AI can create meaningful customer value while strengthening trust and the bank's distinctive experience.
4. Digital Brand Identity Differentiate Banking Customer Experience
Digital Brand Identity in banking is the consistent expression of a financial institution's strategy, personality and brand promise through its digital experiences. It includes visual language, interactions, content, tone of voice, personalization, service behavior and the way customer journeys are designed.
Traditional branding communicates what a financial institution wants customers to believe. Digital experience demonstrates whether that promise is credible.
A bank can position itself as innovative, customer-centered or premium, but those qualities must become visible through actual customer interactions. If a bank promises simplicity while requiring complicated processes, or promotes personalization while delivering generic experiences, the digital product contradicts its positioning.
For financial institutions competing with increasingly similar products and technologies, Digital Brand Identity creates an opportunity to differentiate not only through what services they provide, but through how those services behave and feel.
Customers experience the truth of a financial brand through its digital behavior—not simply through its communication.
5. Banking CX Require Continuous Experience Governance
Banking customer experience cannot be transformed through a one-time redesign. As financial institutions introduce new products, channels, technologies and service models, the experience must evolve without losing consistency, usability or strategic direction.
Experience governance establishes the principles, standards, decision-making processes and accountability needed to maintain customer experience quality across the organization.
Without governance, individual teams may optimize their own products while gradually fragmenting the overall banking experience. Inconsistent navigation, terminology, service logic, interaction patterns and communication can accumulate into experience debt that becomes increasingly expensive to correct.
UXDA's Digital Experience Governance (DXG) system connects strategy, market understanding, services, ecosystem alignment and governance to help financial institutions translate their intended Digital Brand Identity into coherent customer experiences over time.
For banking leaders, governance turns CX from a series of design projects into an institutional capability that can be measured, protected and continuously improved.
6. Emotional Experience Influence Banking Engagement
Banking customer experience is not purely functional. Financial decisions involve uncertainty, confidence, aspiration, security and personal progress. A well-designed experience should help customers feel informed, supported and in control.
UXDA's Dopamine Banking approach explores how emotionally engaging digital experiences can make financial interactions more motivating and rewarding.
This can include clear progress toward savings goals, meaningful recognition of financial milestones, reassuring feedback after important transactions and personalized communication that reflects customer needs.
However, emotional engagement must serve genuine customer value. Gamification and behavioral design should support financial well-being, informed decisions and long-term trust—not encourage unnecessary transactions or manipulative engagement.
The goal is to transform financial interactions from purely transactional tasks into experiences that customers find useful, understandable and personally meaningful.
“These days, your financial brand is only as good as your digital product.”
What Is the Business Cost of Poor Banking Customer Experience
According to Gitnux (2025), a striking 70% of banking customers say they would switch banks for better service, and nearly half—48%—would leave because of poor digital experiences. This shows that a quick “design fix” or simple “interface update” won’t cut it anymore. Winning and keeping customers, and building true loyalty, all hinge on delivering a user experience that’s seamless, intuitive and genuinely valuable. UX isn’t just a detail—it’s a business-critical factor that directly impacts your bottom line.
In today’s world, digital presence is a key brand representation. If your app feels clunky, outdated or confusing, that’s exactly how people will view your entire bank. But when you invest in a digital experience that lives up to your brand’s promise, you turn casual users into passionate advocates. Strong, familiar financial brands no longer have a free pass—customers now have competitors just a tap away, eager to win them over with better experiences, more engaging service and genuine emotional connections.
With neobanks and Fintech disruptors setting a new standard for speed, simplicity and design, traditional banks no longer have the luxury of complacency. And the stakes are high: 89% of customers would switch to a competitor after a poor experience, according to Oracle.
Here’s the real issue—many banks are misdiagnosing the problem. They blame weak conversions or shrinking loyalty on branding or marketing missteps. But more often than not, the root cause is a clunky, frustrating digital experience that wasn’t built with real user needs in mind.
Traditional banks often rely on outdated technology stacks and legacy systems that are difficult to overhaul. The approach to UX becomes reactive rather than proactive. Designers are hired to “fix the interface,” while the deeper issues—process inefficiencies, policy bottlenecks, brand erosion, product ecosystem inconsistency and a lack of strategic vision—remain unaddressed.
But when your competition is a digital-native neobank that’s hyper-focused on delivering intuitive, frictionless experiences, that gap becomes glaring. Consider these telling numbers from McKinsey research (2023):
- Organizations that improved Customer Experience (CX) by at least 20% saw a 5-10% boost in share of wallet.
- Companies that are leaders of CX achieved more than double the revenue growth of “CX laggards” between 2016 and 2021.
Poor banking customer experience creates financial consequences across the customer lifecycle. Friction in onboarding can reduce acquisition, confusing journeys can weaken product adoption, fragmented self-service can increase operating costs, and inconsistent digital interactions can undermine trust and retention.
The business case for CX transformation should therefore be built around measurable improvements in customer behavior and institutional performance—not simply better usability scores or more attractive interfaces.
| CX problem | Business consequence | Measurement |
|---|---|---|
| Complicated onboarding | Lost customer acquisition | Application completion, abandonment |
| Confusing product journeys | Lower product adoption | Activation and conversion |
| Fragmented self-service | Higher operating costs | Cost-to-serve, avoidable calls |
| Poor service recovery | Weaker trust and retention | Complaints, churn |
| Generic digital experience | Weak differentiation | Preference, consideration, win/loss |
| Inconsistent ecosystem | Lower engagement and cross-product usage | Active usage, multi-product adoption |
How Does Banking CX Strategy Improve Business Performance
Banking customer experience strategy drives business performance by improving how financial institutions acquire, activate, engage and retain customers while reducing operational friction and strengthening competitive differentiation. When aligned with business objectives, CX becomes more than a measure of customer satisfaction—it becomes a strategic driver of sustainable growth and profitability.
The business value of better banking CX extends across five interconnected areas:
1. Customer Acquisition: Turn Interest Into Active Relationships
Clear, intuitive onboarding and account-opening journeys reduce unnecessary friction, helping more prospective customers complete applications and become active customers. Improving journey completion can increase acquisition efficiency without requiring proportional growth in marketing investment.
2. Product Activation and Engagement: Turn Access Into Value
Acquiring customers creates limited value if they never meaningfully use the bank's products. Relevant, personalized and intuitive digital experiences help customers discover financial services, activate products and integrate them into their financial lives. Greater product adoption creates opportunities for stronger engagement and deeper customer relationships.
3. Customer Retention: Reduce Friction That Drives Customers Away
Consistent, reliable and trustworthy banking experiences can reduce customer frustration and avoidable churn. By simplifying everyday interactions, resolving service issues and supporting customers at critical financial moments, banks can strengthen loyalty and protect the long-term value of existing relationships.
4. Operational Efficiency: Reduce the Cost of Serving Customers
Poorly designed journeys generate repeated requests, failed transactions, avoidable support contacts and manual intervention. Effective banking CX simplifies processes, improves digital self-service and reduces unnecessary operational complexity, potentially lowering cost-to-serve while improving service quality.
5. Customer Lifetime Value and Differentiation: Build Relationships That Last
Banks that deliver distinctive, relevant and consistently valuable experiences have greater opportunities to deepen customer relationships, support appropriate cross-product adoption and increase customer lifetime value. When these experiences express the bank's Digital Brand Identity, they also help establish competitive differentiation beyond products, rates and features.
From Better Experiences to Measurable Business Value
The financial impact of banking CX transformation follows a connected value chain:
CX Strategy and Experience Improvements
Customer Insight → Journey Design → Digital Brand Identity → Experience Governance
Customer Behavior Improvements
Higher Acquisition → Greater Product Activation → Stronger Retention → More Efficient Self-Service
Measurable Business Outcomes
Revenue Growth → Cost Efficiency → Higher Customer Lifetime Value → Stronger Competitive Position
For banking leaders, the essential distinction is between experience quality, customer behavior and financial outcomes. Better usability or satisfaction alone does not prove business value. The impact of CX investments must be validated through changes in customer acquisition, product adoption, retention, cost-to-serve and profitability.
The strategic value of banking CX is not simply creating better digital experiences. It is turning those experiences into measurable customer and business value.
Who Should Own Banking Customer Experience Strategy
Banking CX strategy requires executive ownership because the customer experience crosses organizational boundaries that no single design or product team controls.
The CEO and executive committee should establish customer experience as a strategic priority linked to business performance. Digital, product and experience leaders should translate that ambition into customer journeys, product priorities and experience principles. Technology, operations, risk and compliance leaders must ensure the intended experience can be delivered responsibly and efficiently.
A mature CX operating model establishes shared outcomes, clear decision rights, cross-functional accountability and continuous measurement.
The goal is not to make every executive responsible for interface design. It is to ensure that the entire institution is accountable for the experience it creates.
| Leadership | CX responsibility |
|---|---|
| CEO / Executive Committee | Strategic ambition, investment and accountability |
| Chief Digital / Experience Officer | CX strategy and cross-channel coherence |
| Product Leadership | Journey performance and adoption |
| CIO / CTO | Technology enablement and integration |
| Operations | Service efficiency and delivery |
| Risk / Compliance | Trust, protection and regulatory requirements |
How to Build a Banking CX Strategy: Ten Strategic Questions
CX strategy is the decision-making foundation; UX design, journey optimization, AI implementation and design systems are means of executing that strategy.
Modern financial brands aren’t built on logos—they’re built on digital experiences. We live in a world in which Amazon sets convenience standards, Netflix defines personalization, and Apple leads in intuitive design. Customers expect the same seamless, on-demand experience from their banks. Fail to deliver, and you can lose more than customers—you can lose trust, reputation and revenue.
Unlike isolated UX improvements or digital channel redesigns, a comprehensive banking CX strategy guides how products, journeys, technologies, services and teams work together to deliver one coherent banking experience. Its ultimate purpose is to turn customer understanding into meaningful differentiation, stronger customer relationships and measurable business value.
1. Business Strategy Alignment
Strategic question: What business outcomes should the digital experience enable?
A financial institution must establish how digital CX contributes to its strategic priorities: profitable growth, acquisition, product adoption, retention, operational efficiency, market expansion or repositioning.
This requires clear alignment between business goals and customer experience objectives.
Typical deliverables include CX business objectives, strategic priorities, value drivers and investment criteria.
UXDA perspective: Digital experience is not an isolated design discipline. It should enable the bank's business strategy.
2. Customer Understanding and Segmentation
Strategic question: Who are our customers, and what genuinely matters to them?
Effective CX strategy requires evidence about customer needs, behaviors, financial motivations, frustrations, trust concerns and life circumstances.
This includes qualitative research, behavioral analytics, customer segmentation, jobs-to-be-done, service feedback and customer journey analysis.
Typical deliverables include priority segments, customer needs, behavioral insights, unmet needs and experience opportunities.
Global best practice: McKinsey emphasizes an end-to-end view of banking journeys rather than optimizing individual touchpoints or organizational silos.
3. Market Positioning and Competitive Differentiation
Strategic question: What distinctive value can we offer that competitors do not?
Banks need to understand category expectations, competitors' experience models, emerging customer behaviors and opportunities competitors have overlooked.
The goal is not simply to achieve competitive parity but to identify where the bank can establish meaningful differentiation.
Typical practices include competitive experience benchmark, category conventions, differentiation opportunities and experience positioning.
UXDA perspective: Copying competitors' interfaces and features may improve functional parity without establishing a reason for customers to prefer the institution.
4. CX Vision and North Star
Strategic question: What future customer experience are we committed to creating?
A CX vision articulates the role the financial institution intends to play in customers' lives and establishes a shared direction for products, channels, services and future investments.
It should be ambitious, differentiated, achievable and understandable across the organization.
Typical deliverables include CX vision statement, North Star experience, future-state concept and strategic experience priorities.
Global best practice: Forrester's January 2026 CX vision guidance emphasizes visions that are authentic, rooted in brand identity and capable of mobilizing employees toward consistent delivery.
5. Digital Brand Identity
Strategic question: How should customers recognize and experience our bank's unique identity?
Digital Brand Identity translates brand strategy into recognizable digital behavior, defining how the bank communicaes, guides decisions, explains financial complexity, responds to customer needs and creates emotional engagement.
It goes beyond visual consistency to establish an experience that is distinctive in both appearance and behavior.
Typical deliverables include Digital Brand Identity direction, experience personality, tone of voice, behavioral characteristics and differentiating experience attributes.
UXDA distinction: This is one of the strongest areas where UXDA goes beyond conventional journey optimization. Brand differentiation should become tangible through the customer experience—not remain confined to advertising and visual identity.
6. Experience Principles and Standards
Strategic question: What rules should guide every customer experience decision?
Experience principles translate the strategic vision and Digital Brand Identity into actionable criteria.
For example, a bank pursuing financial confidence might adopt principles such as:
- Make financial complexity understandable.
- Give customers control before consequential decisions.
- Provide guidance when it is relevant.
- Maintain continuity across channels.
- Build trust through transparency and predictable behavior.
Typical deliverables include strategic experience principles, customer interaction standards, service behavior guidelines and design decision criteria.
Principles should be specific enough to help teams resolve competing requirements.
7. Journey and Ecosystem Strategy
Strategic question: Which experiences must we transform, and how should they connect?
The strategy must identify the journeys that most influence customer value, commercial performance and operational efficiency.
This includes defining future-state journeys, ecosystem relationships, digital service architecture, cross-channel continuity and transformation priorities.
Typical deliverables include journey portfolio, priority experience transformations, target ecosystem, experience architecture and roadmap.
UXDA perspective: Bank-as-a-Product means managing the entire banking experience as one coherent system rather than a collection of independently optimized apps, services and touchpoints.
8. Technology, Data and AI Experience Strategy
Strategic question: Which technologies will enable our intended customer experience?
Technology should support the intended experience—not define it by default.
This element establishes the strategic role of AI, personalization, automation, customer data, channel integration and emerging service models.
It should also define appropriate boundaries for automation, human intervention, transparency and customer control.
A typical approach includes technology-enabled CX opportunities, AI experience principles, personalization strategy, integration requirements and capability priorities.
UXDA perspective: Introducing AI is not the strategy. The strategy defines how intelligent capabilities transform the customer relationship and create differentiated value.
9. CX Measurement and Business Value
Strategic question: How will we know that the experience is creating value?
A mature digital CX strategy connects three levels of measurement:
- Experience quality: Task success, ease of use, customer effort, trust
- Customer behavior: Journey completion, activation, adoption, retention
- Business performance: Revenue, cost-to-serve, customer lifetime value, profitability
Typical practices include CX KPI framework, baseline, targets, measurement approach and business value model.
Global best practice: McKinsey recommends combining operational and customer feedback data rather than relying on broad satisfaction indicators alone.
10. Experience Governance and Organizational Alignment
Strategic question: How will we protect and continuously improve the experience over time?
Without governance, even a strong CX strategy can fragment as different teams, vendors, products and channels evolve.
Experience governance establishes accountability, decision rights, standards, quality controls and continuous improvement mechanisms.
Typical practices include CX governance model, cross-functional ownership, decision framework, experience standards and monitoring processes.
UXDA perspective: The DXG system is designed to connect Strategy, Market, Services, Ecosystem and Governance so a financial institution's Digital Brand Identity remains coherent through ongoing transformation.
Banking CX Transformation in Practice: Emirates NBD
A practical example of connecting customer experience with digital transformation is UXDA's work with Emirates NBD. The challenge extended beyond interface modernization: the institution needed a coherent digital experience that could express its new CX strategy across a complex banking ecosystem.
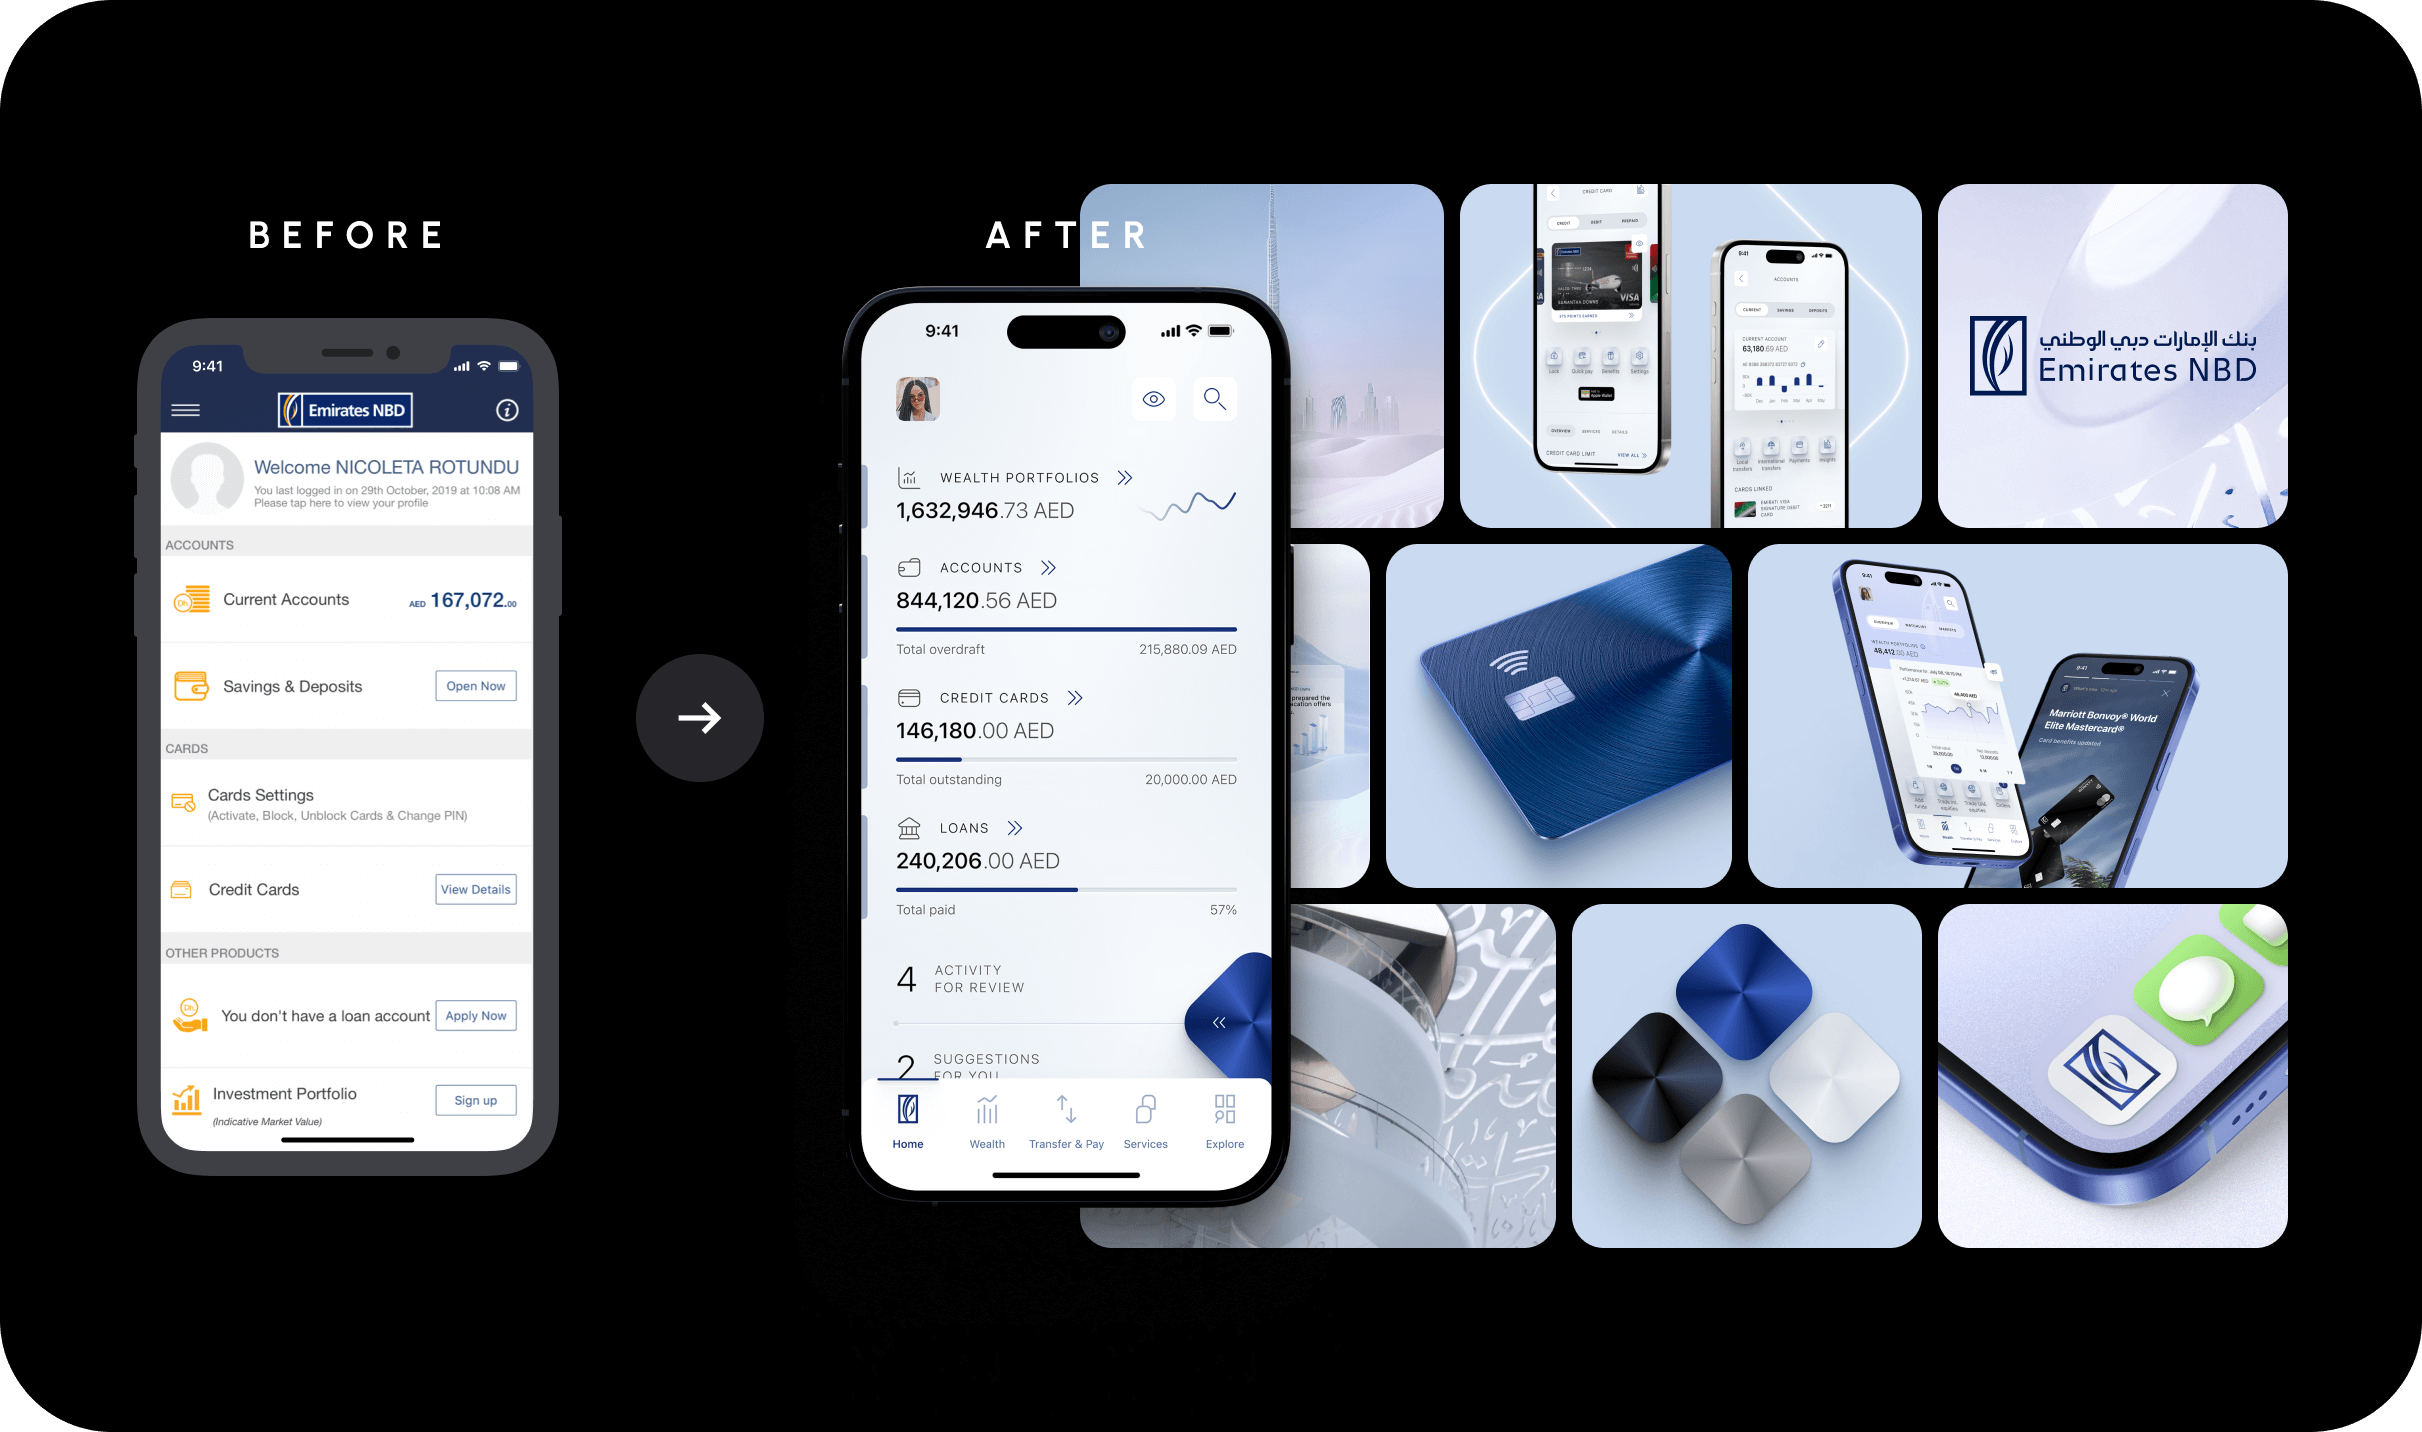
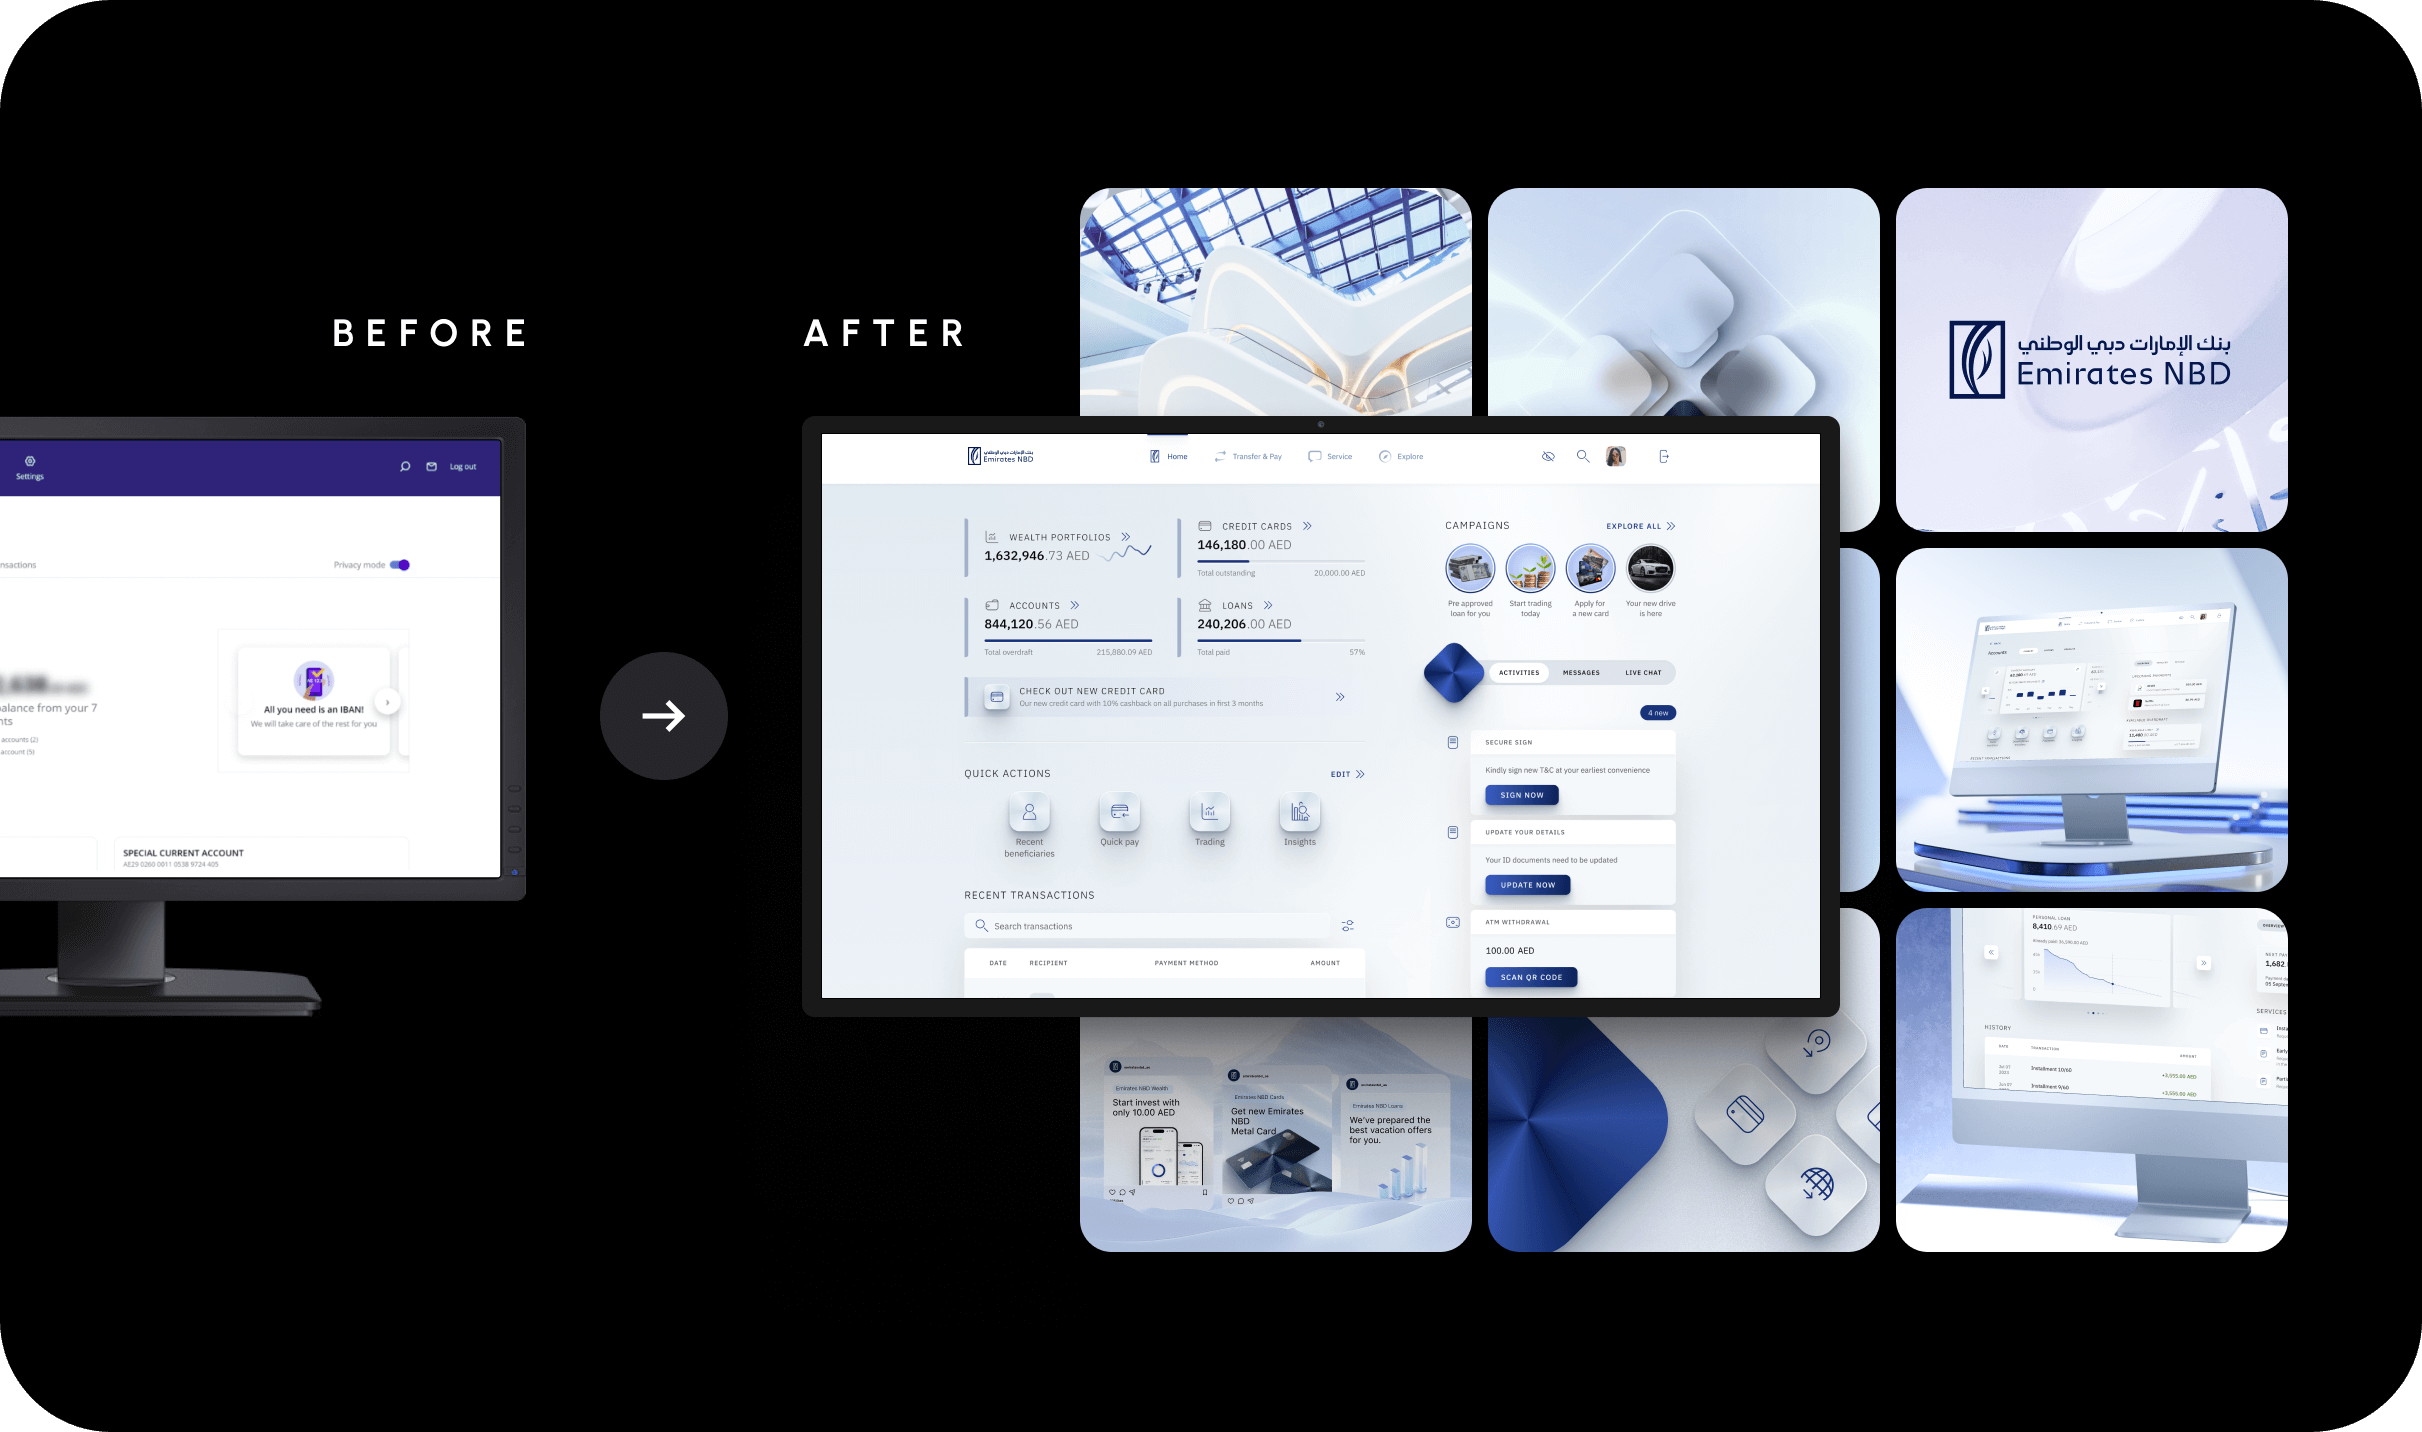
UXDA's strategic approach connected brand positioning, financial UX and digital experience principles to help establish a more consistent and distinctive experience across digital services.
The wider ENBD X transformation has been associated with significant reported outcomes, including 91% digital adoption, a 50% increase in transaction activity and an app rating improvement from 2.0 to 4.7.
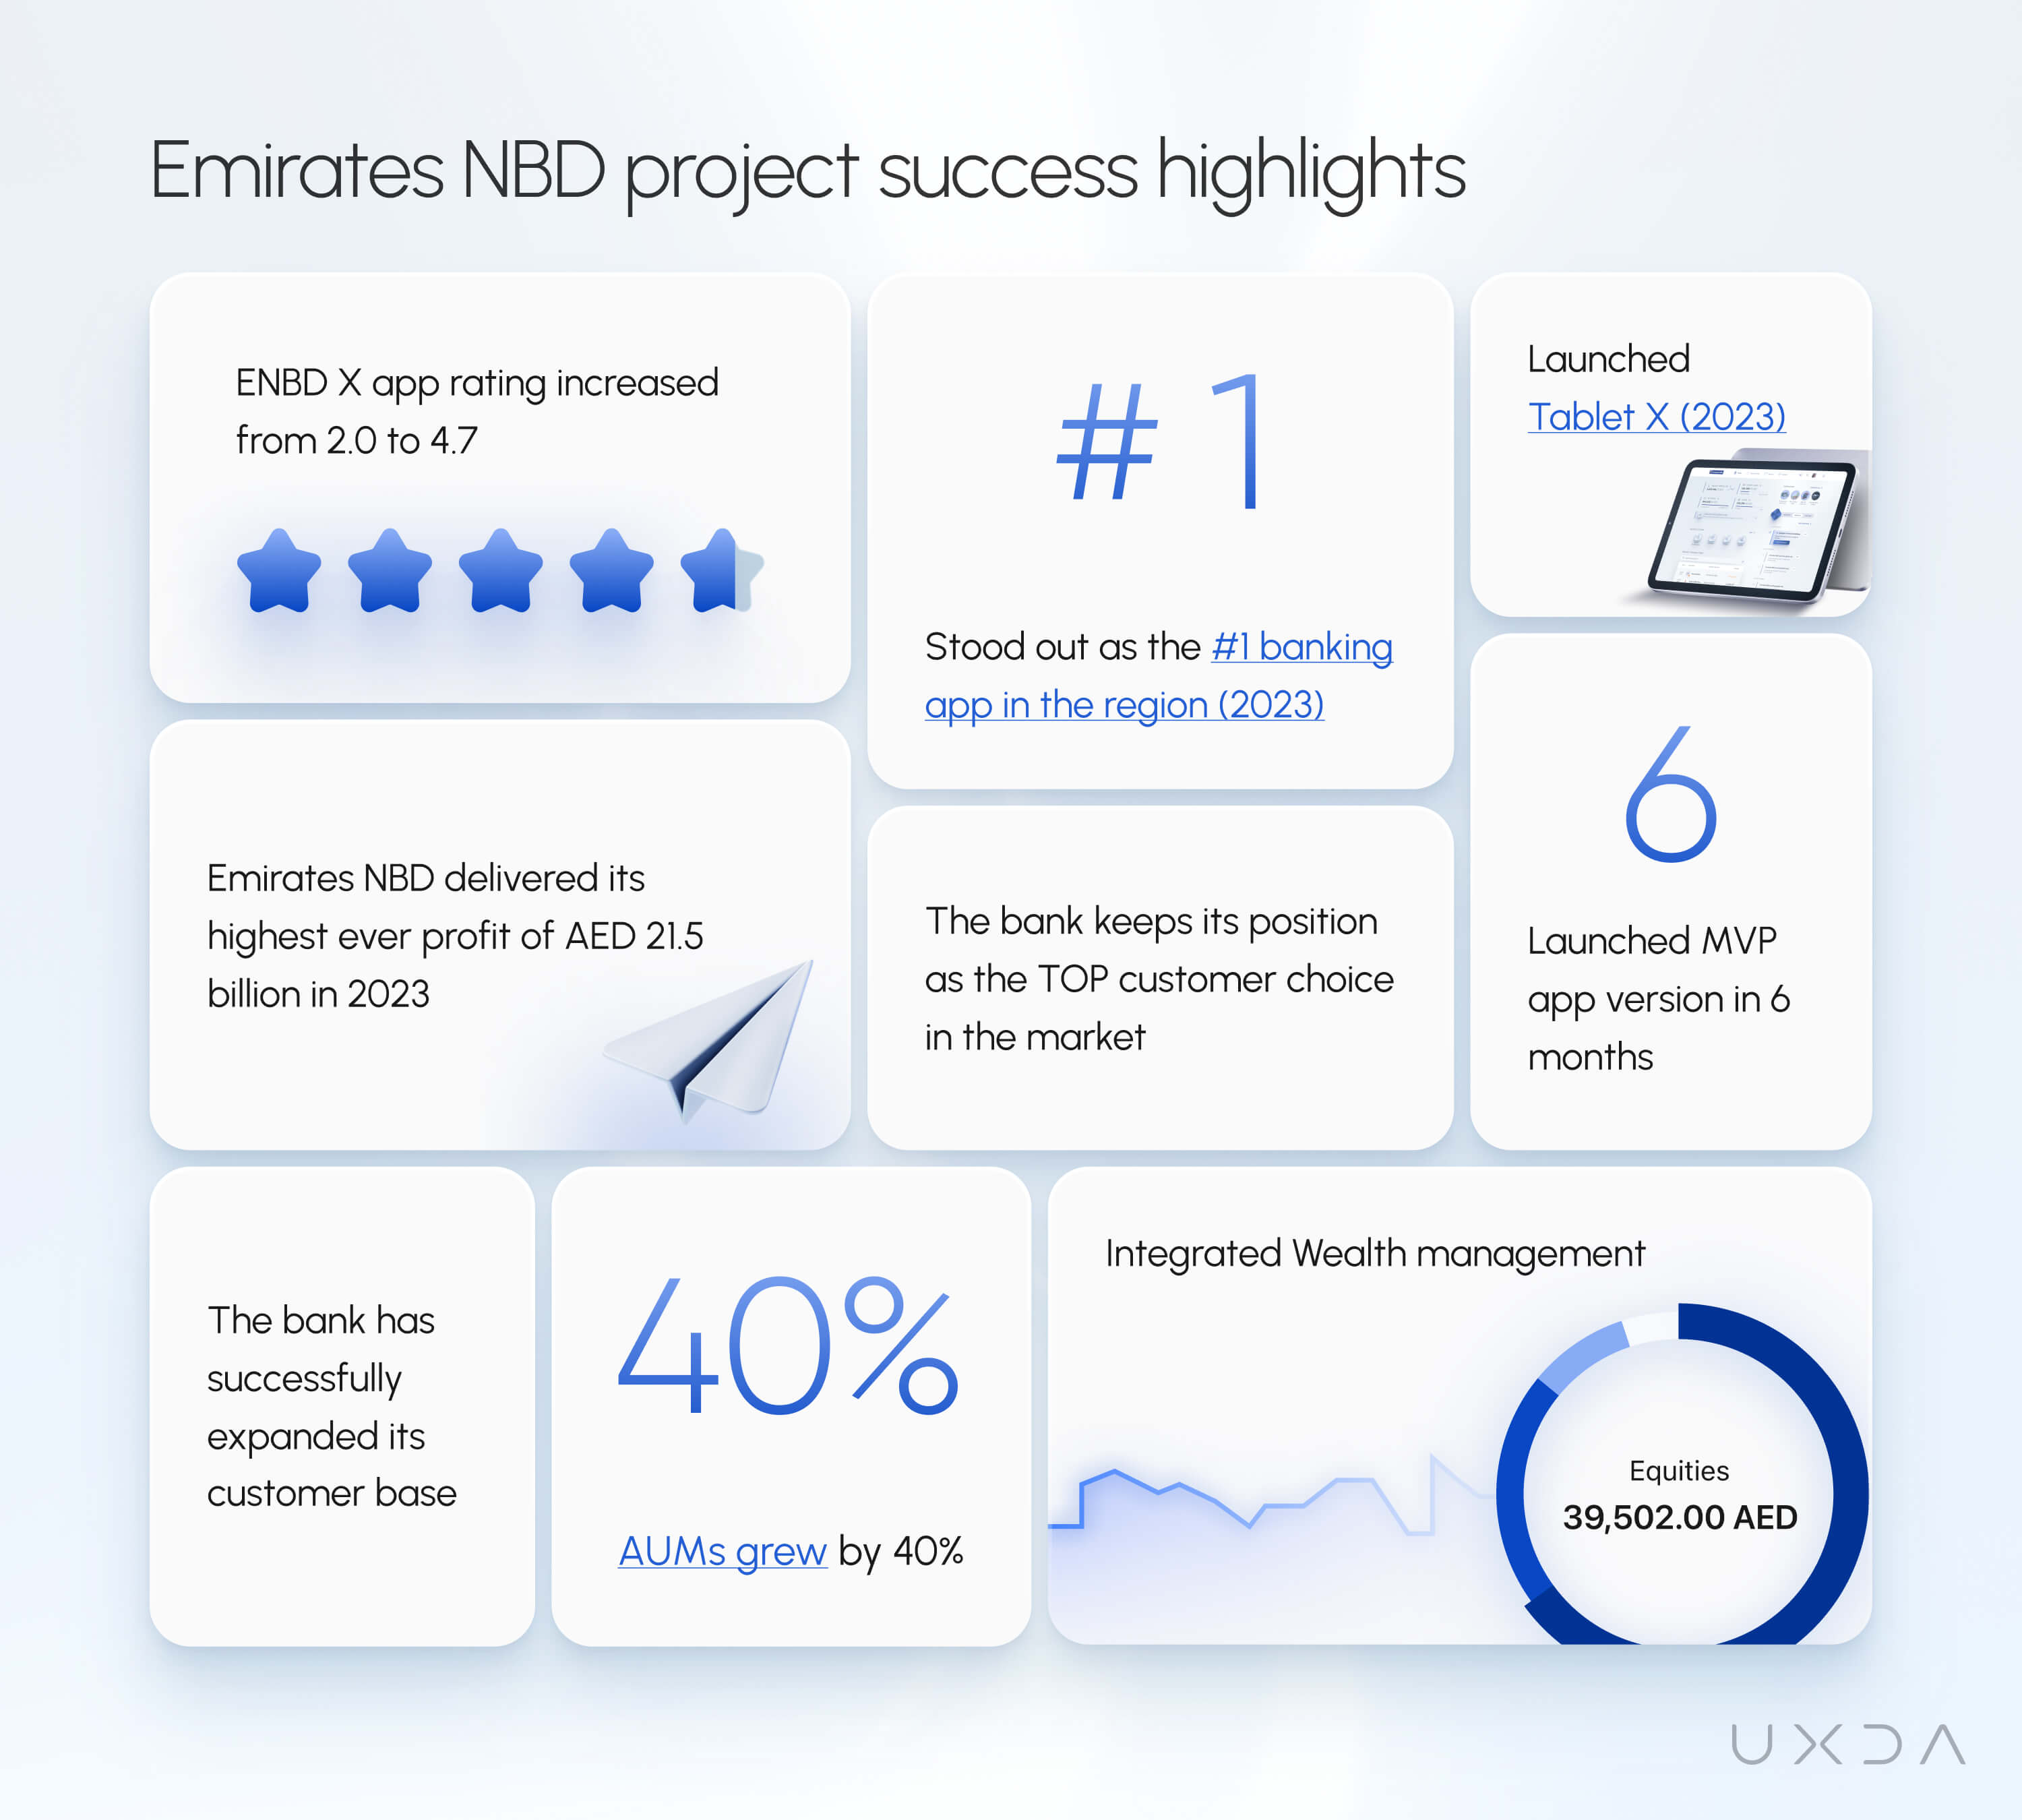
These figures demonstrate the scale of business performance associated with the broader transformation, but they should not be presented as outcomes attributable solely to UX design without supporting causal evidence.
The strategic lesson is that banking CX creates greater value when experience strategy, product innovation, brand identity and technology transformation are aligned rather than managed as separate initiatives.
Conclusion: Customer Experience Is How Banking Strategy Becomes Reality
Banking customer experience strategy is no longer about making digital channels easier to use. It is about ensuring that business ambition, customer needs, technology investments and brand positioning translate into a coherent experience that creates measurable value.
Financial institutions can invest millions in transformation, launch advanced technologies and communicate compelling brand promises. But customers ultimately judge the institution through what they experience.
The banks that create lasting competitive advantage will be those that connect CX strategy, financial UX, Digital Brand Identity and experience governance to deliver experiences that are not only efficient and trustworthy, but meaningfully different.
Your digital experience is where your bank's strategy becomes visible—and where customers decide whether to believe it.
Banking Customer Experience Strategy: Key Questions
1. What is banking customer experience strategy?
Banking customer experience strategy is the approach financial institutions use to align customer needs, business goals, digital services, brand identity and operational capabilities. It aims to improve the complete customer relationship while delivering measurable outcomes in acquisition, engagement, retention, efficiency and differentiation.
2. Why is customer experience important in banking?
Customer experience influences how customers choose, use and remain with a financial institution. Clear, trustworthy and efficient banking experiences can improve product adoption, reduce service friction, support retention and strengthen competitive differentiation.
3. How does banking CX differ from banking UX?
Banking CX covers the entire customer relationship across products, channels, communication and service interactions. Banking UX focuses more specifically on how customers interact with particular products, interfaces and journeys. Financial UX is an essential contributor to the broader banking customer experience.
4. How can banks improve digital customer experience?
Banks can improve digital CX by researching customer needs, identifying journey friction, simplifying financial processes, connecting channels, establishing a distinctive experience vision and measuring customer outcomes. Sustainable improvement also requires cross-functional governance and continuous validation.
5. How does customer experience affect bank profitability?
Customer experience can affect bank profitability through acquisition conversion, product adoption, retention, cross-product relationships and service costs. The financial impact should be measured using attributable revenue improvements, cost reductions and customer lifetime value rather than satisfaction scores alone.
6. What is the role of AI in banking customer experience?
AI can improve banking CX through contextual assistance, proactive insights, personalized decision support and automation of complex service processes. Successful implementation requires transparency, customer control, appropriate safeguards and clear alignment with customer needs.
7. What is Digital Brand Identity in banking?
Digital Brand Identity is how a financial institution expresses its brand promise, values and personality through digital interactions. It includes interface design, communication, service behavior, personalization and customer journeys, helping create a coherent and recognizable banking experience.
8. Who is responsible for banking CX strategy?
Banking CX strategy requires executive sponsorship and cross-functional accountability. Digital, experience and product leaders guide its implementation, while technology, operations, risk, compliance and customer service teams contribute to delivery and measurement.
9. How can banks measure customer experience success?
Banks should combine experience indicators such as customer effort and task success with behavioral metrics such as activation, completion and retention, and financial measures such as revenue, cost-to-serve and lifetime value. Results should be compared with reliable baselines.
10. Why is a mobile banking app redesign not enough?
A mobile app redesign may improve usability without addressing fragmented services, outdated processes, inconsistent channels or organizational constraints. Lasting CX transformation requires alignment between customer journeys, business strategy, technology, operations and governance.
Discover our clients' next-gen financial products & UX transformations in UXDA's latest showreel:
UXDA partners with financial institutions to define, validate and govern distinctive digital experiences that align customer value with business objectives. Whether preparing for a major digital transformation, defining a future banking experience or addressing fragmented digital journeys, UXDA helps financial leaders make experience decisions before they become expensive to reverse.
If you want to create next-gen financial products to receive an exceptional competitive advantage in the digital age, contact us!
With the power of financial UX design, we can help you turn your business into a beloved financial brand with a strong emotional connection with your clients, resulting in success, demand, and long-term customer loyalty:
- E-mail us at info@theuxda.com
- Chat with us in Whatsapp
- Send a direct message to UXDA's CEO Alex Kreger on Linkedin