

Improving customer experience in banking is no longer primarily about redesigning individual screens or adding more digital features. Customers experience the bank as one relationship shaped by mobile and online banking, products, communications, support, operations, policies and the way the institution responds when something goes wrong. This means poor banking CX rarely has one isolated cause. Friction in onboarding may originate in compliance processes. Confusing payments may reflect fragmented systems. Weak personalization may reveal disconnected data. An inconsistent digital experience may expose misalignment between brand promise, product strategy and operational reality.
The challenge for banking leaders is systemic: how can the institution continuously translate customer needs and business strategy into a coherent experience across products, channels and time?
UXDA identifies five drivers that help financial institutions improve banking customer experience at this level: strategic experience intent, customer value, organizational alignment, evidence-based diagnosis and continuous experience governance.
The cost of unresolved customer friction remains visible in banking onboarding. Fenergo’s 2025 survey of 600 financial-services decision-makers found that 70% of firms had lost clients in the previous year because of slow onboarding, while average abandonment was around 10%. The research also points to fragmented processes, manual work and operational complexity as persistent contributors.
Download Improving the customer experience in banking - PDF.
The digital revolution has changed the rules of the game we all play. If you don't adapt, you will probably lose. What was efficient to reach demand a few decades ago has now become a waste of time and money. Customer expectations, technology and market conditions continue to change, making CX improvement a continuous capability rather than a one-time response to disruption.
The UXDA team has tested and put into practice more than 100 UX design methods and techniques while designing 150+ financial products in 39 countries. Across more than a decade of specialized financial UX work with banks and financial institutions globally, UXDA has seen the same pattern repeatedly: customer experience problems rarely belong to the interface alone.
Poor banking customer experience can lead to problems for the customer and the financial company. For the customer, poor customer experience can lead to frustration, confusion, and dissatisfaction, which can ultimately result in them switching to a different financial brand. This can lead to a loss of business and revenue for the company. Additionally, poor customer experience can also lead to negative word-of-mouth and online reviews, which can damage the financial brand's reputation and make it harder to attract new customers.
What Is Customer Experience in Banking?
Customer experience in banking is the total perception customers form through every interaction with a financial institution across products, services, channels and time. It includes mobile and online banking, branches, customer support, payments, lending, investments, communications and the operational processes customers encounter indirectly.
Banking UX and banking CX are closely related but not identical. UX focuses more specifically on how customers use and experience particular products, interfaces and journeys. CX encompasses the wider relationship—including service, brand perception, trust, communication and the consistency of experiences across the institution.
The digital banking customer experience (digital banking CX) consists of all the emotions, thoughts and behavior of a customer triggered in digital interactions with financial service and brand. A banking customer experience is generated by all digital products and brand ecosystems, including previous customer engagements and future expectations.
The goal of improving customer experience in banking is to make banking services as convenient, efficient, and pleasant as possible for the customer. This can be achieved through various means, such as offering an appropriate range of services and features, providing clear and helpful information and assistance, and ensuring that the customer's interactions with the bank are smooth and hassle-free. Make sure that banking customer experience aligns with brand identity and business strategy.
In the digital age, century-old brand reputation is no longer a guarantee of loyalty and can be instantly damaged by a problem with a mobile application caused by poor design. However, while a confusing interface can certainly damage customer experience, largest banking CX problems originate beyond the interface itself. Product rules, technology constraints, fragmented ownership, inconsistent communication, support processes and organizational priorities all influence what customers eventually experience.
This is why improving banking CX requires a systemic approach. Banks need to identify how individual journeys connect with the wider customer relationship and how decisions made across different functions reinforce—or contradict—the intended experience.
A screen can be optimized locally while the overall experience remains fragmented. Sustainable CX improvement happens when strategy, products, operations, technology, brand and governance move in the same direction.
AI also can improve banking CX through contextual assistance, proactive service, personalization, conversational interactions and automation. But AI amplifies the quality of the underlying strategy and experience system: automating a fragmented or misdiagnosed journey can simply scale the problem faster.
Banks should therefore apply AI after clarifying the customer problem, target outcome, data boundaries and governance required for the use case.
5 Systemic Ways to Improve Customer Experience in Banking
Improving customer experience in banking requires more than fixing individual journeys, redesigning an app or introducing another digital feature. The strongest banking experiences emerge when customer needs, business strategy, brand, technology, operations and organizational decision-making reinforce the same experience vision. Leadership needs to define what kind of relationship the bank intends to create, which customer behaviors and outcomes matter, and how experience supports the institution’s broader business strategy.
This requires banks to move beyond treating UX as a delivery function. Customer experience needs to become an institutional capability: strategically directed, systemically designed, emotionally meaningful and continuously governed. The objective is to make customer experience part of how the institution prioritizes and makes decisions—not merely how those decisions are presented through an interface.
Five interconnected principles can help financial institutions make that shift.
1. Use Strategic UX to Align Customer Experience With Business Strategy
One of the most expensive mistakes in banking CX improvement is solving the visible symptom instead of the underlying customer problem. Low adoption may look like a communication problem but originate in poor relevance. Onboarding abandonment may appear to require a UI redesign while the real cause sits in fragmented KYC processes. Repeated support calls may indicate unclear product rules rather than insufficient customer education.
Before choosing the solution, banks need to combine customer research, behavioral analytics, complaints, support data, operational insight and competitive context to understand why the problem occurs. This is where UX research and Systemic UX become strategic: they connect what customers experience with the wider system producing that experience.
Instead of starting with available technology or a list of requested features, begin with the customer and business outcome the institution wants to create. Then work backward to identify the journeys, processes, capabilities and technology needed to deliver it.
Many banks still involve UX after the most important decisions have already been made. Business teams define the proposition, technology defines the constraints, product teams define the requirements—and designers are then asked to make the resulting journey intuitive. This limits UX to improving the presentation of decisions rather than influencing whether those decisions create the right customer and business outcomes in the first place.
Strategic UX moves customer experience upstream. It connects customer needs, business goals, Digital Brand Identity, technology and product strategy before individual features and interfaces are defined.
Before improving a journey, banks need clarity about the value the experience is intended to create. A faster payment flow, more personalized dashboard or AI assistant has little strategic meaning unless it addresses a validated customer need and supports a business objective. The target experience therefore needs to define both sides of the equation: what should become better for the customer and why that improvement matters to the institution.
Instead of beginning with “What should we build?”, a Strategic UX approach asks more fundamental questions:
- What customer problem are we trying to solve?
- Which behaviors and outcomes should the experience support?
- What should customers understand, feel and be able to accomplish?
- How does this strengthen the bank's business model and strategic positioning?
- What should distinguish this experience from competing financial services?
- How will we know whether it creates customer and business value?
For example, if a bank wants to increase investment adoption, the immediate response might be to add more investment products or promotional placements. Strategic UX looks deeper. Customers may not need more products—they may need greater confidence, clearer risk explanation, better goal-setting or a more understandable path from saving to investing. The resulting solution could therefore be very different from the original feature request.
Strategic UX helps banks connect experience improvements to measurable outcomes such as digital adoption, conversion, retention, customer effort, operational efficiency, trust and relationship value. UX stops being the final layer applied to a banking product and becomes part of deciding what the product should become.
The goal is not to make predefined banking requirements easier to use. It is to ensure the bank is solving the right customer problems in the right way. This is an important shift because customer experience is shaped by decisions long before customers see the interface.
Social networks, information transparency and demand for sustainability challenge businesses to put the people first by becoming customer-centered and deliver experiences people need. That's why the future of the banking industry depends on how the new generation of bankers can bring their mindset in line with the digital age to provide the best possible banking customer experience.
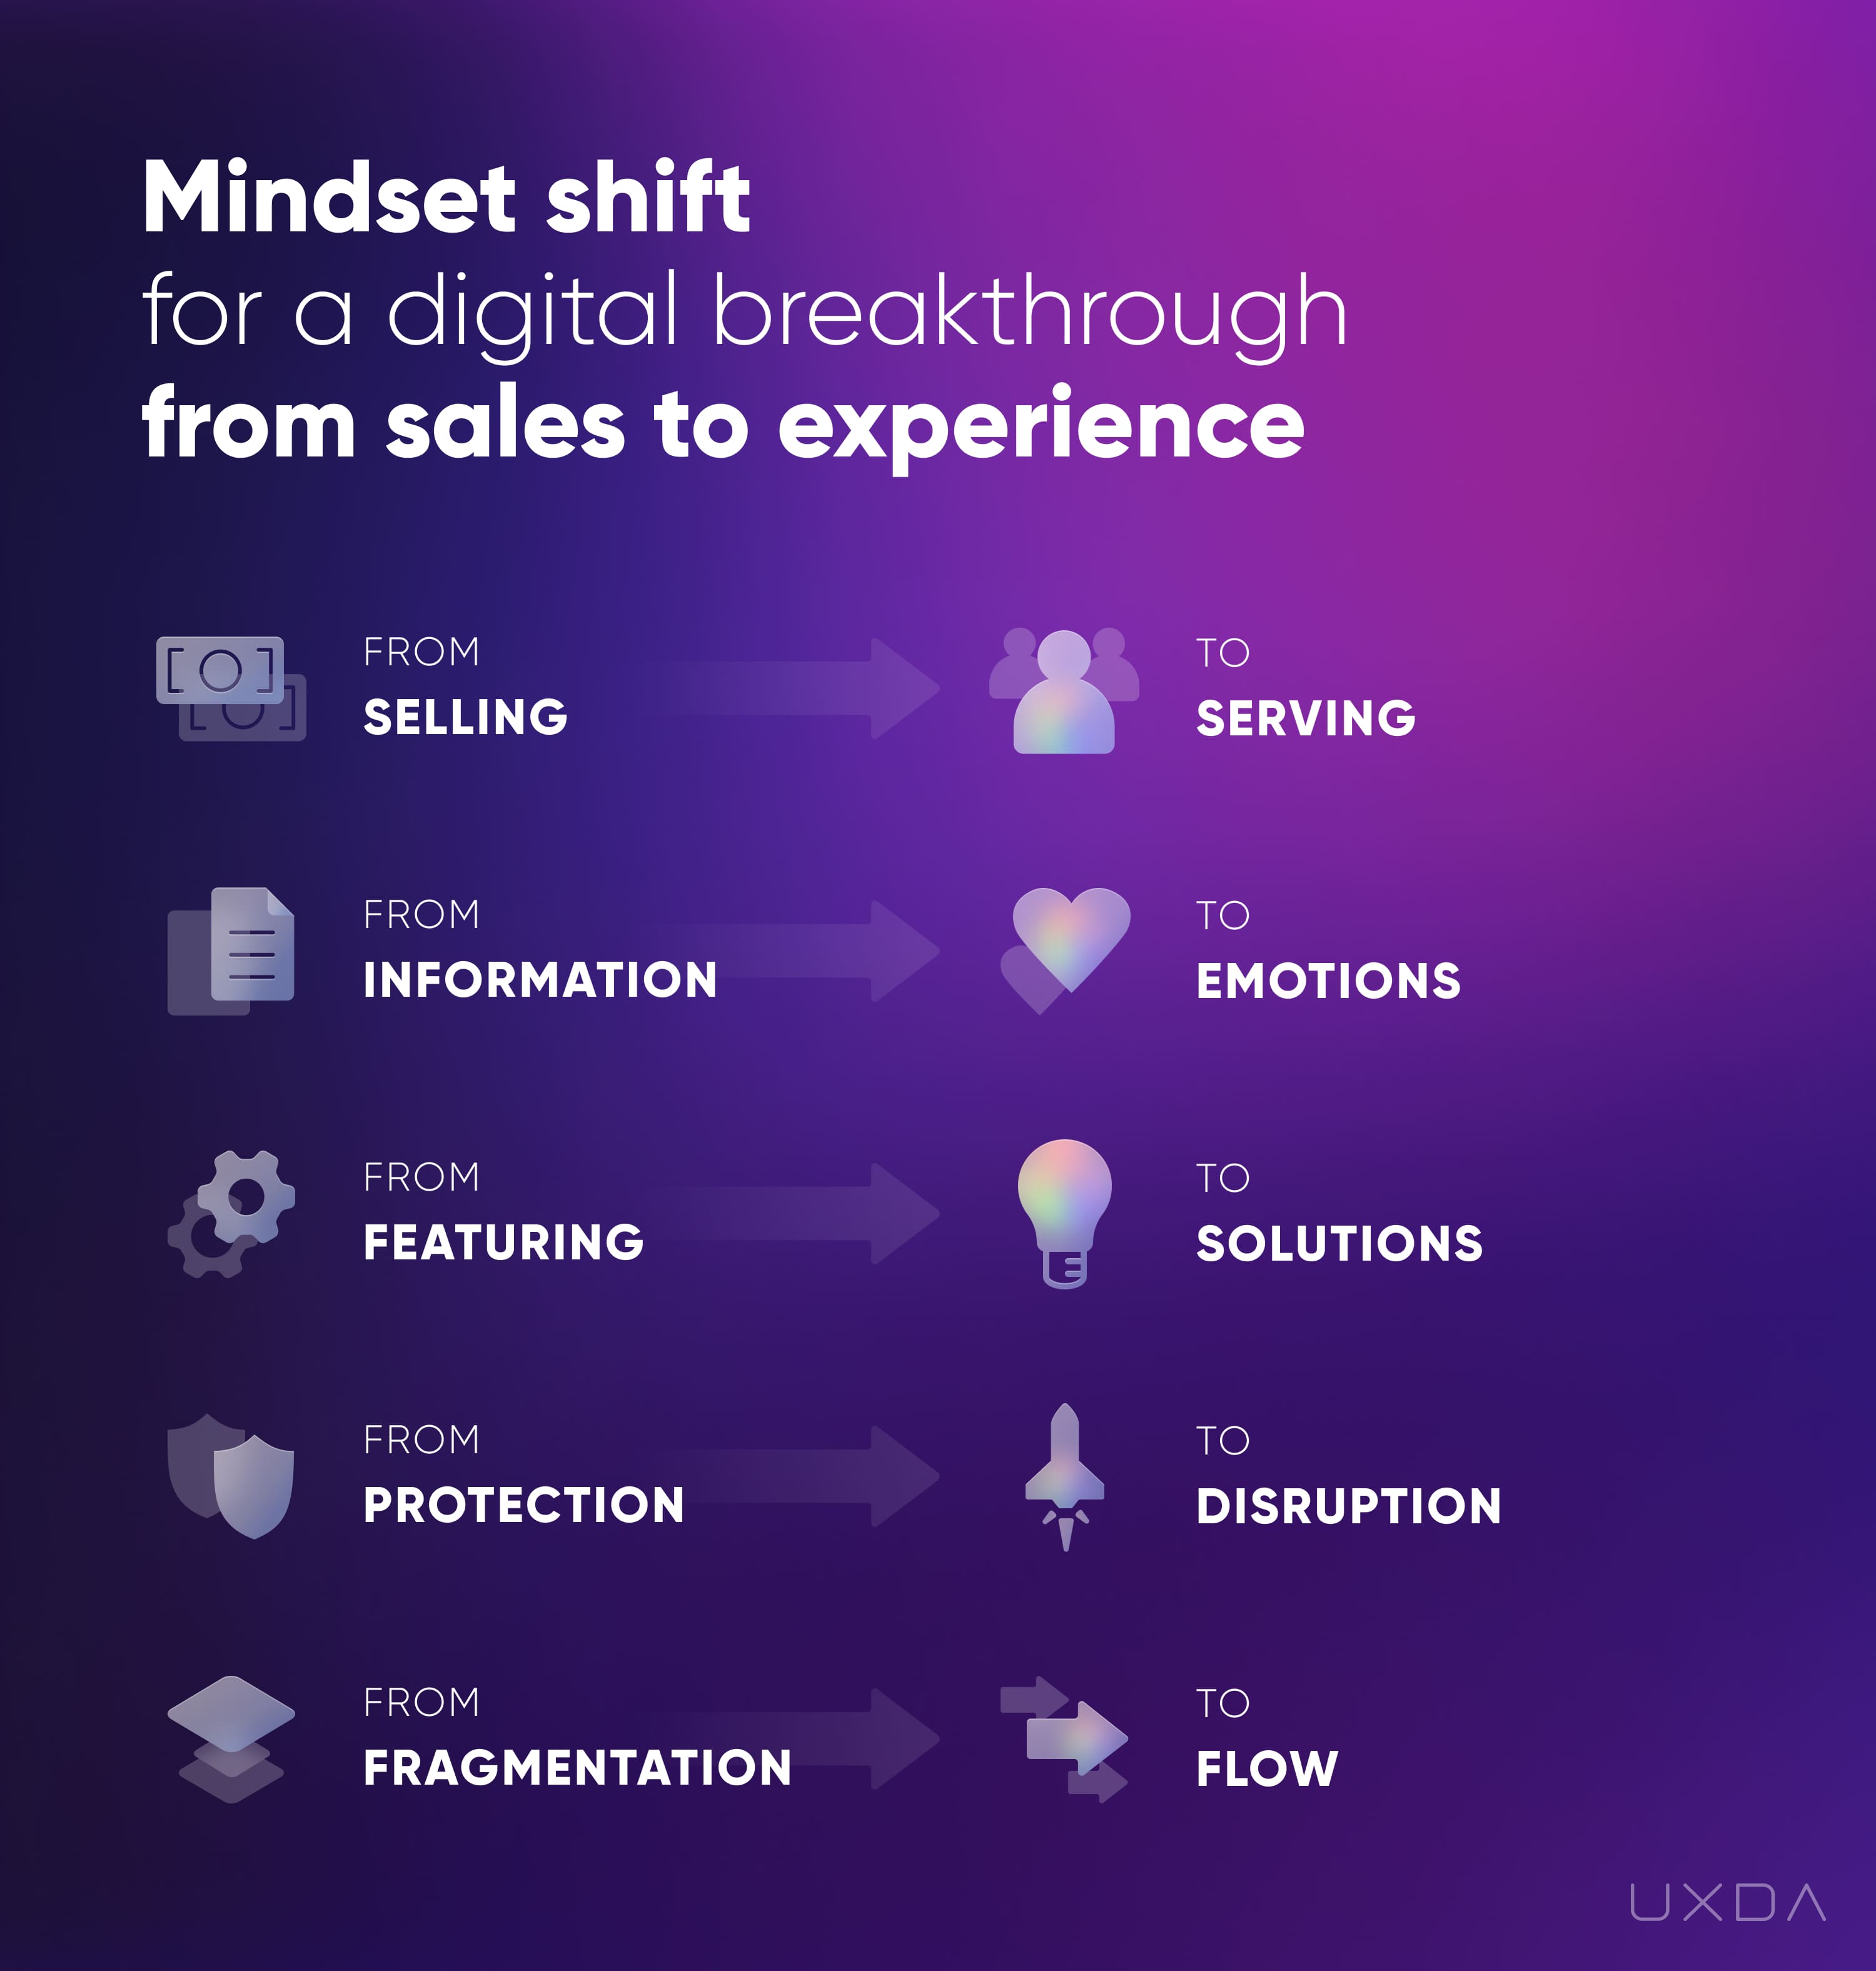
There are five key attitudes that can be integrated into a company's DNA with the aim to make the team mindset purpose-driven and shift the business culture toward the digital age.
Serve Instead of Sell: Customer Value Before Sales Pressure
Traditional banking starts with products, targets and conversion. Strategic UX starts with the customer problem and asks what value the bank should create before deciding what to sell.
Emotions Over Information: Design the Right Emotional Outcome for the Context
Traditional banking assumes that providing correct information is enough. Emotional banking approach recognizes that customers also need to feel delight, confidence, control, reassurance or progress depending on the financial moment.
Solution Instead of Features: Customer Outcomes Before Features
Traditional transformation measures progress by features launched. Strategic UX measures whether customers can achieve meaningful outcomes more easily, confidently and successfully.
Disruption Over Protection: Challenge Legacy Assumptions With Evidence
Traditional organizations often design around existing products, processes, systems and internal ownership. Research and evidence should reveal whether existing structures still serve customers—or whether the bank is simply transferring historical complexity into the digital experience.
Create Flow, Avoid Fragmentation: Design One Relationship, Not Isolated Journeys
Traditional banking often allows individual products, journeys and teams to develop their own language, interaction patterns and visual logic. Digital Brand Identity aligns them around one recognizable expression of the bank’s strategy, personality and promise.
Read more about the experience mindset
2. Treat the Bank as One Product, Not a Collection of Features and Channels
Customers do not think about banking in the same organizational structure as the institution. They do not experience the Cards Department, Payments Department, Lending Department, Contact Center and Mobile Banking Team separately.
Customers experience one bank, but the experience is produced by many functions. Product defines capabilities. Technology enables them. Operations shape delivery. Risk and compliance define boundaries. Marketing creates expectations. Customer service manages moments where the experience breaks.
If each function optimizes independently, the customer receives the combined result: fragmented journeys, conflicting communication and inconsistent service. Improving banking CX therefore requires shared experience principles, common customer evidence and clear ownership across organizational silos.
Yet many financial institutions still develop digital experiences as a collection of projects. A new onboarding journey is redesigned independently. Payments receive another update. Investments are built on a separate platform. Customer support follows different processes. Marketing introduces new terminology. AI is added as another layer.
Each initiative may perform well independently while the total customer experience becomes increasingly fragmented.
Customers do not experience departments. They experience one bank.
The Bank-as-a-Product approach changes the unit of design from an individual feature or channel to the entire banking relationship. Mobile banking, online banking, products, services, communications, support and emerging AI-powered interactions become parts of one continuously evolving experience ecosystem.
This changes how banks evaluate individual improvements. A new feature should not only answer: Does this feature work?
It should also answer: Does this make the whole bank work better for the customer?
For example, redesigning card controls is not successful if terminology differs from customer support, alerts communicate another status, web banking follows different logic and customers cannot understand what will happen after freezing their card.
Similarly, a beautiful mobile onboarding flow does not create a good customer experience if account verification continues through disconnected emails, manual document requests and contradictory support communication.
Every local experience decision either strengthens or weakens the coherence of the whole bank.
How banking customer experience is created:
Business strategy
↓
Customer needs and desired outcomes
↓
Products and policies
↓
Technology and operations
↓
Journeys and interactions
↓
Communication and service
↓
Customer perception, behavior and trust
CX problems can originate at any layer. Redesigning only the final interface may therefore improve the symptom without resolving the cause.
Bank-as-a-Product therefore encourages financial institutions to manage experience continuously rather than through isolated redesign projects. Customer journeys need to connect across products, channels and life stages, while new capabilities should strengthen the existing ecosystem instead of adding another layer of complexity.
This is especially important as banks introduce AI, embedded services and increasingly adaptive experiences. Without a shared product vision, faster innovation can simply produce faster fragmentation.
Customers do not experience banking projects. They experience one bank. The bank should therefore be designed and managed as one product.
Read more about Bank-as-a-Product
3. Build a Digital Brand Identity Customers Can Experience, Not Just Recognize
Banks invest heavily in brand strategy, visual identity, campaigns and positioning. Yet once customers enter the digital product, much of that distinctiveness often disappears.
One bank promises simplicity. Another promises empowerment. Another positions itself as innovative, personal or premium. But inside their apps, customers encounter similar dashboards, similar navigation, similar components and similar transactional language.
The logo changes. The experience often does not.
Digital Brand Identity closes the gap between what the bank says and how the bank actually behaves in digital space.
It extends brand identity beyond colors, typography and visual assets into:
- interaction patterns;
- tone of voice;
- information hierarchy;
- motion and microinteractions;
- personalization;
- service behavior;
- feedback and system responses;
- emotional tone;
- product logic;
- the way complexity is explained;
- the way customers are guided through important financial decisions.
A bank positioned around empowerment, for example, should not merely use empowering marketing language. Its digital experience should give customers greater visibility, control and understanding of their finances.
A bank positioned around simplicity should not require customers to navigate organizational terminology, interpret unclear statuses or contact support to understand routine processes.
A premium financial brand should express that positioning not only through sophisticated and consistent visuals but through the quality of guidance, personalization, service continuity and attention to detail throughout the journey.
A visual identity defines how a bank looks. Digital Brand Identity defines how the bank looks, feels and behaves in digital space.
This becomes increasingly important as AI makes high-quality interface production easier and functional banking features become more comparable. Distinctiveness will depend less on whether a bank can build a polished interface and more on whether customers experience a recognizable philosophy, personality and relationship behind it.
Digital Brand Identity therefore improves banking CX in two ways: it creates coherence, because interactions consistently reinforce the same promise, and distinctiveness, because the experience begins to feel recognizably different from competitors.
The strongest financial brands do not simply communicate their values. Customers can feel those values through the way the digital service behaves and communicates.
Explore more about Digital Brand Identity
4. Use Dopamine Banking to Turn Financial Progress Into Emotional Value
Traditional banking UX has focused heavily on reducing friction and making transactions efficient. That remains essential—but efficiency alone does not define the full customer relationship.
Money is emotional.
Customers can feel anxiety before paying a large bill, uncertainty when investing, frustration when something fails, relief when debt decreases, confidence when finances become clearer and satisfaction when they reach a savings goal. A banking experience that ignores these emotional states may be technically usable while still feeling cold, stressful or indifferent.
UXDA's Dopamine Banking approach introduces positive emotional reinforcement into financial experiences through progress, achievement, meaningful feedback, personalization and carefully designed moments of delight.
The objective is not to turn banking into a game or maximize stimulation. It is to use emotional design responsibly to help customers feel delight, progress, confidence, control, reassurance and motivation.
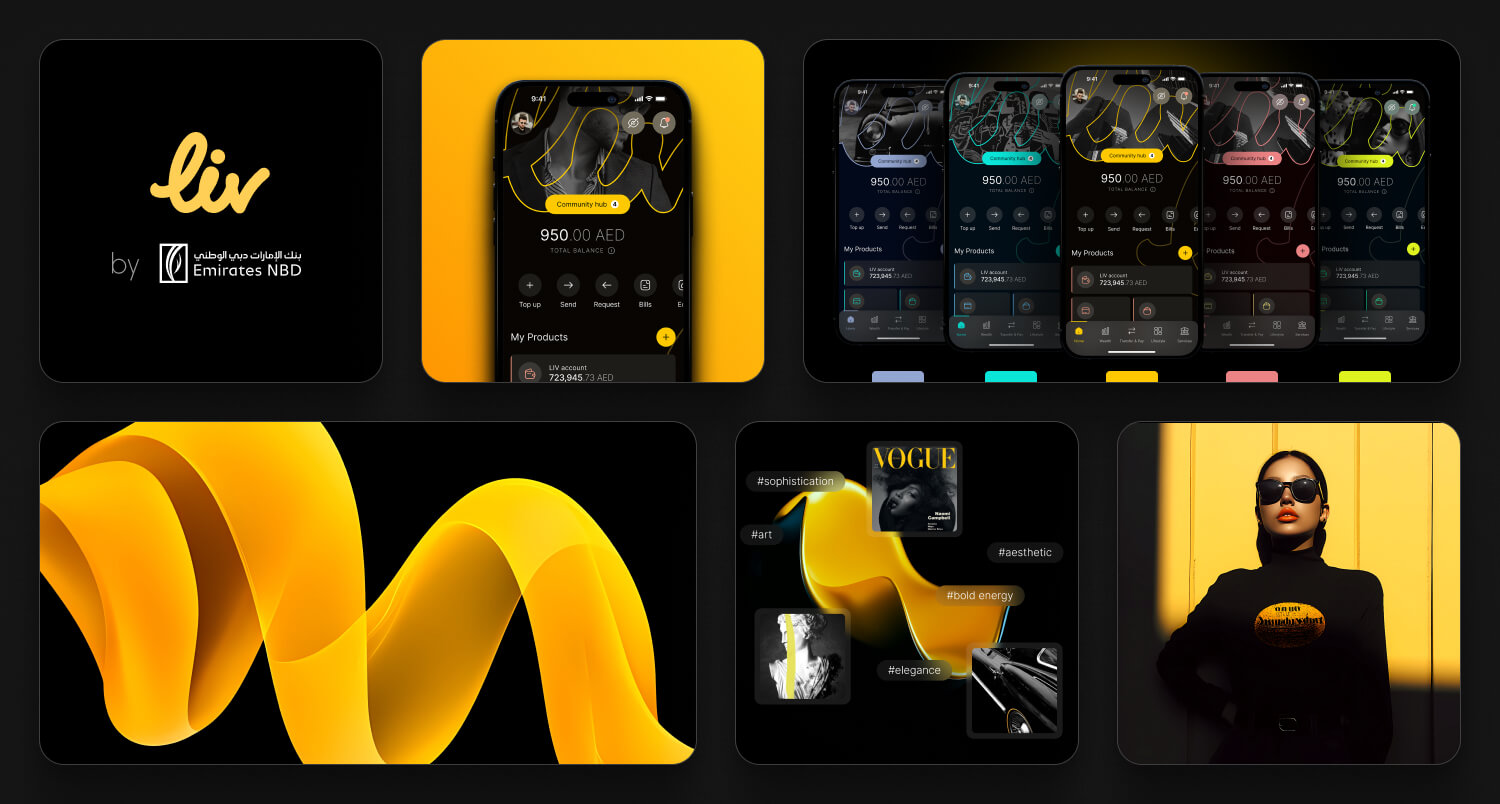
For example: Instead of showing only a savings balance, the experience can visualize progress toward a meaningful goal. Instead of presenting an investment portfolio as a wall of numbers, the product can help customers understand whether they are progressing toward their long-term objectives. Instead of responding to a successful debt repayment with a generic “Transaction completed,” the experience can acknowledge an important financial milestone. Instead of using alarming language when something goes wrong, the interface can clearly explain what happened, reassure the customer about what is safe and show exactly what to do next.
These details matter because the emotional outcome of an interaction influences how customers perceive the wider relationship with the bank. However, Dopamine Banking should reinforce healthy financial behavior rather than manipulate attention. Positive reinforcement should support meaningful customer outcomes—saving consistently, understanding finances, reducing debt, making informed decisions or developing greater financial confidence.
The most emotionally intelligent banking experiences also understand when not to celebrate. A loan rejection, fraud alert or significant investment loss requires reassurance and clarity rather than playful animation.
This is why emotional design is contextual. The objective is not maximum emotion. It is the right emotion at the right moment.
When functional usability, Digital Brand Identity and emotional intelligence reinforce one another, banking can move beyond being a transactional utility and become a supportive part of customers' financial life.
Read more about Dopamine Banking approach
5. Use Systemic UX Governance to Sustain Customer Experience at Scale
Even an excellent redesign can deteriorate over time. New teams introduce different patterns. Regulations add additional steps. Technology creates exceptions. Product owners optimize individual KPIs. New vendors introduce different interaction logic. AI generates new interfaces and communication. Features accumulate faster than old complexity is removed.
Gradually, the coherent experience becomes fragmented again. This is why improving banking CX cannot end with a successful redesign.
Systemic UX Governance turns customer experience from a project outcome into a continuously managed institutional capability.
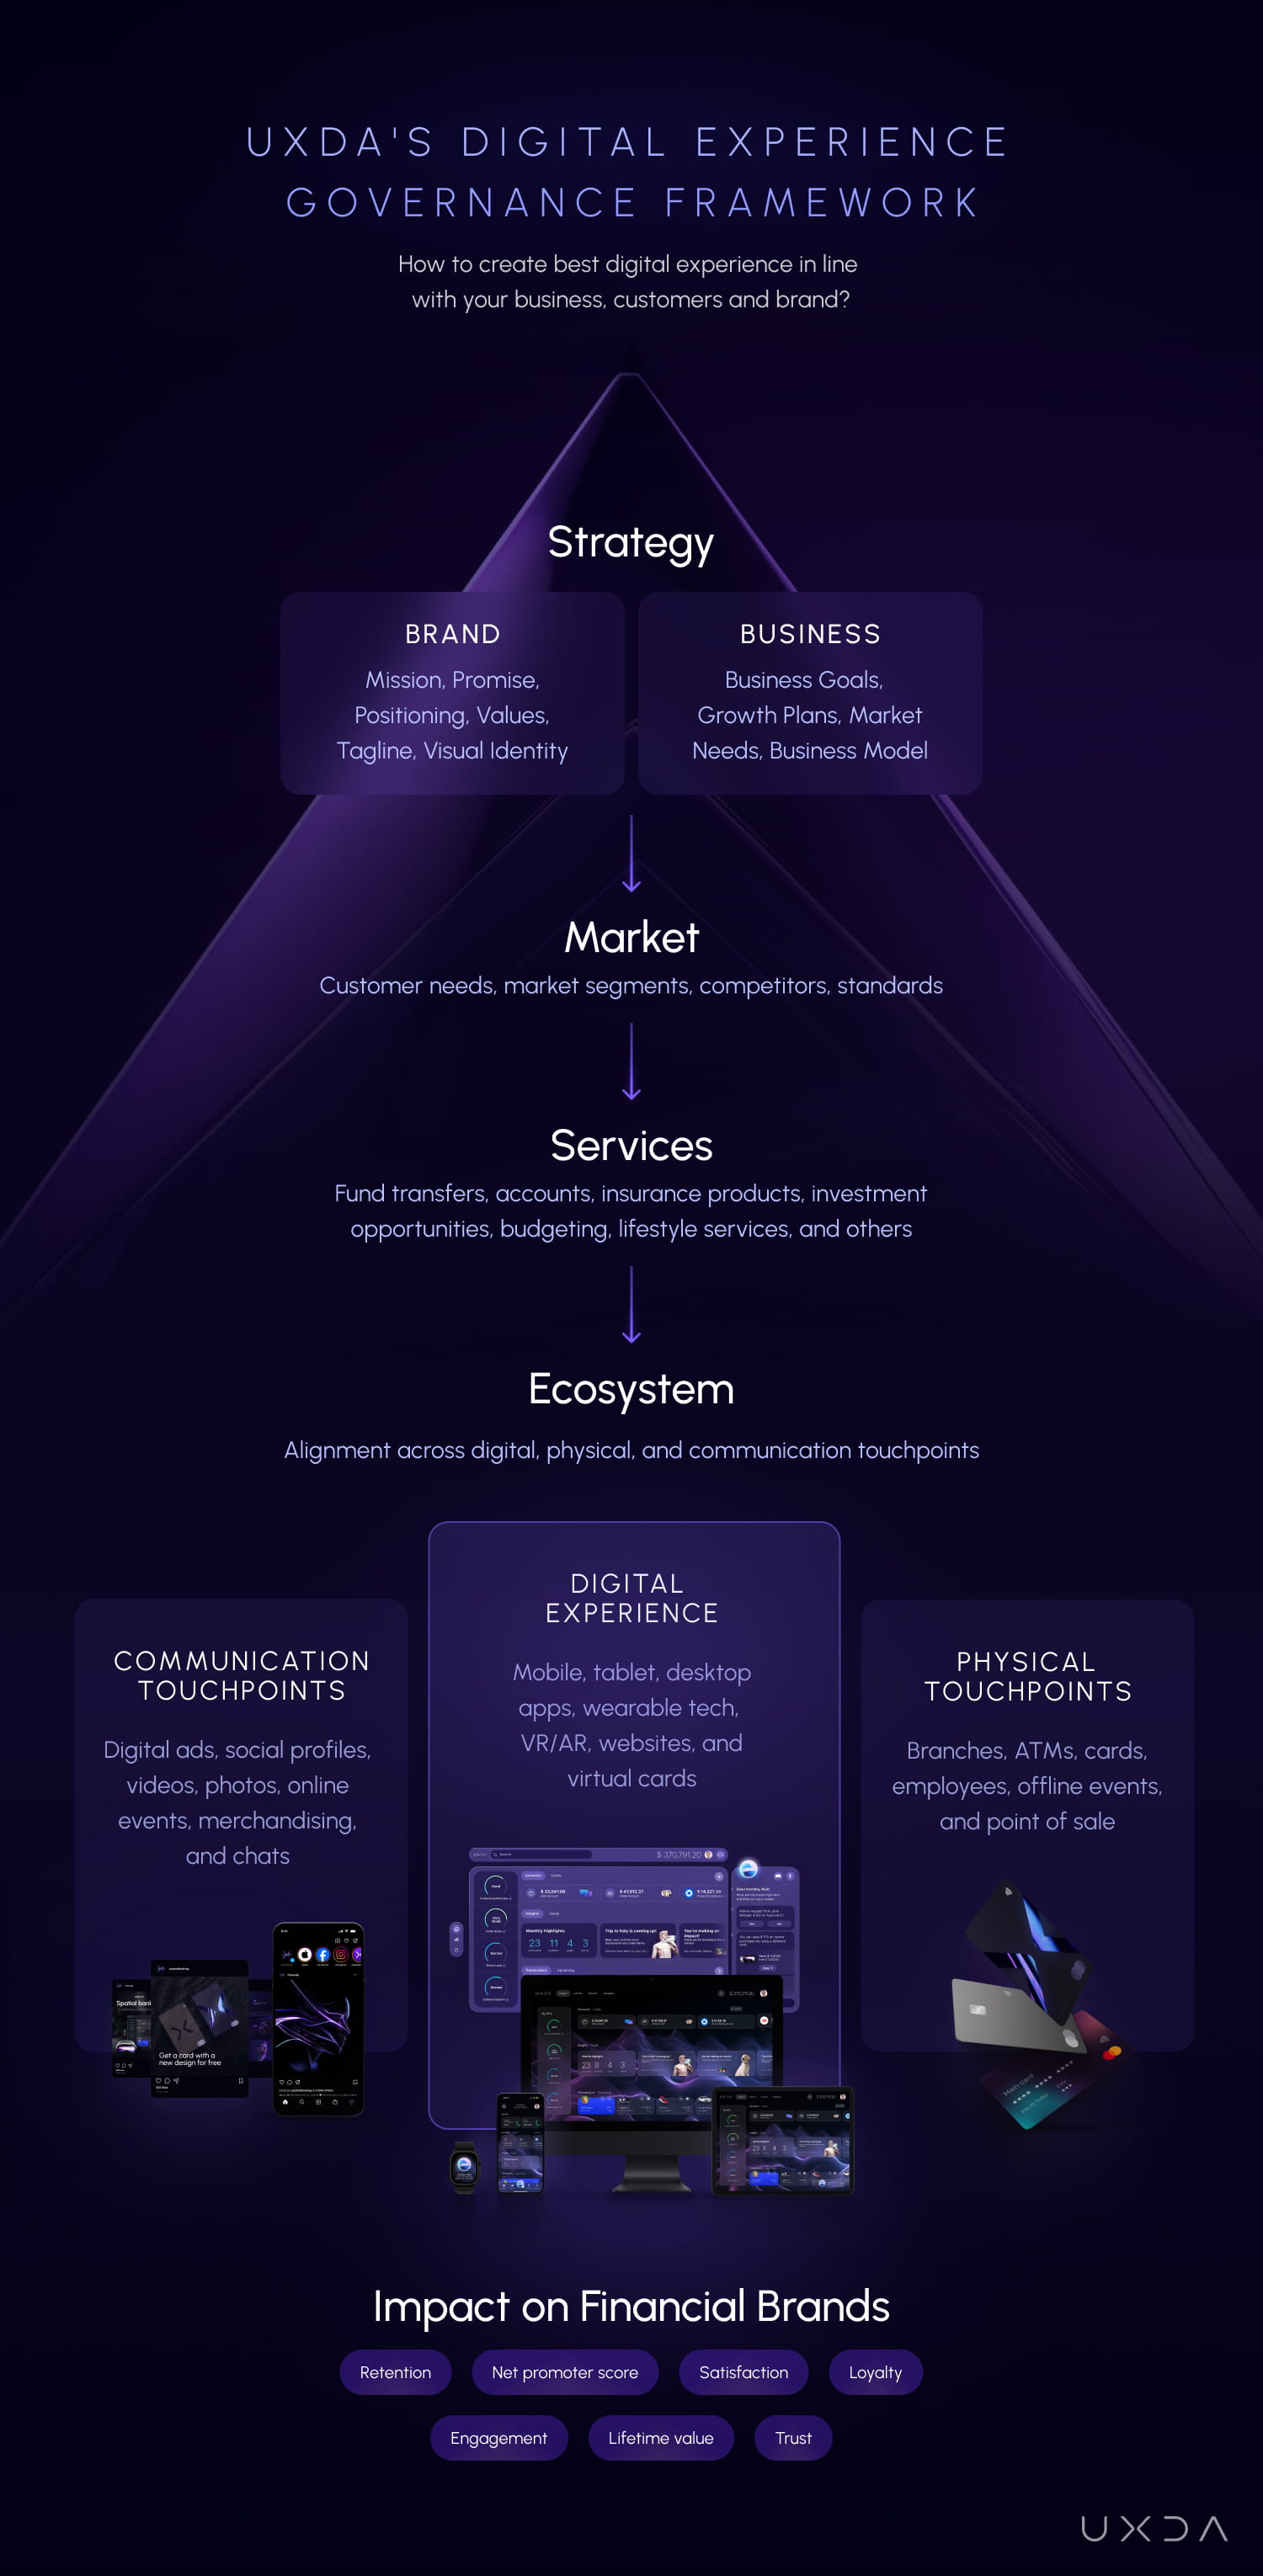
Strategic UX defines where the experience should go. Systemic UX Governance establishes how hundreds of decisions across the organization remain aligned with that direction.
This includes:
- shared experience principles;
- clear decision rights and accountability;
- customer evidence available across teams;
- design and interaction standards;
- Digital Brand Identity guidelines;
- cross-product experience reviews;
- measurable customer and business outcomes;
- mechanisms for identifying Experience Debt;
- processes for resolving conflicts between business, technology, risk and customer needs;
- continuous research and validation.
Governance becomes especially important in large financial institutions because no single UX team can control every customer interaction.
Product, technology, operations, compliance, marketing and service teams continuously make decisions that affect the experience. Systemic UX Governance creates the common framework that allows those decisions to remain locally efficient while still supporting one coherent customer relationship.
It also changes how banks measure progress. The number of features released, screens redesigned or design-system components created does not necessarily indicate better customer experience.
Banks need to connect experience decisions with outcomes such as:
- adoption;
- successful journey completion;
- customer effort;
- conversion;
- retention;
- trust;
- avoidable support demand;
- operational errors;
- cross-product engagement;
- cost-to-serve;
- long-term relationship value.
This creates a feedback loop in which customer experience can be continuously diagnosed, improved and protected as the bank evolves.
Without governance, every new initiative has the potential to increase fragmentation. With governance, innovation can reinforce the wider experience system.
Customer experience should not depend on whether individual teams happen to make good UX decisions. The institution needs a system that makes coherent experience decisions repeatable at scale.
Find more on Systemic UX Governance
Why Banking CX Improvements Often Fail
Many customer experience initiatives underperform because they begin too late in the decision process. UX teams receive requirements after product, technology and operational decisions have already defined most of the experience. The interface can then improve presentation but has limited ability to address structural causes of customer friction.
Other initiatives fail because improvement is localized. One journey becomes easier while adjacent products, communications or support processes remain unchanged. Customers then encounter a polished island inside a fragmented ecosystem.
The third failure happens after launch. Without measurement and governance, subsequent releases gradually introduce exceptions, new terminology and inconsistent patterns until the original experience intent is diluted.
Sustainable CX improvement requires influence before, during and after interface design.
Banks should begin where customer friction and business impact intersect. High-volume journeys, high abandonment, recurring complaints, avoidable support demand, low adoption and strategically important products are useful starting points—but the visible symptom should still be diagnosed before a solution is selected.
- Find the friction — analytics, complaints, support and research.
- Identify the root cause — UX, process, product, technology, communication or policy.
- Define the target outcome — customer + business.
- Prioritize systemic leverage — changes that improve multiple journeys or outcomes.
Adding functionality can increase customer value when it solves a genuine need, but feature growth can also increase navigation complexity, inconsistency and Experience Debt.
The measure of CX progress should therefore not be how much the bank ships. It should be whether customers can achieve more meaningful outcomes with less unnecessary effort, greater confidence and stronger trust.
Improving Banking CX Means Building a Systemic Experience Capability
Improving customer experience in banking is not a matter of making every screen more attractive or every interaction frictionless. It requires the institution to build an experience system by understanding what customers need, defining the value and experience it intends to create, aligning the organization around that direction and continuously measuring whether decisions are producing the intended outcomes.
The five drivers work as a one banking experience system.
Strategic UX defines what customer experience the bank should create and why it matters.
Bank-as-a-Product ensures individual products, channels and journeys contribute to one coherent customer relationship.
Digital Brand Identity gives that relationship a recognizable and distinctive character.
Dopamine Banking adds the emotional intelligence and positive reinforcement that can turn financial functionality into meaningful customer progress.
Systemic UX Governance protects and continuously develops the whole system as products, technology, regulation and customer expectations evolve.
Together, they move banking CX beyond interface optimization toward an institutional capability for creating customer and business value.
This is the difference between periodically redesigning banking experiences and building an institutional capability for continuously improving them.
The objective is not simply a better banking app. It is a bank that repeatedly turns customer understanding and business strategy into better financial experiences at scale.
Improving Banking Customer Experience: Key Questions
What is customer experience in banking?
Banking customer experience is the overall perception customers develop through interactions with a financial institution across products, channels, communications, service and time. It includes digital and physical interactions as well as the operational processes customers experience indirectly.
How can banks improve customer experience?
Banks can improve CX by defining clear customer and business outcomes, diagnosing the root causes of friction, aligning journeys across channels and departments, using customer evidence to guide decisions and continuously measuring and governing experience quality.
What is the difference between banking CX and banking UX?
Banking UX focuses primarily on how customers use and experience particular products, interfaces and journeys. Banking CX encompasses the wider relationship, including service, communication, brand perception, trust and consistency across all interactions.
Why do banking customer experience initiatives fail?
CX initiatives often fail when they optimize isolated screens instead of systemic causes, begin after critical product decisions have already been made or lack ownership and governance after launch.
How should banks measure customer experience?
Banks should combine perception metrics with behavioral and operational outcomes such as adoption, completion, customer effort, abandonment, errors, support demand, retention, trust and relationship depth.
Does better banking CX mean removing all friction?
No. Some friction is necessary for security, understanding and informed financial decisions. Good CX removes unnecessary effort while making necessary friction clear, proportional and understandable.
How does AI improve banking customer experience?
AI can support contextual assistance, personalization, automation and proactive service, but its effectiveness depends on the quality of the underlying customer strategy, data, journeys and governance.
Why does banking CX require governance?
Banking experiences continually evolve through new features, regulations, technologies and teams. Governance helps keep local decisions aligned with shared experience principles and prevents fragmentation from accumulating over time.
Get UXDA Research-Based White Paper "How to Win the Hearts of Digital Customers":
Turn Customer Experience Into an Institutional Capability
UXDA partners with banks and financial institutions to diagnose experience gaps, define target customer experiences and build the systems needed to improve them at scale. Through customer research, Systemic UX, Digital Brand Identity and experience governance, we connect customer needs with business strategy, products, technology and operations.
- E-mail us at info@theuxda.com
- Chat with us in Whatsapp
- Send a direct message to UXDA's CEO Alex Kreger on Linkedinmove in the same direction